While it is impossible to predict where the S&P will be in 10 years (or even
1), one can safely make some assumptions about what the world will look like in
a decade (assuming of course it hasn't blown up by then). It will be hungry, it
will be thirsty, it will demand resources, and it will be crowded (and it will
certainly have lots and lots of wheelbarrows carrying pieces of paper to and fro
the local bakery). Implicitly then, countries which control the production and
export of various key natural resources and commodities channels will become
increasingly more strategic and important. However, for some economies, such as
the Middle East, whose entire export-based welfare is reliant on a core set of
commodities, this export-benefit may be a doubled-edged sword, should it lead to
militant antagonism by one time friends and outright enemies, and/or complacency
leading to lack of revenue stream diversity. In order to determine who the key
resource players in the future will be, we present the below commodity trade
matrix which answers two questions: how important is a commodity to a country,
and how important is a country to a commodity. As GS notes, those on the riskier
side of this equation are economies that are heavily reliant on oil, such as the
Middle East or even Russia (which albeit scores better on other hard
commodities). On the other hand, food exporters enjoy relatively better
diversity in their trade portfolios. We highlight the LatAm economies here,
while Canada and the US also look healthy. Will food (and water) be the oil of
the future, and will the next resource war be not over black, or even yellow,
gold, but, pardon the pun, edible gold?
Some additional observations via Goldman:
Not all countries are blessed with abundant resources, and even among those
that are, some countries have benefitted a great deal more than others as a
result of the quality of their institutions. Indeed, resource wealth can, and
has, tempted institutions to retain the revenues narrowly, rather than
distribute them broadly or develop others parts of the economy. This is the
reason why the presence of resources hasn’t historically guaranteed economic
success. Australia, Canada, Russia, Brazil and South Africa are countries that
have high levels of hard commodities per capita, while Argentina and the US
should be added to the list if soft commodities are included.
But what are the resources of the future? We think it very likely that food,
water and therefore land, will become increasingly important, tilting the
advantage in favour of those capable of feeding the next billion people. As two
of the world’s largest populations industrialise (hence producing less of their
own food) and become wealthier (and hence hungrier), the way food flows around
the world is likely to change significantly. Russia, South Korea, Japan and much
of Western Europe are major food importers currently, while Brazil, Argentina,
the US, Australia, Thailand and Canada sit on the other end of food trade. Here
we have to mention Africa and India as regions with huge potential, but in need
of greater institutional support to deliver it.
The current debate on the resources curse (the potential for resource-rich
countries to become imbalanced) is also important. Being heavily reliant on a
particularly commodity is risky as a result of the possibility of big shifts in
the global economy, innovation-led substitutes or new discoveries. It is not
implausible, for example, to imagine EM consumers extinguishing their demand for
cigarettes just like their health conscious Western brethren did a few decades
ago. This puts tobacco-heavy African economies like Zimbabwe at significant
risk. Above is a commodity trade matrix to answer two entwined questions: how
important is a commodity to a country, and how important is a country to a
commodity? As expected, those on the riskier side of this equation are economies
that are heavily reliant on oil, such as the Middle East or even Russia (which
albeit scores better on other hard commodities). On the other hand, food
exporters enjoy relatively better diversity in their trade portfolios. We
highlight the LatAm economies here, while Canada and the US also look
healthy.
The last question is which countries have succeeded despite resource
deficits? Japan and South Korea stand out here, which cements our argument that
necessity, in this case driven by constraints, is the mother of innovation.
September 21, 2012
September 20, 2012
New Study Finds “Severe Toxic Effects” of Pervasively Used Monsanto Herbicide Roundup and Roundup Ready GM Corn
Although I generally refrain from posting on Big Ag and relegate the topic to Links, I have a special interest in Monsanto. Last year, I had wanted to devise a list or ranking of top predatory companies, but could not find a way to make the tally sufficiently objective to be as useful in calling them out as it ought to be. Nevertheless, no matter how many ways I looked at the issue, it was clear that any ranking would put Monsanto as number 1. Monsanto has (among other things) genetically engineered seeds so that they can’t reproduce, denying farmers the ability to save seeds and have a measure of financial independence. In 2009, Vandana Shiva estimated that 200,000 farmers in India had committed suicide since 1997, and Monsanto was a major culprit:
I also know a wee bit about Monsanto because I was on its client team as a very junior investment banker at Goldman in the early 1980s. It was then a specialty chemical company, with the herbicide Roundup as the driver of its profits. The Goldman bankers and analysts were aware that Monsanto was effectively a one-trick pony, and that the St. Louis company was exposed both to the end of its patent and the possibility of Roundup-resistant weeds developing. Monsanto managed to extend the life of its patent both legally and far more important, practically, via the genetic engineering described above. The result is that Roundup has been far and away the most widely used herbicide in the US for over 30 years.
And that little fact makes a newly-released study particularly troubling. The study, by Dr. Joel Spiroux and Professor Gilles-Eric Seralini, was published in Food and Chemical Toxicology as “Long term toxicity of a herbicide Roundup and Roundup-tolerant genetically has modified maize.” The authors are both members of CRIIGEN (Committee for Research and Independent Information). Per the summary on the CRIIGEN website (furzy mouse):
But from my perspective, the more troubling part is the finding of Roundup toxicity. As the study suggests, Roundup is pervasive, it’s even in the water. If it is toxic to the degree this analysis suggests, we may be at the beginning of a large scale legal battle, similar to the suits against Big Tobacco, where the science was initially disputed but the link between smoking and lung cancer was eventually confirmed.
The problem is that if the study’s findings are valid, it will be hard to stuff this evil genie back in the bottle. But Europeans, particularly the French, have long been leery of GMOs and Big Ag generally, and this study may be the opening salvo in a serious pushback effort.
Update 4:30 AM: Below is the published article. Be sure to look at the photos.
Long Term Toxicity of Roundup Herbicide…
Read more
In 1998, the World Bank’s structural adjustment policies forced India to open up its seed sector to global corporations like Cargill, Monsanto and Syngenta. The global corporations changed the input economy overnight. Farm saved seeds were replaced by corporate seeds, which need fertilizers and pesticides and cannot be saved.Monsanto’s seeds can also sterilize wild crops via contamination. And Monsanto routinely sues farmers who wind up having some Monsanto seeds by virtue of seeds from neighboring farms blowing onto their property.
Corporations prevent seed savings through patents and by engineering seeds with non-renewable traits. As a result, poor peasants have to buy new seeds for every planting season and what was traditionally a free resource, available by putting aside a small portion of the crop, becomes a commodity. This new expense increases poverty and leads to indebtness.
The shift from saved seed to corporate monopoly of the seed supply also represents a shift from biodiversity to monoculture in agriculture. The district of Warangal in Andhra Pradesh used to grow diverse legumes, millets, and oilseeds. Now the imposition of cotton monocultures has led to the loss of the wealth of farmer’s breeding and nature’s evolution.
Monocultures and uniformity increase the risk of crop failure, as diverse seeds adapted to diverse to eco-systems are replaced by the rushed introduction of uniform and often untested seeds into the market. When Monsanto first introduced Bt Cotton in 2002, the farmers lost 1 billion rupees due to crop failure. Instead of 1,500 kilos per acre as promised by the company, the harvest was as low as 200 kilos per acre. Instead of incomes of 10,000 rupees an acre, farmers ran into losses of 6,400 rupees an acre. In the state of Bihar, when farm-saved corn seed was displaced by Monsanto’s hybrid corn, the entire crop failed, creating 4 billion rupees in losses and increased poverty for desperately poor farmers. Poor peasants of the South cannot survive seed monopolies. The crisis of suicides shows how the survival of small farmers is incompatible with the seed monopolies of global corporations.
I also know a wee bit about Monsanto because I was on its client team as a very junior investment banker at Goldman in the early 1980s. It was then a specialty chemical company, with the herbicide Roundup as the driver of its profits. The Goldman bankers and analysts were aware that Monsanto was effectively a one-trick pony, and that the St. Louis company was exposed both to the end of its patent and the possibility of Roundup-resistant weeds developing. Monsanto managed to extend the life of its patent both legally and far more important, practically, via the genetic engineering described above. The result is that Roundup has been far and away the most widely used herbicide in the US for over 30 years.
And that little fact makes a newly-released study particularly troubling. The study, by Dr. Joel Spiroux and Professor Gilles-Eric Seralini, was published in Food and Chemical Toxicology as “Long term toxicity of a herbicide Roundup and Roundup-tolerant genetically has modified maize.” The authors are both members of CRIIGEN (Committee for Research and Independent Information). Per the summary on the CRIIGEN website (furzy mouse):
For the first time, the health impact of a GMO and a widely used pesticide have been comprehensively assessed * in a long term animal feeding trial of greater duration and with more detailed analyses than any previous studies, by environmental and food agencies, governments, industries or researchers institutes.The difference between this study and most studies of toxicity is the duration of the exposure. Analyses for regulatory purposes are only 3 months in length, while this was two years (which is pretty close to a normal rat lifespan, or at least for rats as pets). The sample size, 200 animals, is large enough that the findings can’t be dismissed casually. CRIIGEN, a not for profit with a large roster of scientific advisors, is making an aggressive push and launching a related book and documentary. But CRIIGEN can’t be depicted as knee jerk anti GMO. In an interview, Dr. Spiroux stressed that he approved of the use of transgenic GMOs to produce medication, such as insulin, but that he and other CRIIGEN members are opposed to “pesticides plants that are agricultural GMOs and above all are poorly evaluated.” And he is far from alone. A burger eating buddy (as in no sanctimonious health foodie) who is a biomedical engineer whose first job was with the NIH would get agitated on the subject of GMOs, complaining it was a mass scale, uncontrolled experiment on the public at large. He even tried avoiding GMOs but found it too difficult and gave up.
The two tested products are in very common use : (i) a transgenic maize made tolerant to Roundup, the characteristic shared by over 80% of food and animal feed GMOs, and (ii) Roundup itself, the most widely used herbicide on the planet. The regulatory approval process requires these products to be tested on rats as a surrogate for humans.
The new research took the form of a two year feeding trial on 200 rats, monitored for outcomes against more than 100 parameters. The doses were consistent with typical dietary/ environmental exposure (from 11% GMO in the diet, and 0.1 ppb in water).
The results, which are of serious concern, included increased and more rapid mortality, coupled with hormonal non linear and sex related effects. Females developed significant and numerous mammary tumours, pituitary and kidney problems. Males died mostly from severe hepatorenal chronic deficiencies. Professor Seralini’s team in the University of Caen is publishing this detailed study in one of the leading scientific international peer-reviewed journals of food toxicology, on line on Sept. 19, 2012.
The implications are extremely serious. They demonstrate the toxicity, both of a GMO with the most widely spread transgenic character and of the most widely used herbicide, even when ingested at extremely low levels, (corresponding to those found in surface or tap water). In addition, these results call into question the adequacy of the current regulatory process, used throughout the world by agencies involved in the assessment of health, food and chemicals, and industries seeking commercialisation of products.
But from my perspective, the more troubling part is the finding of Roundup toxicity. As the study suggests, Roundup is pervasive, it’s even in the water. If it is toxic to the degree this analysis suggests, we may be at the beginning of a large scale legal battle, similar to the suits against Big Tobacco, where the science was initially disputed but the link between smoking and lung cancer was eventually confirmed.
The problem is that if the study’s findings are valid, it will be hard to stuff this evil genie back in the bottle. But Europeans, particularly the French, have long been leery of GMOs and Big Ag generally, and this study may be the opening salvo in a serious pushback effort.
Update 4:30 AM: Below is the published article. Be sure to look at the photos.
Long Term Toxicity of Roundup Herbicide…
Read more
September 19, 2012
Matt Taibbi: The People Vs. Goldman Sachs
To fully grasp the case against Goldman, one first needs to understand that the financial crime wave described in the Levin report came on the heels of a decades-long lobbying campaign by Goldman and other titans of Wall Street, who pleaded over and over for the right to regulate themselves.
Before that campaign, banks were closely monitored by a host of federal regulators, including the Office of the Comptroller of the Currency, the FDIC and the Office of Thrift Supervision. These agencies had examiners poring over loans and other transactions, probing for behavior that might put depositors or the system at risk. When the examiners found illegal or suspicious behavior, they built cases and referred them to criminal authorities like the Justice Department.
This system of referrals was the backbone of financial law enforcement through the early Nineties. William Black was senior deputy chief counsel at the Office of Thrift Supervision in 1991 and 1992, the last years of the S&L crisis, a disaster whose pansystemic nature was comparable to the mortgage fiasco, albeit vastly smaller. Black describes the regulatory MO back then. "Every year," he says, "you had thousands of criminal referrals, maybe 500 enforcement actions, 150 civil suits and hundreds of convictions."
But beginning in the mid-Nineties, when former Goldman co-chairman Bob Rubin served as Bill Clinton's senior economic-policy adviser, the government began moving toward a regulatory system that relied almost exclusively on voluntary compliance by the banks. Old-school criminal referrals disappeared down the chute of history along with floppy disks and scripted television entertainment. In 1995, according to an independent study, banking regulators filed 1,837 referrals. During the height of the financial crisis, between 2007 and 2010, they averaged just 72 a year.
But spiking almost all criminal referrals wasn't enough for Wall Street. In 2004, in an extraordinary sequence of regulatory rollbacks that helped pave the way for the financial crisis, the top five investment banks — Goldman, Merrill Lynch, Morgan Stanley, Lehman Brothers and Bear Stearns — persuaded the government to create a new, voluntary approach to regulation called Consolidated Supervised Entities. CSE was the soft touch to end all soft touches. Here is how the SEC's inspector general described the program's regulatory army: "The Office of CSE Inspections has only two staff in Washington and five staff in the New York regional office."
Among the bankers who helped convince the SEC to go for this ludicrous program was Hank Paulson, Goldman's CEO at the time. And in exchange for "submitting" to this new, voluntary regime of law enforcement, Goldman and other banks won the right to lend in virtually unlimited amounts, regardless of their cash reserves — a move that fueled the catastrophe of 2008, when banks like Bear and Merrill were lending out 35 dollars for every one in their vaults.
Goldman's chief financial officer then and now, a fellow named David Viniar, wrote a letter in February 2004, commending the SEC for its efforts to develop "a regulatory framework that will contribute to the safety and soundness of financial institutions and markets by aligning regulatory capital requirements more closely with well-developed internal risk-management practices." Translation: Thanks for letting us ignore all those pesky regulations while we turn the staid underwriting business into a Charlie Sheen house party.
Goldman and the other banks argued that they didn't need government supervision for a very simple reason: Rooting out corruption and fraud was in their own self-interest. In the event of financial wrongdoing, they insisted, they would do their civic duty and protect the markets. But in late 2006, well before many of the other players on Wall Street realized what was going on, the top dogs at Goldman — including the aforementioned Viniar — started to fear they were sitting on a time bomb of billions in toxic assets. Yet instead of sounding the alarm, the very first thing Goldman did was tell no one. And the second thing it did was figure out a way to make money on the knowledge by screwing its own clients. So not only did Goldman throw a full-blown "bite me" on its own self-righteous horseshit about "internal risk management," it more or less instantly sped way beyond inaction straight into craven manipulation.
"This is the dog that didn't bark," says Eliot Spitzer, who tangled with Goldman during his years as New York's attorney general. "Their whole political argument for a decade was 'Leave us alone, trust us to regulate ourselves.' They not only abdicated that responsibility, they affirmatively traded against the entire market."
Read the entire artire
September 18, 2012
Faber's 'Fed Counterfeiting' Remark is Unusual but Not Extreme These Days
Marc Faber: If I Were Bernanke, I Would Resign ... Central bankers are "counterfeit money printers" and Federal Reserve Chairman Ben Bernanke should resign for messing up the U.S. economy so badly, Marc Faber, author of the Gloom, Doom and Boom, told CNBC on Friday. He said Bernanke was one of the main proponents of an ultra-expansionist economic monetary policy that was to blame for the latest financial crisis. "If I had messed up as badly as Bernanke I would for sure resign. The mandate of the Fed to boost asset prices and thereby create wealth is ludicrous — it doesn't work that way. It's a temporary boost followed by a crash," Faber said. – CNBC
Dominant Social Theme: The Fed is triumphing slowly but surely.
Free-Market Analysis: This is fairly unprecedented. A so-called mainstream economist and investor, Marc Faber, has accused the Federal Reserve of "counterfeiting."
While Faber is certainly on the conservative/libertarian side of the spectrum, his views have been popularly disseminated by the mainstream media for years.
For us, such statements confirm the crumbling of the elite's central banking dominant social theme. We predicted several years ago now that the Fed had lost any claim to the moral high ground.
Once it became clear to people that Fed officials were printing TRILLIONS during a time of great financial pain for ordinary people, the Fed, we believed, would become an object of popular anger.
That process is well underway. To see some previous articles on this issue, search the Internet for "Daily Bell" along with the terms "Fed" and "morality" and "inspector general."
This unraveling must be of great concern to the power elite that relies on central banking to fund its push toward one-world government. But we have also predicted that within the context of what we call the Internet Reformation, there would be nothing much the elites could do about it.
We do believe that the power elite has, perhaps, cleverly launched a pure fiat counterattack, acknowledging that the public/private Fed model is probably done for and seeking to sway public opinion toward an entirely government focused option.
The elites, in our view, don't care whether or not monopoly fiat central banking is conducted "privately" or by government entities. Via mercantilism they will control the process of money printing either way.
Nonetheless, an elite meme – the necessity of monopoly fiat central banking – is becoming increasingly hard to sustain. Faber's attacks, while extreme, are merely a symptom of that.
Again, Faber is not to be considered an outlier. He is a man with significant mainstream credentials. Here's a bit of background on Faber.
Dr. Marc Faber was born in Zurich, Switzerland. He went to school in Geneva and Zurich and finished high school with the Matura. He studied Economics at the University of Zurich and, at the age of 24 obtained a PhD in Economics magna cum laude.
Between 1970 and 1978, Dr. Faber worked for White Weld & Company Limited in New York, Zurich and Hong Kong. Since 1973, he has lived in Hong Kong. From 1978 to February 1990 he was the Managing Director of Drexel Burnham Lambert (HK) Ltd.
In June 1990 he set up his own business, MARC FABER LIMITED, which acts as an investment advisor, fund manager and broker/dealer. Dr. Faber publishes a widely read monthly investment newsletter "THE GLOOM, BOOM & DOOM" report which highlights unusual investment opportunities.
This bio was posted with an interview we did with Dr. Faber in June 2011. You can see the interview here:
Marc Faber on 21st Century Investing, Why It's Too Late for the Dollar and Why Emerging Markets Look Good
The article excerpted above reminds us that Dr. Faber's perspective on finance and monetary stimulation has reaped rewards for investors as far back as 1987, when he received media credit for predicting the 1987 stock market crash.
What's unusual about Faber's stance is that he's chosen to be even more outspoken than usual. For anyone in the "mainstream" to characterize central banking operations as counterfeiting is newsworthy. But Faber didn't stop there. Here's some more from the article:
"This unlimited QE (quantitative easing), buying mortgage-backed securities (MBS) and continuing operation twist has the implication of simply having asset prices go up and the money flows down to the Mayfair economy," Faber said.
A Mayfair economy is one which benefits the wealthier and better off in society. Faber said this latest round of QE would not help the "man on the street".
"QE helps rich people whose asset prices go up and whose net worth then increases but it doesn't flow to the man on the street who is faced with higher costs of living with price rises. You just have a small economy that is booming but the majority of the economy is damaged by QE," he said.
This is strong stuff because Faber is essentially explaining that Ben Bernanke's approach to the market is not helpful for ordinary citizens. Usually, mainstream pundits go along with the idea that central bank price-fixing provides valuable support for the economy as a whole.
The proximate cause of Faber's statements is the announcement by Bernanke that the Fed would buy $40 billion a month in MBS, in order to unfreeze the mortgage market and give homeowners the chance to refinance.
Surprisingly, Bernanke's announcement has been met with some skepticism within the mainstream. Sorting through the commentary, one is struck by the increasing resistance to portray the Fed as being helpful to the larger economy.
Perhaps the media is merely acknowledging public sentiment, or perhaps mainstream participants themselves are growing impatient.
It is widely acknowledged that the Fed's money printing has boosted stock prices, which have more than doubled in aggregate within the US. But tens of millions are out of work. As much as 30 or even 40 percent of the US workforce probably suffers from lack of employment or unemployment.
Within this context, Faber's statements are unusual but not radical. His sentiments are increasingly echoed by others despite their forceful nature.
"The money printers are responsible for this crisis. If we continue with this expansionist monetary policy we won't be facing a fiscal cliff it will be a fiscal grand canyon," he added.
We try to chart reactions to dominant social themes because they can reveal larger potential changes when it comes to the economy and what actions the top elites may take. It seems to us that the militarism now spreading around the world is a direct elite reaction to the challenges to the modern central banking system and to modern economies generally.
There are various other reactions, too, including perhaps surreptitious elite encouragement of pure fiat, alternative money systems. Analyze elite dominant social themes to support a larger comprehension about where the world may be headed. These memes are the building blocks of directed history.
Conclusion: They are not the only tools that one needs to use but they surely deserve to be part of a larger toolkit as elite memes continue to unravel.
September 17, 2012
Is QE3 Yet Another Stealth Bank Bailout?
It’s difficult to puzzle out what Bernanke thinks he is accomplishing with QE3. The level of bond buying, as various commentators have pointed out, is much lower than in the earlier QE programs. And pulling out bigger guns in the past was not terribly productive. As we wrote in April 2011 in a post titled “Mirabile Dictu! Economists Agree All the Fed Has Done is Goose Financial Markets!“:
You heard it first in the blogopshere. From the New York Times:
The Federal Reserve’s experimental effort to spur a recovery by purchasing vast quantities of federal debt has pumped up the stock market, reduced the cost of American exports and allowed companies to borrow money at lower interest rates.
But most Americans are not feeling the difference, in part because those benefits have been surprisingly small. The latest estimates from economists, in fact, suggest that the pace of recovery from the global financial crisis has flagged since November, when the Fed started buying $600 billion in Treasury securities to push private dollars into investments that create jobs….
A study published in February found that interest rates decreased, but only for companies with top credit ratings. “Rates that are highly relevant for households and many corporations — mortgage rates and rates on lower-grade corporate bonds — were largely unaffected by the policy,” wrote Arvind Krishnamurthy and Annette Vissing-Jorgensen, both finance professors at Northwestern University
We’ve argued repeatedly, as have others, that well targeted fiscal stimulus and more private sector debt restructuring were the right medicine. But Obama and his bankster friendly advisors had no stomach for much of either remedy.
For what it’s worth, QE and QE2 have gotten a barrage of criticism. Jim Hamilton looked at the much bigger first round of QE and concluded that it lowered long bond yield by only 17 basis points. Paul Volcker thought making a fuss over the program was silly, since the Fed used to buy bonds as a matter of course. And as Marshall Auerback has pointed out, the idea of a fixed dollar amount of purchases was bizarre. There was no way of knowing what if anything it would accomplish. It would have made more sense for the central bank to set a rate target (say for whatever longer-dated maturity it chose to target) and buy whatever it took to keep that level.
You could argue that the big impact of the QEs was psychological, that it was tangible proof that the Bernanke put was the Greenspan put on steroids.
Back to the current post. Given that previous QEs amped up the stock market, weakened the dollar, lifted commodity prices, and made central bankers in emerging markets mighty unhappy (risk on trades boosted their currencies and sent hot money into their economies, developments they did not like), all on a temporary basis, it’s quite a stretch for Bernanke to depict it as a way to boost employment in the US, unless he has a very bad case of “if the only tool you have is a hammer, every problem looks like a nail” syndrome.
One interpretation is that Bernanke, despite his protests otherwise, is giving the stock market a short term sugar high to assure an Obama reelection. The Republicans have threatened to take hot pokers to the Fed, so Bernanke could rationalize his actions as preserving his institution rather than mere electioneering.
Another is that the central bank is quite cognizant of what it is doing and is deliberately boosting bank profits, perhaps also hoping that the banks will eventually feel robust enough to do more lending. The wee problem is that financial speculation is so much more profitable and much easier to dial up and down quickly.
Even though mortgage backed securities prices rose (as in interest rates fell) sharply after QE3 was announced, mortgage rates remained unchanged:
The average rate on a 30- year fixed mortgage held at 3.55 percent in the week ended Sept. 13, near a record-low of 3.49 reported July 26 in data dating to 1971, according to McLean, Virginia-based Freddie Mac.
The New York Times’ Dealbook on Friday evening took note of the failure of banks to lower borrower interest rates in light of more favorable funding costs:
The federal funds effective rate, one short-term rate that banks use to lend to each other, is at 0.14 percent. That compares with a rate of 3.62 percent in September 2005.
The 10-year Treasury note has a yield of 1.87 percent, down from 4.2 percent in 2005. These are huge declines.
Yet the cost of credit card loans has hardly budged. The Fed’s own data shows that average credit card interest rate was 12.06 percent earlier this year; in 2005, it was 12.45 percent…
But even when fear of default is removed from the equation certain interest rates seem to be stuck too high.
Take mortgages. The federal government agrees to shoulder the cost of defaults in nearly all of the mortgages made today. Banks make mortgages to borrowers, and then take those loans and attach the government guarantee of repayment to them.
After that, they package the loans into bonds, which they then sell to investors. The Fed’s purchases of these bonds have helped their yields fall to 2.2 percent. But the cost of mortgages to borrowers hasn’t fallen anywhere near as much.
The banks are choosing not to reduce mortgage rates further. One reason: By keeping the rates elevated, they are able to earn much larger profits when they sell the mortgages into the bond market. If the level of profits on those sales stayed at recent average levels, borrowers might, for instance, pay $30,000 less in interest payments on a $300,000 mortgage, according to a recent New York Times analysis.
Today, the Financial Times took note of the issue, but added a bit of bank PR: they really, truly want to lend more, but golly gee, they haven’t staffed up:
The Federal Reserve’s attempt to push aid into the heart of the US economy is being blunted by banks struggling to process mortgage applications fast enough, keeping rates on home loans elevated, according to the largest lenders.
“In the very near term [QE3] has virtually no transfer mechanism whatsoever to the customer,” said one executive at a leading lender, who requested anonymity. “Originators are massively backlogged in terms of origination volumes.”
Steven Abrahams, MBS analyst at Deutsche Bank, noted that the yield on mortgage-backed securities fell more than 30 basis points after the Fed announcement.
“Very little of that is likely to make it through immediately to consumers,” he said. “There’s nothing that will force mortgage originators themselves to lower the rates that they’re offering to consumers. Right now they have their hands pretty full in terms of the pipeline and managing paperwork and making loans. These folks are busy. There’s not a bunch of people on long cigarette breaks.”
MBS Guy confirmed our skeptical view:
No one on the planet can be surprised that mortgage rates are very low and refinancing is attractive (few bank executives should be surprised by QE3, plus they’ve all been banging on the table for it for the last few months).
Yet, for some reason, banks don’t have the staffing to originate loans faster, as if they were somehow unprepared for this environment. It’s preposterous.
The only explanation: lenders don’t want to originate any faster.
They want to capture more spread and, perhaps, they want fewer people to lock in at lower rates?
Nonetheless, QU3 will be a huge opportunity for bankers to make a lot more trading revenue and come up with new strategies to leverage and arb the new regulatory environment. The Fed basically confirmed low rates and continuous MBS purchases through 2015 – that provides a lot of opportunity to make money. Lending, however, is an afterthought.
Note that there has not been a peep out of the Fed on the failure of the banks to lower borrower rates to reflect their cheaper funding costs. The central bank has a powerful bully pulpit, and if it were to make noise, you’d see Congresscritters and the media piling on. One wonders if the Fed has even broached the topic privately. I can imagine Jamie Dimon grousing about the loss of profits on float and the flatter yield curve justifying them taking margin wherever they find it, and the Fed unwilling to point out that the banks created the new normal and they need to adjust to it too.
So the Fed looks to be completely on board with this sort of rent-seeking. Perhaps the central bank believes its charges need more in the way of earnings to strengthen their balance sheets, even though history shows they prioritize executive bonuses over building their equity levels. Or maybe Bernanke was being completely truthful when he said QE3 was targeting employment. After all, fatter bank margins will preserve their staffing levels.
September 14, 2012
The Fed's Balance At The End Of 2013: $4 Trillion
What happens next:
•Imminently, the Fed's Open Markets Operations desk will commence buying $40 billion in MBS per month, or about $10 billion each week. Concurrently, the Fed which is continuing Operation Twist, will still purchase $45 billion in "longer-term" Treasurys, sterilized by the $45 billion or so in 1-3 years Bonds it will sell until the end of the year at which point it runs out of short-term paper to sell.
End result: every month through the end of 2012, the Fed's balance sheet expands by $40 billion in MBS.
•Beginning January 1, 2013 the Fed will continue monetizing $40 billion in MBS each month, and will continue Operation Twist, however it will adjust the program so that it continues to increase its long-term holdings at $85 billion per month, without sterilization as it will no longer have short-term bonds to sell. It will also need to extend its ZIRP language "through the end of 2016" so all bonds 1-3 years are essentially risk free, as they are now, in effect eliminating the need to sell them.
End result: every month in 2013 the Fed will increase its balance sheet by $85 billion, consisting of $40 billion in MBS, and $45 billion in 10-30 year Treasurys, or the natural monthly supply of longer-dated issuance. The Fed will therefore monetize roughly half of the US budget deficit in 2013.
Putting it all together, the Fed's balance sheet will increase from just over $2.8 trillion currently, to $4 trillion on December 25, 2013. A total increase of $1.17 trillion.
This is what the Fed's balance sheet will looks like:

Another way of visualizing this is how many assets as a percentage of US GDP the Fed will hold on its books. Currently, this number is 18%. By the end of 2013, the Fed's historical flow operations will be accountable for 24% of US GDP.

Why is this important? Simple: when the time comes for the Fed to unwind its balance sheet, if ever, the reverse Flow process will be responsible for deducting at least 24% of US GDP at the time when said tightening happens. If ever.
What is scariest, is that as of this moment, all of this is priced in. Any incremental gains in the stock market will have to come from additional easing over and above what Bernanke just announced.
And finally: Fed's DV01 at December 31, 2013: ~$4 billion
•Imminently, the Fed's Open Markets Operations desk will commence buying $40 billion in MBS per month, or about $10 billion each week. Concurrently, the Fed which is continuing Operation Twist, will still purchase $45 billion in "longer-term" Treasurys, sterilized by the $45 billion or so in 1-3 years Bonds it will sell until the end of the year at which point it runs out of short-term paper to sell.
End result: every month through the end of 2012, the Fed's balance sheet expands by $40 billion in MBS.
•Beginning January 1, 2013 the Fed will continue monetizing $40 billion in MBS each month, and will continue Operation Twist, however it will adjust the program so that it continues to increase its long-term holdings at $85 billion per month, without sterilization as it will no longer have short-term bonds to sell. It will also need to extend its ZIRP language "through the end of 2016" so all bonds 1-3 years are essentially risk free, as they are now, in effect eliminating the need to sell them.
End result: every month in 2013 the Fed will increase its balance sheet by $85 billion, consisting of $40 billion in MBS, and $45 billion in 10-30 year Treasurys, or the natural monthly supply of longer-dated issuance. The Fed will therefore monetize roughly half of the US budget deficit in 2013.
Putting it all together, the Fed's balance sheet will increase from just over $2.8 trillion currently, to $4 trillion on December 25, 2013. A total increase of $1.17 trillion.
This is what the Fed's balance sheet will looks like:
Another way of visualizing this is how many assets as a percentage of US GDP the Fed will hold on its books. Currently, this number is 18%. By the end of 2013, the Fed's historical flow operations will be accountable for 24% of US GDP.
Why is this important? Simple: when the time comes for the Fed to unwind its balance sheet, if ever, the reverse Flow process will be responsible for deducting at least 24% of US GDP at the time when said tightening happens. If ever.
What is scariest, is that as of this moment, all of this is priced in. Any incremental gains in the stock market will have to come from additional easing over and above what Bernanke just announced.
And finally: Fed's DV01 at December 31, 2013: ~$4 billion
September 13, 2012
Can the SEC Improve if it Does Not Perform a Viable Function?
The Great Debate ... Can the SEC ever improve? ... The U.S. Securities and Exchange Commission's case against Citigroup's Brian Stoker, a director in the bank's Global Markets group, seemed clear-cut. Stoker structured and marketed an investment portfolio consisting of credit default swaps. The agency accused him of misrepresenting deal terms and defrauding investors for not disclosing the bank's bet against the portfolio while pitching the investment vehicle to customers. But when it came to trial earlier this summer, the government could not prove that Stoker knew or should have known that the pitches were misleading, and the jury didn't convict. It's hardly surprising. The SEC's failure to secure a guilty verdict is one more sign that the commission still has not climbed out of the morass in which it was mired for most of the Bush years. The agency tasked with overseeing some 5,000 broker-dealers, 10,000 investor-advisers, 10,000 hedge funds, and 12,000 public companies, as well as mutual funds, the exchanges and even the rating agencies, is ailing because of outdated rules, systems and structures. – Reuters
Dominant Social Theme: It needs tweaking but it is a good agency.
Free-Market Analysis: We've written about the dysfunction of the SEC quite a bit and we know where we stand on the SEC's viability ... It never was viable.
The main idea behind the SEC is to force individuals to provide full disclosure of their financial offering in such a way as they can be sued civilly. But like all other regulatory authorities, the SEC doesn't work as planned.
In fact, regulation generally is a price-fix and price-fixes transfer wealth from those who generate it to those who didn't generate it and don't know how to apply it effectively.
The Reuters editorial takes a slightly different stance, of course. Reuters is evidently a limb of money power and thus promotes regulatory democracy. Money Power seeks regulatory democracy because it seeks world government as well and needs to use nation-state governmental mechanisms to realize its goals.
This larger methodology is called mercantilism and it conflates private interests with the public purse. The power elite drives its globalist agenda via government. Here's some more from the article:
What exactly ails the SEC? For starters, the legal framework in place to prosecute securities fraud is flawed. The commission was established to create rules that prohibit "any manipulative or deceptive device or contrivance." But intent or recklessness is required to prove fraud or misrepresentation, and that can be difficult because the agency doesn't have enough staff to comb through reams of documents for rare evidence that someone intended to cheat ...
Another glaring structural problem at the agency is that any changes in securities laws require congressional approval, but the SEC also relies on Congress for annual appropriations to continue running.
... The U.S. Treasury Department collects $2.94 trillion in revenue, which runs its core operations. The Federal Deposit Insurance Corporation runs on taxes from banks that form its membership. If the SEC were funded. Independently, securities fraud would presumably be more easily and effectively regulated and prosecuted.
The SEC's bureaucracy is a common complaint among bankers, traders and other financial services workers. Officials spend years launching, investigating and charging parties engaged in wrongdoing. In June, Peter Madoff was charged with fraud, four long years after his brother Bernie. It took a decade for the SEC to hold an Ohio fraudster accountable financially, except by then he was no longer living ...
Finally, the agency also suffers from low morale. Last year, the SEC ranked 27th out of 33 federal agencies for workplace happiness, according to a survey by the Partnership for Public Service. In 2007, it came in third. The revolving-door issue also is worth repeating. Young lawyers who start their careers in government often do so to jump, eventually, into the private sector.
Let's take these points one at a time. First, the SEC was indeed established for purposes of mitigating fraud. But this was a great deal different than establishing a policing agency. The SEC is not the FBI of the securities industry.
The SEC was established as basically a civil agency because Money Power that controls the larger securities industry did not want its appendages exposed to criminal risk. It is easy to pay a fine but hard to run a business from behind bars.
Most everything that takes place on Wall Street or in the City of London is broadly fraudulent as it must be since money itself is a monopoly fraud and broadly unconstitutional.
For instance, there is little capital available from institutions these days because most capital is tied up in Treasuries. The Fed charges a tiny amount for borrowing from the discount window and the banks in turn invest that money in Treasuries.
It is yet another kind of almost "risk-free" carry trade and one that guarantees banks some two percent on their money. It is the money center banks that are funding governments with faux money created by central banks. This is a vast illegality but the SEC won't investigate it.
The suggestion is made in this Reuters article that the SEC ought to be able to self-fund based on penalties it collects. But the SEC's rules, from insider trading to securities fraud, are vague, opinionated and in many cases devoid of common sense. To encourage the SEC to make and apply more of these rules in order to generate revenue would poison what is left of the securities industry, especially its smaller players.
The last two points about the clumsiness of the bureaucracy and the low morale of the agency are tied together. What people who join government agencies soon come to realize is that they don't really DO anything.
People in government agencies want a paycheck and are motivated to either enforce rules rigidly and unreasonably or to "pass the buck" to someone else. The idea is to collect a paycheck with the least risk possible. This is not conducive either to high morale or to efficiency.
In fact, the SEC – and all regulatory agencies of Western democracies, for that matter – function mostly as promotions. They are promulgated by Money Power to justify government. Money Power NEEDS government for its own purposes and thus must provide memes proving government is utile.
It was the Federal Reserve that overprinted money illegally and caused the great crash of 1929. But Wall Street was blamed and the SEC was created along with the strange idea of a "public market."
The SEC and other regulatory markets were not created for purposes of "improvement." They were created to trick people about the nature of government.
It is the market itself that can discipline its participants. Those who cheat or otherwise provide little or no value shall not long survive. It is always thus.
Conclusion: The idea that markets need "policing" is one developed by those who want to justify government. But justifying government and providing a useful function are two separate things. For more on these issues, search the 'Net for "SEC" and "Daily Bell" or "insider trading" and "Daily Bell."
September 12, 2012
Is There Any Value at Citigroup? Nom de Plumber on Basel III Dysfunction
In this issue of The Institutional Risk Analyst, we feature a comment from our friend Nom de Plumber, a risk analyst at a major NY bank, about the train wreck we all know as Basel III. But first we want to start off with some additional comments about the presentation by IRA Vice Chairman Christopher Whalen this Tuesday in New York at the investment conference sponsored by BCA Research.
The title of the panel is "IS THE BANKING SECTOR IN SECULAR DECLINE?" The answer to that provocative question is yes and no. Yes the US banking sector is reverting to the mean in terms of equity and asset returns, and business models. But no, this is not so much a decline as a return to normal. Click the link below to read Whalen's presentation, including a summary of the top-level Q2 2012 bank ratings and analytics published by IRA.
http://www.rcwhalen.com/pdf/BCA_0912.pdf
There was time when bank stocks traded like bonds. Equity returns in good years barely broke out of single digits. Those few banks which had market traded equity saw betas at or below 1. The reason for this, very simply, was that bank stocks were illiquid and deliberately so. The revenue and earnings of banks were only a concern to a stable group of long-term shareholders. Nobody cared what % of the S&P 500 was attributable to bank stocks.
Over the past 20 years, however, banks have been turned into speculative vehicles as growing public sector debt, grotesque monetary policy by the Fed and ridiculous public policies in Washington regarding the housing sector have forced banks to become hedge funds. Today the largest banks do not serve the economy so much as feed upon it in a parasitic fashion, creating risk in ways and amounts that cannot even be measured accurately.
Notice in the charts for the BCA presentation that Citigroup ("C") is used as a comparison to the large bank peer group in terms of defaults, recoveries and exposure. Notice that C's default rate is well above the peer average, which includes C in the calculation. With a beta close to 2 and a loss rate a standard deviation above the peer group average (excluding Citi), only a complete idiot would be willing to hold C as a long term "investment" unless that bank compensated for the additional risk in terms of an increased dividend payout. But that is not the case.
C currently offers a dividend yield of 0.1% vs. 3.1% for JPMorgan Chase ("JPM"), 2.5% for Wells Fargo ("WFC") and 0.5% for Bank America ("BAC"). WFC has a beta of 1.3, JPM is at 1.6 as of the Friday close and BAC is 1.8, just below C. So if you are an "investor" and not a volatility chasing disciple of Jim "Mad Money" Cramer, you buy WFC and JPM. But all of the zombie money center banks are basically volatility plays, not true investments, since all four of these institutions arguably insolvent.
So if C has a higher beta and lower cash flow yield, why would anyone own the stock? The answer, very simply, is volatility. The reason you own C is not as an investment per se, but because the stock is big and moves around a lot. We occasionally hear analysts try to make a case that C represents "value" at current levels, but such arguments don't count for very much where we are concerned. C remains a subprime lender with an above-peer loss rate and a below peer investor payout.
This is not to say that we think people ought to run out and buy WFC. As Whalen noted on Bloomberg Radio today with Tom Keene and Jonathan Weil, WFC's has the most aggressive accounting among the top four money center banks and arguably the worst disclosure. Practices such as booking up front the full profit from residential loans and also taking the value of cross-sell opportunities into current income make us more than a little nauseous when looking at WFC. At 1.34 x book value, WFC is arguably the most overvalued of the top banks.
Of course, none of the above is recognized by the supposed regulators who are meant to supervise C, WFC and the other zombie banks. If the Basel III capital framework was even remotely sensitive to business models, then C would be required to hold substantially more capital per dollar of assets than either JPM or WFC. Instead the minions of mediocrity who populate the federal bank regulatory agencies spend time pondering the unknowable and irrelevant in pursuit of safety and soundness.
Part of the reason that government agencies have turned Basel III into such a complete mess is that the capital framework ignores the single biggest threat to banks and consumers, namely the governments themselves. Thus we saw last month the ECB arguing for less capital to address liquidity concerns generated by the gyrations in the market for government bonds, so called "risk free" assets.
http://www.bloomberg.com/news/2012-08-27/ecb-said-to-urge-weaker-basel-liquidity-rule-on-crisis-concerns.html
"The regulatory mistake is trying to define in advance what should be completely liquid assets under all market scenarios, and then mandating all banks to own them, for the hundred-year flood which happens every ten years (1987 equity crash, 1998 LTCM failure, 2008 global collapse, 2018…..)," notes Nom de Plumber.
"This policy-sponsored version of an ultra-crowded trade will simply spawn the next loss-correlation debacle. Once everybody subsequently needs to sell Basel LCR-compliant assets under stress, which buyers will provide such liquidity? If investors and regulators can know in advance all potential scenarios, we would not be in the fifth year of this global crisis."
A much better approach would be to foster general market liquidity, Nom de Plumber argues, without favoring or disfavoring specific assets, by restoring:
* legal contract sanctity
* loss privatization rather than socialization
* risk-capital sufficiency
* credit market pricing integrity (removal of zero interest-rate policies).
But of course none of these wise prescriptions are likely to be included in the Basel III framework anytime soon. The whole purpose of Basel III, we should recall, is to make the world safe for profligate, insolvent governments and their debt emissions. Going back to the Great Depression and WWII, the entire framework of international finance has been predicated on government debt being the top of the economic food chain. But the financial crisis of 2007 now shows that this assumption is badly flawed.
Rather than giving government debt the lowest risk weighting, Basel III should assign the highest capital charge to government debt and the lowest to top-quality corporate obligations. Instead Basel III seeks to give advantage to government agencies with debt loads that can only be repaid via inflated currencies. These same government and their captive central banks pursue policies that undermine the value of money and of bank assets. Thus Basel III and the governments which sponsor it are doomed to fail, in terms both of keeping banks and currencies safe and sound.
September 11, 2012
"Under True Capitalism, Goldman Sachs Would Not Exist"
The words in the title of this blog come from H. "Woody" Brock, Ph.D, President, Strategic Economic Decisions, Inc., who has other interesting and insightful things to say about capitalism and how it is being played out in America. He contrasts "true" capitalism with crony capitalism.
"Capitalism is an economic system that is based on private ownership of the means of production and the creation of goods or services for profit.[1] Other elements central to capitalism include competitive markets, wage labor and capital accumulation.[2] There are multiple variants of capitalism, including laissez-faire, welfare capitalism and state capitalism. Capitalism is considered to have been applied in a variety of historical cases, varying in time, geography, politics, and culture." (from Wikipedia)
"Crony capitalism is a term describing an economy in which success in business depends on close relationships between business people and government officials. It may be exhibited by favoritism in the distribution of legal permits, government grants, special tax breaks, or other forms of dirigisme[1] Crony capitalism is believed to arise when political cronyism spills over into the business world; self-serving friendships and family ties between businessmen and the government influence the economy and society to the extent that it corrupts public-serving economic and political ideals." (from Wikipedia)
Elsewhere, Ralph Nader describes some of the aspects of capitalism by stating what defines it and at the same time hints at what capitalism should not look like:
--In capitalist society, when business fails, it is not bailed out;
--Business cannot lobby for the benefit of its own position;
--Capitalism works for the good of all, not just the rich;
--Speculation with derivatives, polluting and gambling should not be part of capitalism;
--Capitalism is not solely about profit either for shareholders and top executives.
With the financialization of the economy and the deminuation of manufacturing, capitalism has focused more and more on ways to create huge profits for corporations which comes at the expense of ordinary citizens whose pensions and savings have been diminished and whose employment opportunities have suffered. Wealth has been, and still is being, transferred from the many below to the few at the top. With the fixation on attaining money, new financial innovations (like derivatives and outsourcing labor) have contributed to the rising inequality of wealth.
September 10, 2012
The Real Unemployment Numbers Are Worse Than You Are Being Told
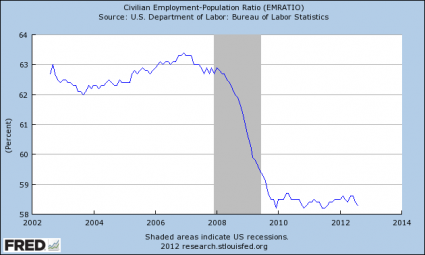
According to the Obama administration, the unemployment rate in the United States has been slowly coming down over the past couple of years. But is that actually true? When you take a closer look at the data you quickly realize that the real unemployment numbers are much worse than we are being told. For example, if the labor force participation rate was the same today as it was back when Barack Obama first took office, the unemployment rate in the United States would be a whopping 11.2 percent. But every month the Obama administration has been able to show "progress" because of the fiction that hundreds of thousands of Americans are "disappearing" from the labor force each month. Frankly, the way that they come up with these numbers is an insult to our intelligence. Personally, I much prefer the employment-population ratio. It is a measure of the percentage of working age Americans that actually have jobs. I like to call it "the employment rate". So what happened to the "employment rate" in August? It fell slightly to 58.3 percent. It is lower than it was when the last recession supposedly ended, and it is almost as low as it has been at any point since the very beginning of this crisis. A few times during this economic downturn it has actually hit 58.2 percent. Needless to say, things are not getting any better. So why aren't the American people being told the truth?
After every other recession in the post-World War II era, the employment rate has always rebounded.
But not this time.
Does this look like a recovery to you?....

So how in the world can Barack Obama claim that we are better off now?
In August 2010, 58.5 percent of working age Americans had jobs.
In August 2012, 58.3 percent of working age Americans had jobs.
So where is the recovery?
It is two years later and a smaller percentage of Americans are employed.
It is very frustrating to me that we are not being told the truth about the unemployment numbers. The following are some more indications that the real unemployment numbers are much worse than we are being told....
-In July, 142,220,000 Americans were working. In August, only 142,101,000 Americans were working. So the number of Americans working fell by 119,000 and yet the government would have us believe that the unemployment rate actually declined from 8.3 percent to 8.1 percent.
-According to the federal government, 96,000 jobs were added to the economy in August and the U.S. labor force shrank by 368,000 even though our population is continually growing. If the size of the U.S. labor force had stayed the same, the official unemployment rate would have actually gone up to 8.4 percent.
-Almost all of the new jobs added in August were the result of the "birth-death" model used by the Labor Department to estimate jobs added by new businesses. That model has been heavily criticized for being inaccurate. If you take the 87,000 jobs added by that model out of the equation, then the U.S. economy only added 9,000 jobs in August. But it takes somewhere around 125,000 new jobs each month just to keep up with the growth of the population.
-If the labor participation rate was sitting where it was when Barack Obama first took office, the unemployment rate in the United States would actually be 11.2 percent.
-If the labor participation rate was sitting at the 30 year average of 65.8 percent, the unemployment rate in the United States would actually be 11.7 percent.
-John Williams of Shadow Government Statistics would put the "real" rate of unemployment up around 23 percent after adding in all workers that have given up looking for work and all underemployed workers.
-The labor participation rate for men has fallen to 69.9 percent. This is the lowest level that it has been since the U.S. government began tracking this statistic back in 1948.
-There was more bad news for manufacturing in this latest report. During the month of August the U.S. manufacturing sector lost approximately 15,000 jobs.
-The official unemployment rate has now been above 8 percent for 43 months in a row.
-The percentage of working age Americans with a job has been below 59 percent for 36 months in a row.
-The employment numbers for both June and July were revised downward significantly. For June, it turns out that only 45,000 jobs were added to the economy as opposed to the 64,000 that were originally reported. For July, it turns out that only 141,000 jobs were added to the economy as opposed to the 163,000 that were originally reported.
-Incredibly, 58 percent of the jobs created since the end of the last recession have been low income jobs.
-The U.S. economy currently has 4.7 million less jobs than it did when the last recession started.
So what is the solution to these problems?
The media is breathlessly proclaiming that more quantitative easing is on the way and that the Federal Reserve will save the economy and send the stock market soaring to new heights.
A headline on CNBC on Friday boldly declared the following: "Market Sees 'Helicopter Ben' Coming to the Rescue".
You can almost hear the chopper blades whirling now.
Apparently Bernanke has had a love of showering the economy with money for a very long time. For example, you can see a picture of a young Ben Bernanke in action right here.
Of course that is a joke, but you get the point.
In recent years Federal Reserve Chairman Ben Bernanke and the rest of his cohorts have printed money like there is no tomorrow.
So have the previous rounds of quantitative easing solved our problems?
Of course not.
The employment rate is even lower today than it was two years ago.
But all of that money printing has sent the stock market soaring and it has enabled the big Wall Street banks to make an obscene amount of money.
The truth is that the Federal Reserve, the Obama administration and the big Wall Street banks don't really care about you.
They don't really care that the middle class is rapidly shrinking and that the number of Americans on food stamps has risen by more than 14 million since Barack Obama became president.
What they care about is what is good for them.
As I have written about previously, if we continue on the same path that we have been on for the past several decades, there will never be enough jobs in America ever again.
On our current trajectory, we will end up just like Greece where the unemployment rate is now up to 24.4 percent.
Once upon a time the economy of Greece was thriving.
But today, many formerly middle class Greek citizens are leaving Greece and are picking up whatever work they can find....
As a pharmaceutical salesman in Greece for 17 years, Tilemachos Karachalios wore a suit, drove a company car and had an expense account. He now mops schools in Sweden, forced from his home by Greece’s economic crisis.
“It was a very good job,” said Karachalios, 40, of his former life. “Now I clean Swedish s---.”
Karachalios, who left behind his 6-year-old daughter to be raised by his parents, is one of thousands fleeing Greece’s record 24 percent unemployment and austerity measures that threaten to undermine growth.
Would you be willing to do that?
Don't laugh.
Someday when the unemployment rate in the United States gets that high we will see large numbers of desperate Americans leaving this country in search of work somewhere else.
Already, an increasing number of Americans are buying expired food at auctions.
Times are hard and people are trying to get by any way that they can.
More than 100 million Americans are already on welfare and things have not even gotten that bad yet.
This is nothing compared to what is coming.
As you can see from the chart posted near the top of this article, the last economic downturn appears to have permanently weakened the U.S. economy.
Now the next wave of the economic collapse is rapidly approaching.
How much worse will things get when it finally hits us?
That is something to think about.
After every other recession in the post-World War II era, the employment rate has always rebounded.
But not this time.
Does this look like a recovery to you?....
So how in the world can Barack Obama claim that we are better off now?
In August 2010, 58.5 percent of working age Americans had jobs.
In August 2012, 58.3 percent of working age Americans had jobs.
So where is the recovery?
It is two years later and a smaller percentage of Americans are employed.
It is very frustrating to me that we are not being told the truth about the unemployment numbers. The following are some more indications that the real unemployment numbers are much worse than we are being told....
-In July, 142,220,000 Americans were working. In August, only 142,101,000 Americans were working. So the number of Americans working fell by 119,000 and yet the government would have us believe that the unemployment rate actually declined from 8.3 percent to 8.1 percent.
-According to the federal government, 96,000 jobs were added to the economy in August and the U.S. labor force shrank by 368,000 even though our population is continually growing. If the size of the U.S. labor force had stayed the same, the official unemployment rate would have actually gone up to 8.4 percent.
-Almost all of the new jobs added in August were the result of the "birth-death" model used by the Labor Department to estimate jobs added by new businesses. That model has been heavily criticized for being inaccurate. If you take the 87,000 jobs added by that model out of the equation, then the U.S. economy only added 9,000 jobs in August. But it takes somewhere around 125,000 new jobs each month just to keep up with the growth of the population.
-If the labor participation rate was sitting where it was when Barack Obama first took office, the unemployment rate in the United States would actually be 11.2 percent.
-If the labor participation rate was sitting at the 30 year average of 65.8 percent, the unemployment rate in the United States would actually be 11.7 percent.
-John Williams of Shadow Government Statistics would put the "real" rate of unemployment up around 23 percent after adding in all workers that have given up looking for work and all underemployed workers.
-The labor participation rate for men has fallen to 69.9 percent. This is the lowest level that it has been since the U.S. government began tracking this statistic back in 1948.
-There was more bad news for manufacturing in this latest report. During the month of August the U.S. manufacturing sector lost approximately 15,000 jobs.
-The official unemployment rate has now been above 8 percent for 43 months in a row.
-The percentage of working age Americans with a job has been below 59 percent for 36 months in a row.
-The employment numbers for both June and July were revised downward significantly. For June, it turns out that only 45,000 jobs were added to the economy as opposed to the 64,000 that were originally reported. For July, it turns out that only 141,000 jobs were added to the economy as opposed to the 163,000 that were originally reported.
-Incredibly, 58 percent of the jobs created since the end of the last recession have been low income jobs.
-The U.S. economy currently has 4.7 million less jobs than it did when the last recession started.
So what is the solution to these problems?
The media is breathlessly proclaiming that more quantitative easing is on the way and that the Federal Reserve will save the economy and send the stock market soaring to new heights.
A headline on CNBC on Friday boldly declared the following: "Market Sees 'Helicopter Ben' Coming to the Rescue".
You can almost hear the chopper blades whirling now.
Apparently Bernanke has had a love of showering the economy with money for a very long time. For example, you can see a picture of a young Ben Bernanke in action right here.
Of course that is a joke, but you get the point.
In recent years Federal Reserve Chairman Ben Bernanke and the rest of his cohorts have printed money like there is no tomorrow.
So have the previous rounds of quantitative easing solved our problems?
Of course not.
The employment rate is even lower today than it was two years ago.
But all of that money printing has sent the stock market soaring and it has enabled the big Wall Street banks to make an obscene amount of money.
The truth is that the Federal Reserve, the Obama administration and the big Wall Street banks don't really care about you.
They don't really care that the middle class is rapidly shrinking and that the number of Americans on food stamps has risen by more than 14 million since Barack Obama became president.
What they care about is what is good for them.
As I have written about previously, if we continue on the same path that we have been on for the past several decades, there will never be enough jobs in America ever again.
On our current trajectory, we will end up just like Greece where the unemployment rate is now up to 24.4 percent.
Once upon a time the economy of Greece was thriving.
But today, many formerly middle class Greek citizens are leaving Greece and are picking up whatever work they can find....
As a pharmaceutical salesman in Greece for 17 years, Tilemachos Karachalios wore a suit, drove a company car and had an expense account. He now mops schools in Sweden, forced from his home by Greece’s economic crisis.
“It was a very good job,” said Karachalios, 40, of his former life. “Now I clean Swedish s---.”
Karachalios, who left behind his 6-year-old daughter to be raised by his parents, is one of thousands fleeing Greece’s record 24 percent unemployment and austerity measures that threaten to undermine growth.
Would you be willing to do that?
Don't laugh.
Someday when the unemployment rate in the United States gets that high we will see large numbers of desperate Americans leaving this country in search of work somewhere else.
Already, an increasing number of Americans are buying expired food at auctions.
Times are hard and people are trying to get by any way that they can.
More than 100 million Americans are already on welfare and things have not even gotten that bad yet.
This is nothing compared to what is coming.
As you can see from the chart posted near the top of this article, the last economic downturn appears to have permanently weakened the U.S. economy.
Now the next wave of the economic collapse is rapidly approaching.
How much worse will things get when it finally hits us?
That is something to think about.
September 7, 2012
Citigroup, Goldman, UBS Sued Over Mortgage-Backed Bonds
Citigroup Inc. (C), Goldman Sachs Group Inc. (GS) and UBS AG (UBSN) were sued separately in New York over losses on $368.7 million in mortgage-backed securities.
The three banks made “material misrepresentations” about the loans backing the securities and about the transfer of the loans into trusts, according to filings today in New York State Supreme Court.
IKB Deutsche Industriebank AG (IKB) sued Citigroup over losses on $137.4 million in mortgage securities and also sued Goldman Sachs over $73.2 million in securities. IKB, a German lender, said it sold the securities at a loss.
UBS, based in Zurich, was sued by Sealink Funding Ltd. over $158.1 million in bonds. The securities at issue in the UBS case are either held by Sealink or were previously sold at a loss, according to court papers.
Claims against Citigroup, Goldman Sachs and UBS include fraud and negligent misrepresentation, according to the filings.
Danielle Romero-Apsilos, a spokeswoman for New York-based Citigroup; Michael DuVally, a spokesman for New York-based Goldman Sachs; and UBS spokeswoman Karina Byrne declined to comment on the filings.
The cases are IKB International SA in Liquidation v. Citigroup Inc., 653100-2012; IKB International SA in Liquidation v. Goldman Sachs Group Inc., 653101-2012; and Sealink Funding Ltd. v. UBS AG, 653102-2012, New York State Supreme Court (Manhattan).
September 6, 2012
$83,046 For A 3 Hour Hospital Visit - Why Are Hospital Bills So Outrageous?
The fastest way to go broke in America is to go to the hospital. These days it seems like almost everyone has an outrageous hospital bill story to share. It is getting to the point where most people are deathly afraid to go to the hospital. All the financial progress that you have made in recent years can literally be wiped out in just a matter of hours. For example, you are about to read about an Arizona woman that was recently charged $83,046 for a 3 hour hospital visit. How in the world is anyone supposed to pay a bill like that? I have a really hard time understanding why a visit to the doctor should ever be more than a couple hundred bucks or why a hospital stay should ever be more than a couple thousand dollars. Outrageous hospital bills are a real pet peeve of mine and I have not even been to the hospital in ages. What makes all of this even more infuriating is that Medicare, Medicaid and the big insurance companies are often charged less than 10 percent of what the rest of us are billed for the same procedures. There is a reason why 41 percent of all working age Americans are struggling with medical debt right now. It is because our health care system has become a giant money making scam. Millions of desperate Americans go into hospitals each year assuming that they will be treated fairly, but in the end they get stuck with incredibly outrageous bills and in many cases cruel debt collection techniques are employed against them if they don't pay.
So why do we have to pay so much for medical care? Back in 1980, less than 10 percent of U.S. GDP went to health care. Today, about 18 percent of U.S. GDP goes toward health care.
And considering the fact that over the next 20 years the number of Americans 65 years of age or older is projected to double that number is going to go even higher.
On a per capita basis we spend about twice as much on health care as anyone else in the world.
In fact, if the U.S. health care system was a nation it would be the 6th largest economy on the entire planet.
America spent 2.47 trillion dollars on health care in 2009, and it is now being projected that we will spend 4.5 trillion dollars on health care in 2019.
Our system is completely and totally broken, and Obamacare is going to make things far worse. We need to throw the entire system out and start over.
A perfect example of why this is true is what happened when 52-year-old Marcie Edmonds went in to a hospital in Arizona recently to get treated for a scorpion sting....
With the help of a friend, she called Poison Control and was advised to go to the nearest hospital that had scorpion antivenom, Chandler Regional Medical Center. At the hospital, an emergency room doctor told her about the antivenom, called Anascorp, that could quickly relieve her symptoms. Edmonds said the physician never talked with her about the cost of the drug or treatment alternatives.
Her symptoms subsided after she received two doses of the drug Anascorp through an IV, and she was discharged from the hospital in about three hours.
Weeks later, she received a bill for $83,046 from Chandler Regional Medical Center. The hospital, owned by Dignity Health, charged her $39,652 per dose of Anascorp.
What makes this even more shocking is that hospitals in Mexico only charge $100 per dose of Anascorp.
These days many hospitals will do whatever they can get away with on hospital bills.
One NBC News reporter was absolutely stunned at the bill that she received after she went in for neck surgery for degenerative disc disease recently....
Once I got my itemized bill, the grand total was a little over $66,013.40! That was for a one night stay and a four level vertebrae fusion surgery. The charges included $22 for one sleeping pill, $427 for one dissecting tool, and $32,000 for four titanium plates and ten screws.
I brought it to Todd Hill, a fee based patient advocate who helps people decipher their medical bills. "The screws in your procedure were billed at $605 a piece for a total of $6050 dollars. We've seen those in our past research for $25 or $30," he said. "In this case, the markup is tremendous," he added.
Considering the fact that 77 percent of American families are living paycheck to paycheck at least part of the time, a single hospital bill like this can be a financial death blow.
If you have time, read this tragic story where one man was charged $11,000 and all he had was a case of bad indigestion. Nothing was even wrong with him and now his family is going to have to declare bankruptcy.
Often medical bills are so complex and so confusing that nobody can really understand them. A lot of the times this is probably done on purpose to keep people from understanding how badly they are being overcharged. The following is from a recent article in the New York Times....
Hospital care tends to be the most confounding, and experts say the charges you see on your bill are usually completely unrelated to the cost of providing the services (at hospitals, these list prices are called the “charge master file”). “The charges have no rhyme or reason at all,” Gerard Anderson, director of the Center for Hospital Finance and Management at Johns Hopkins Bloomberg School of Public Health. “Why is 30 minutes in the operating room $2,000 and not $1,500? There is absolutely no basis for setting that charge. It is not based upon the cost, and it’s not based upon the market forces, other than the whim of the C.F.O. of the hospital.”
And those charges don’t really have any connection to what a hospital or medical provider will accept for payment, either. “If you line up five patients in their beds and they all have gall bladders removed and they get the same exact medication and services, if they have insurance or if they don’t have insurance, the hospital will get five different reimbursements, and none of it is based on cost,” said Holly Wallack, a medical billing advocate in Miami Beach. “The insurers negotiate a different rate, and if you are uninsured, underinsured or out of network, you are asked to pay full fare.”
It has been estimated that hospitals in the United States overcharge their patients by about 10 billion dollars every single year.
Medical bills are the number one reason why Americans file for bankruptcy. As I mentioned earlier, approximately 41 percent of all working age Americans are struggling with medical debt.
And health insurance is not as much protection as you might think. According to a report published in the American Journal of Medicine, of all bankruptcies caused by medical debt, approximately 75 percent of the time the people actually did have health insurance.
And if you can't pay your bills, many hospitals will come after you ruthlessly.
In fact, collection agencies sought to collect unpaid medical bills from approximately 30 million Americans during 2010 alone.
If you don't cough up the cash they are demanding you can even end up in prison. The following example comes from CBS News....
How did breast cancer survivor Lisa Lindsay end up behind bars? She didn't pay a medical bill -- one the Herrin, Ill., teaching assistant was told she didn't owe. "She got a $280 medical bill in error and was told she didn't have to pay it," The Associated Press reports. "But the bill was turned over to a collection agency, and eventually state troopers showed up at her home and took her to jail in handcuffs."
Although the U.S. abolished debtors' prisons in the 1830s, more than a third of U.S. states allow the police to haul people in who don't pay all manner of debts, from bills for health care services to credit card and auto loans.
But why do these bills have to be so high? It is not like many doctors are getting rich these days. In fact, many of them are going broke.
So what is the deal?
Well, as a recent article by Dr. Paul Craig Roberts explained, there are a whole lot of people pulling profit out of the system other than just doctors these days....
There are two main reasons that US medicine is so expensive. One is that profits are piled upon profits. In addition to wages and salaries for doctors, nurses, and medical personnel, the American health care system has to provide profits for private hospitals, diagnostic centers, insurance companies, and for the accountants, attorneys and management consultants made necessary by the enormous litigation and regulatory compliance cost. American medicine is the most regulated in the world and the most criminalized.
And another big factor is that the rest of us have to make up the difference for the patients that are not profitable.
It has gotten to the point where some doctors in certain kinds of practices barely make any profit on Medicare and Medicaid patients. In fact, in many cases doctors actually lose money treating them.
An article posted on medicalcostadvocate.com has some outrageous examples of the difference between what you and I are billed and what Medicare pays out for the exact same procedures....
A patient in Illinois was charged $12,712 for cataract surgery. Medicare pays $675 for the same procedure. In California, a patient was charged $20,120 for a knee operation for which Medicare pays $584. And a New Jersey patient was charged $72,000 for a spinal fusion procedure that Medicare covers for $1,629.
So not only do we pay very high taxes to support Medicaid and Medicare, we also have to pay higher medical bills in order to make up the difference for the money that doctors and hospitals are not seeing from those patients.
Unfortunately, Medicaid and Medicare are expected to grow dramatically in the years ahead.
For example, it is now being projected that Obamacare will add 16 million more Americans to Medicaid.
And enrollment in Medicare is projected to grow from 50.7 million today to 73.2 million in 2025.
How in the world can our current system possibly handle this?
And please don't tell me that Obamacare is the answer.
The truth is that Obamacare is going to take everything that is wrong with our health care system and make it even worse.
For a good summary on this, please see this article.
In the years ahead it is going to get even harder for those that are not dependent on the government for health care....
-Approximately 10 percent of all employers plan to drop health insurance coverage entirely because of Obamacare.
-According to one recent poll, 83 percent of all doctors in the United States have considered quitting the profession because of Obamacare, and we were already projected to have a severe doctor shortage in the years ahead even before Obamacare came along.
We are heading into the greatest health care crisis the United States has ever seen, and none of our leaders seem to have any answers.
In a recent article entitled "11 Signs That The U.S. Health Care System Is Heading Straight Down The Toilet", I detailed a lot more reasons why our health care system is a national disgrace. If you can handle some more ranting I encourage you to go check that article out.
I am just absolutely disgusted with the condition of our health care system. It is dominated by government bureaucrats, pharmaceutical corporations and the big health insurance companies. It is a giant money making scam that seeks to drain as much money from the rest of us as possible.
So do you have a hospital bill horror story to share? Please feel free to share your thoughts below....
September 5, 2012
Is The Fed Responsible For The Great Financial Crisis?
"Recessions are a natural economic feature and their regular occurrence is healthy and indeed essential," is how Deutsche's Jim Reid introduces his investigation into post-Fed un-natural business cycles. Without them there is a serious danger of bubbles and the misallocation of resources as the further market participants detach themselves from the last downturn the more they tend to under-estimate risk. We,
Jim Reid, Deutsche Bank: The history of business cycles in the US
The chart below shows the duration of each economic expansion (i.e. between all US recessions) since the NBER started collating statistics from 1854. This highlights the fact that prior to the GFC the three preceding expansions were in the top five on record. We can also show that this cycle is now almost exactly average length through history.

If we re-order these cycles by duration we can show more clearly how this current US expansion compares to those through history.

We passed the median cycle length at the start of 2012 and we will be past the historical average point by the end of this month (September 2012). This expansion is now the 12th longest out of 34 since 1854.
There are those that suggest that the Fed's inception back in 1913 has allowed for longer business cycles and for those interested we have colour coded those cycles (above) that occurred after this point, and also those post WWII when overall economy debt seemed to start a YoY increase that continues to this day. Countering the argument for longer post-1913 cycles would be the view that without the Fed helping to elongate several recent cycles, the GFC we've just been through might not have been anywhere near this deep and we are therefore now left in a unique situation at what is at the likely end of a multi-decade leverage binge consisting of several artificially long cycles. We are also now arguably in a liquidity trap where the Fed are less potent that they have been before in their near 100 year history.
The three 'super-cycles' between 1982 and 2007 were the exception rather than the norm, one where Central Banks and Governments had almost total flexibility over policy. The conditions that allowed for these long cycles perhaps started a decade earlier with the already much talked about collapse of the Gold Standard.
Unfortunately the 25-30 year build up of excess that this facilitated led to the GFC being the worst crisis since the 1930s and we have now likely moved to an era where policymakers no longer have the flexibility that defined the previous 25-30 years. Most Developed World (DW) Governments are up against their fiscal limits and are actually being forced into economically damaging austerity. We also have interest rates across the Western World that remain close to zero with little room to be lowered further. While we do have money printing, we are close enough to a liquidity trap that flooding the market with printed money doesn't have the same immediate impact on the economy as a cut in interest rates did in the long leveraging stage of the super-cycle.
So not only are we battling with the huge structural problems that the post-credit crisis world brings, we are fighting it without much policy flexibility and are indeed being forced into a reversal of stimulus at arguably exactly the wrong time.
So it all adds up to a return to more normal length business cycles in our opinion. Indeed one could make an argument for shorter cycles than normal given the lack of policy flexibility relative to most of history.
We, like Jim, would argue that the reason the Great Financial Crisis was so deep was due to the authorities continued refusal to let the business cycle take its natural course.
Jim Reid, Deutsche Bank: The history of business cycles in the US
The chart below shows the duration of each economic expansion (i.e. between all US recessions) since the NBER started collating statistics from 1854. This highlights the fact that prior to the GFC the three preceding expansions were in the top five on record. We can also show that this cycle is now almost exactly average length through history.
If we re-order these cycles by duration we can show more clearly how this current US expansion compares to those through history.
We passed the median cycle length at the start of 2012 and we will be past the historical average point by the end of this month (September 2012). This expansion is now the 12th longest out of 34 since 1854.
There are those that suggest that the Fed's inception back in 1913 has allowed for longer business cycles and for those interested we have colour coded those cycles (above) that occurred after this point, and also those post WWII when overall economy debt seemed to start a YoY increase that continues to this day. Countering the argument for longer post-1913 cycles would be the view that without the Fed helping to elongate several recent cycles, the GFC we've just been through might not have been anywhere near this deep and we are therefore now left in a unique situation at what is at the likely end of a multi-decade leverage binge consisting of several artificially long cycles. We are also now arguably in a liquidity trap where the Fed are less potent that they have been before in their near 100 year history.
The three 'super-cycles' between 1982 and 2007 were the exception rather than the norm, one where Central Banks and Governments had almost total flexibility over policy. The conditions that allowed for these long cycles perhaps started a decade earlier with the already much talked about collapse of the Gold Standard.
Unfortunately the 25-30 year build up of excess that this facilitated led to the GFC being the worst crisis since the 1930s and we have now likely moved to an era where policymakers no longer have the flexibility that defined the previous 25-30 years. Most Developed World (DW) Governments are up against their fiscal limits and are actually being forced into economically damaging austerity. We also have interest rates across the Western World that remain close to zero with little room to be lowered further. While we do have money printing, we are close enough to a liquidity trap that flooding the market with printed money doesn't have the same immediate impact on the economy as a cut in interest rates did in the long leveraging stage of the super-cycle.
So not only are we battling with the huge structural problems that the post-credit crisis world brings, we are fighting it without much policy flexibility and are indeed being forced into a reversal of stimulus at arguably exactly the wrong time.
So it all adds up to a return to more normal length business cycles in our opinion. Indeed one could make an argument for shorter cycles than normal given the lack of policy flexibility relative to most of history.
We, like Jim, would argue that the reason the Great Financial Crisis was so deep was due to the authorities continued refusal to let the business cycle take its natural course.
September 4, 2012
Audit of the Federal Reserve Reveals $16 Trillion in Secret Bailouts
The first ever GAO (Government Accountability Office) audit of the Federal Reserve was carried out in the past few months due to the Ron Paul, Alan Grayson Amendment to the Dodd-Frank bill, which passed last year.
Jim DeMint, a Republican Senator, and Bernie Sanders, an independent Senator, led the charge for a Federal Reserve audit in the Senate, but watered down the original language of the house bill(HR1207), so that a complete audit would not be carried out.
Ben Bernanke (pictured to the right), Alan Greenspan, and various other bankers vehemently opposed the audit and lied to Congress about the effects an audit would have on markets.
SHADE the Motion Picture – Global Depopulation Agenda Exposed!(Ad)
Nevertheless, the results of the first audit in the Federal Reserve’s nearly 100 year history were posted on Senator Sander’s webpage earlier this morning.
What was revealed in the audit was startling:
$16,000,000,000,000.00 had been secretly given out to US banks and corporations and foreign banks everywhere from France to Scotland.
From the period between December 2007 and June 2010, the Federal Reserve had secretly bailed out many of the world’s banks, corporations, and governments. The Federal Reserve likes to refer to these secret bailouts as an all-inclusive loan program, but virtually none of the money has been returned and it was loaned out at 0% interest.
Why the Federal Reserve had never been public about this or even informed the United States Congress about the $16 trillion dollar bailout is obvious – the American public would have been outraged to find out that the Federal Reserve bailed out foreign banks while Americans were struggling to find jobs.
To place $16 trillion into perspective, remember that GDP of the United States is only $14.12 trillion. The entire national debt of the United States government spanning its 200+ year history is “only” $14.5 trillion.
The budget that is being debated so heavily in Congress and the Senate is “only” $3.5 trillion. Take all of the outrage and debate over the $1.5 trillion deficit into consideration, and swallow this Red pill: There was no debate about whether $16,000,000,000,000 would be given to failing banks and failing corporations around the world.
In late 2008, the TARP Bailout bill was passed and loans of $800 billion were given to failing banks and companies. That was a blatant lie considering the fact that Goldman Sachs alone received 814 billion dollars.
As is turns out, the Federal Reserve donated $2.5 trillion to Citigroup, while Morgan Stanley received $2.04 trillion. The Royal Bank of Scotland and Deutsche Bank, a German bank, split about a trillion and numerous other banks received hefty chunks of the $16 trillion.
“This is a clear case of socialism for the rich and rugged, you’re-on-your-own individualism for everyone else.“- Bernie Sanders (I-VT)
When you have conservative Republican stalwarts like Jim DeMint(R-SC) and Ron Paul(R-TX) as well as self identified Democratic socialists like Bernie Sanders all fighting against the Federal Reserve, you know that it is no longer an issue of Right versus Left.
When you have every single member of the Republican Party in Congress and progressive Congressmen like Dennis Kucinich sponsoring a bill to audit the Federal Reserve, you realize that the Federal Reserve is an entity onto itself, which has no oversight and no accountability.
Americans should be swelled with anger and outrage at the abysmal state of affairs when an unelected group of bankers can create money out of thin air and give it out to megabanks and supercorporations like Halloween candy.
If the Federal Reserve and the bankers who control it believe that they can continue to devalue the savings of Americans and continue to destroy the US economy, they will have to face the realization that their trillion dollar printing presses will eventually plunder the world economy.
The list of institutions that received the most money from the Federal Reserve can be found on page 131of the GAO Audit and are as follows..
Citigroup: $2.5 trillion ($2,500,000,000,000)
Morgan Stanley: $2.04 trillion ($2,040,000,000,000)
Merrill Lynch: $1.949 trillion ($1,949,000,000,000)
Bank of America: $1.344 trillion ($1,344,000,000,000)
Barclays PLC (United Kingdom): $868 billion ($868,000,000,000)
Bear Sterns: $853 billion ($853,000,000,000)
Goldman Sachs: $814 billion ($814,000,000,000)
Royal Bank of Scotland (UK): $541 billion ($541,000,000,000)
JP Morgan Chase: $391 billion ($391,000,000,000)
Deutsche Bank (Germany): $354 billion ($354,000,000,000)
UBS (Switzerland): $287 billion ($287,000,000,000)
Credit Suisse (Switzerland): $262 billion ($262,000,000,000)
Lehman Brothers: $183 billion ($183,000,000,000)
Bank of Scotland (United Kingdom): $181 billion ($181,000,000,000)
BNP Paribas (France): $175 billion ($175,000,000,000)
and many many more including banks in Belgium of all places
View the 266-page GAO audit of the Federal Reserve (July 21st, 2011):
September 3, 2012
China Manufacturing PMI At Lowest Since March 2009; Market Response 'Bad Is Good' So Far
AUDJPY is getting smacked hard in this evening's admittedly thin trading given the US holiday. China's double-whammies of PMI data (both official and HSBC versions - with the latter revised lower from Flash to its lowest level since March 2009) and some weak Aussie retail sales data is weighing very heavily on the critical carry trade pair. S&P 500 futures traded down in line with AUDJPY from Friday's close but once the China PMI came as weak as it was so the 'Good is Bad', the PBoC have to do something crowd started buying and dragged ES up a few points. Juxtaposing these dismal macro data was a better than expected China Services PMI and Aussie manufacturing index - as the Schrodinger 'economy is good and bad' headlines continue to confound. For the 'bad-is-good' crowd who see stimulus as the solution, we offer two words 'Steel over-capacity'.
The last time HSBC and Official Manufacturing PMIs were sub-50 was in Nov 11 - right before the last coordinated central bank intervention (but energy and food prices were dramatically different then). This is the lowest HSBC PMI since March 2009...

S&P 500 futures fell in line with AUDJPY's weakness but have diverged since China PMI printed so weak - now the market reprices on further central-planning help implied by the dismal data...

sigh...
With markets thin and no Treasury market 'police' to control the tom-foolery this evening, we can onlyt imagine where this ends but for now AUDJPY is our guide.
Perhaps this must-read story from Reuters will color those stimulus-hunters' opinion a little!!
China's banks are coming after the country's steel traders, hauling executives into court to chase down loans that some traders said they didn't initially need and can't now repay.
The heavy push to recover the loans is another sign of strain on China's financial system at a time when the country's leaders are contemplating another round of stimulus to boost the economy, and when banks are worried about bad debts piling up.
The battle between the banks and steel traders also exposes flaws in the 4 trillion ($629 billion) stimulus round in 2008, and offers a warning to those calling for pumping more money into the system. At that time, Chinese banks threw money at the steel trade - a crucial cog in supplying the country's massive construction and infrastructure growth.
But those steel loans, after offering a quick fix, became excessive, poorly managed, or a combination of the two. Government officials insisted more money was needed to prop up the industry. Steel executives said the money flow was too heavy, and they had to put the money to work in real estate and the stock market.
"After the financial crisis, when the government released its stimulus, banks begged us to borrow money we didn't need," Li Huanhan, the owner of Shanghai Shunze Steel Trading, told a judge at a recent hearing. "We had nothing to do with the money, so we turned to other investments, like real estate."
The last time HSBC and Official Manufacturing PMIs were sub-50 was in Nov 11 - right before the last coordinated central bank intervention (but energy and food prices were dramatically different then). This is the lowest HSBC PMI since March 2009...
S&P 500 futures fell in line with AUDJPY's weakness but have diverged since China PMI printed so weak - now the market reprices on further central-planning help implied by the dismal data...
sigh...
With markets thin and no Treasury market 'police' to control the tom-foolery this evening, we can onlyt imagine where this ends but for now AUDJPY is our guide.
Perhaps this must-read story from Reuters will color those stimulus-hunters' opinion a little!!
China's banks are coming after the country's steel traders, hauling executives into court to chase down loans that some traders said they didn't initially need and can't now repay.
The heavy push to recover the loans is another sign of strain on China's financial system at a time when the country's leaders are contemplating another round of stimulus to boost the economy, and when banks are worried about bad debts piling up.
The battle between the banks and steel traders also exposes flaws in the 4 trillion ($629 billion) stimulus round in 2008, and offers a warning to those calling for pumping more money into the system. At that time, Chinese banks threw money at the steel trade - a crucial cog in supplying the country's massive construction and infrastructure growth.
But those steel loans, after offering a quick fix, became excessive, poorly managed, or a combination of the two. Government officials insisted more money was needed to prop up the industry. Steel executives said the money flow was too heavy, and they had to put the money to work in real estate and the stock market.
"After the financial crisis, when the government released its stimulus, banks begged us to borrow money we didn't need," Li Huanhan, the owner of Shanghai Shunze Steel Trading, told a judge at a recent hearing. "We had nothing to do with the money, so we turned to other investments, like real estate."
Subscribe to:
Posts (Atom)