November 18, 2014

Private Equity Now Looking to Even Bigger Chumps, Namely 401 (k)s and Retail

One of the reasons that private equity has managed to flourish is that its biggest investor group is what is traditionally referred to as dumb money: public pension funds, which account for 25% of industry assets. Readers may recall that even CalPERS, widely considered to be the savviest public pension fund, recently had a public board meeting where the questions asked of prospective gatekeepers, the pension fund consultants, were, with one exception, softballs. And that question was the only one to address the SEC’s revelation that private equity firms have been engaging in large scale fee-skimming and other forms of grifting. And remember, the SEC also stated that the investors in these funds, known in industry nomenclature as limited partners, have done a crappy job of negotiating their agreements.

But in predictable fashion, as one group of marks, um, sales targets, starts to dry up, private equity funds, aka general partners, are hunting for new ones. And having gone very systematically after every conceivable large pot of money, the only place left for them to go is down market, in terms of size and sophistication. As private equity industry expert Eileen Appelbaum explains in The Hill, both public and private pension funds, another big money source for private equity, are shrinking as pensions generally are under attack. So the prize for private equity is to get its hands on retail investors, namely, even lower tier wealthy and 401 (k) plans.

Before we get into how this is happening, we need to step back and underscore why this is a terrible idea. Private equity returns, even for institutional investors, are exaggerated. These reported returns do not beat stocks on a risk-adjusted basis. And that’s even when you use a measure that flatters private equity, with is internal rates of return. As we’ve discussed, IRR is known by anyone with a even a smidgen of finance training to be a terrible measure. One of the big reasons why is it overstates performance relative to better metrics, such as the widely used gold standard of discounted cash flows, or one that some academics view fondly, called public market equivalent.

So understand this: private equity’s entire raison d’etre is its allegedly superior returns. If that is bunk, the rationale for investing in private equity collapses. The other justification for investing in it, that its profile of returns doesn’t covary much with other investments, is highly sus, given that private equity is essentially levered equity. Many experts believe that the supposed differentiated pattern of returns depends heavily on private equity “smoothing” as in not marking their portfolios to market at times when markets are terrible.

In fairness, there have been historical periods when buyouts, the main type of private equity deals (accounting for 85% of industry assets) produced sparkling returns for investors, such as in the 1980s, when there were lots of overdiversified large companies selling at conglomerate discounts. Making money in leveraged buyouts then was like shooting fish in a barrel, provided you could hire an investment bank to run a hostile takeover. Simply buying the company with a ton of debt (and achievable leverage levels were also higher back then, amping up returns), breaking it up and selling off the parts was an easy winner. Selling off other assets, like headquarters properties, the corporate art collection, and surplus jets, helped too, as did thinning out an often-bloated corporate center.

But looking dispassionately at the data shows that PE’s claims to better returns don’t hold up. And that’s before you get to factoring in issues that astonishingly, academics have managed to ignore despite them being blindingly obvious omissions. For instance, when an investor signs up for a private equity fund, he is contractually obligated the minute the ink is dry. Yet the general partner won’t begin making capital calls for months, sometimes starting as much as a year later. Those capital calls continue typically until year three or four after the commitment date.

The convention in the industry is to calculate returns ONLY when the money has left the investor’s pocket and gone over to the PE fund. Yet if you read limited partnership agreements, capital calls have very short notices. Five to ten days is the norm. The consequences of missing a capital call are draconian. Generally speaking, you lose the money you’ve put in. And even if you simply miss your first capital call (as in you lose no actual dollars), that general partner will never invite you into a fund again. If you are a typical limited partner that thinks getting into funds, particularly the illusory “better” funds, is important, that alone is a terrible sanction.

So that means the investors need to make sure they have enough dough on hand to meet capital calls. That means they need to be in liquid, hence generally lower-return investments. The cost of being in lower-term investments early in the life of private equity investments to accommodate general partner capital calls, which is inherent to investing in private equity, is not factored into return calculations. Low returns in the early years of any investment severely dampen total returns.

We anticipate being able to perform some analyses of this issue. In the meantime, a paper by Oxford professor Ludovic Phalippou is coming out shortly that looks at this issue on a theoretical level (as in not working from a specific data set). He told us that his conclusion is that the cost of being in lower-return investments is roughly 300 basis points a year.* Note that 300 basis points is conventional wisdom as to how much PE outperforms public stocks using its current dubious metrics (and that is before risk adjusting it for its illiquidity, which is also conventionally depicted as 300 to 400 basis points**).

So the reason to allow smaller investors to get into private equity at all looks spurious on its face, particularly since private equity returns have been declining in recent years. And remember, the return picture will look even worse for small investors than for the big boys because they will pay more in fees, more in expenses (pretty much inherent to smaller investments) and are also just about certain to be steered to at least some less than stellar funds. A New York Times article last month flagged some of these issues (emphasis ours):
Carlyle’s new vehicle, called Carlyle Private Equity Access 2014, whose existence has not previously been disclosed, is just one of several efforts by the industry to attract checks in the tens of thousands of dollars rather than in the hundreds of millions. In addition to annual fees paid to their wealth manager, investors pay Carlyle 1 to 2 percent of their capital plus 20 percent of any profits, in line with the industry standard…. 
Morgan Stanley, for example, was recently gathering capital from wealthy clients for a new Blackstone energy fund that is expected to exceed its $4 billion target when it finishes raising capital this year. It took the bank a single day to raise its entire $500 million feeder fund, which was about four times oversubscribed, people briefed on the matter said…. 
Traditional feeder funds can also allow investors to commit as little as $250,000, but the new Carlyle product is intended to provide a more diversified investment, including private equity funds focused on Japan, Asia and Europe, as well as an international energy fund… 
Other firms, acting as middlemen, are allowing the private equity giants to attract a lower stratum of wealth. One firm, the Central Park Group, gives investors indirect access to Carlyle funds. It caters to so-called accredited investors, who have at least $1 million in assets not including their primary home. Because it is an intermediary, the firm charges a fee as high as 1.8 percent and an additional 0.55 percent for expenses, on top of the 1.3 percent of assets charged by the Carlyle funds in which it invests, according to marketing materials and a person briefed on the matter. Still, it has raised more than $500 million since its debut last year, this person said.
We’ll discuss in a later post why these hot energy funds look to be a particularly successful version of private equity picking investors’ pockets.

If you look at how the Carlyle funds that CalPERS has invested in have performed (and remember that CalPERS in theory can do a better job of fund-picking and can negotiate lower fees), you will see that on the whole, the foreign funds have performed less well than the flagship domestic funds. So “more diversified investment” appears to be seller talk for “putting you in funds with lower odds of payoff because we have less of an information advantage.”

Appelbaum explains why this downmarket trend is particularly troubling:
While private equity hasn’t tapped workers 401(k)s yet, Carlyle and other PE firms are currently developing new financial products that will let individual investors write small checks to PE funds. 
This new focus on individual investors is facilitated by the Jumpstart Our Business Startups Act (JOBS Act) that went into effect in the fall of 2013…The rules that implement the JOBS Act do not incorporate basic investor protections…It is, however, still the case that individuals that participate in a PE fund must be “accredited investors.” 
To be an accredited investor, an individual must have a net worth — alone or with a spouse — greater than $1 million, not including the value of his or her home. 
Alternatively, the individual can be an accredited investor if they have an annual income of $200,000 or more (or $300,000 with a spouse). These income thresholds were set in 1982 when $200,000 meant you were a lot richer. If these wealth and income thresholds had been adjusted for inflation, an accredited investor would have to have a net worth of $2.5 million or an annual income of $493,000 (or $740,000 with a spouse). 
Granted, very few of us will ever qualify as an accredited investor. Still, about 8.5 million people meet the current criteria. And that includes many professionals, especially in two-earner households, who may head toward retirement with a million dollars in their 401(k)s. To put that in perspective, a million dollars in a retirement savings account comes to $40,000 to $50,000 a year in pre-tax income during retirement.
The kicker here is that the $1 million in net worth can include investment in retirement accounts. And as Appelbaum stresses, having a decent personal balance sheet or income does not mean someone is financially savvy.

What goes unstated is why the mythology of these superior returns goes unchallenged, when that legitimates the rush to syphon funds out of retail chumps. The fact is that private equity has effectively bought off, co-opted or cowed the very people who ought to be minding the store.

As we indicated with Harvard, which is also considered to be a sophisticated investor, its law firm, which is one of its most important resources in cutting deals with private equity firms, is more loyal to private equity kingpin Bain. This pattern is repeated across the industry, where private equity limited partners simply don’t pay remotely enough in fees compared to private equity firms to get the best legal talent on their side. This pattern is most obvious with attorneys, but it applies to all the other supposed gatekeepers who are afraid to rock the boat with PE firms because they’ll simply refuse to deal with them (remember, the gatekeepers, such as the supposedly independent consulting firms, need to get information from the private equity firms to do their job. And the consultants no doubt correctly fear that they would be frozen out of limited partner engagements if PE firms reported that they were difficult or implies that their information demands reflected a lack of sophistication, as opposed to well-warranted skepticism).

This situation is even worse as far as the mythology of superior returns is concerned. Key employees at private equity limited partners benefit directly from PE funds reporting exaggerated returns. Even at CalPERS, cetain members of the investment office get bonuses based on performance relative to benchmarks. At CalPERS and public pension funds, these bonuses are so small as to arguably not be terribly motivating, but at other opinion leaders, such as universities like Yale and Harvard, the performance bonuses are significant. And they are also much more meaningful at private pension funds and insurers, both large investors in private equity.

We’ve noted how the use of IRR exaggerates the return side of the performance equation. The benchmarking is often flawed too. For instance, Thompson Reuters is one of the most popular services for private equity benchmarking. It also happens to show the lowest returns. An industry insider tells us that Thompson Reuters is in the process of exiting this business, forcing limited partners who used Thompson to find new benchmarks. The replacement services, such as Cambridge Associates, use benchmarks that show returns that are sufficiently greater than the one Thompson showed as to call into question whether bonuses paid to investment staffers in prior years were deserved. One doubts that any fiduciary will have the nerve to try to claw back payments, or reduce going forward bonuses in light of what now looks like excessive prior payouts, but the differences are great enough in some cases as to be giving boards and trustee fits.

And to complete this sorry picture, last week, Private Equity Manager reported that the investors’ association, the ILPA, had stated in effect that limited partners were circling the wagons, and wanted only more transparency between themselves and the general partners. So to the extent any reforms take place (and don’t hold your breath), small fry players won’t benefit. That, as we often say here, is a feature, not a bug.

* Looking at illustrative or better yet actual capital calls will allow for much more granular analysis, as well as looking at the impact over the lives of various funds, which is the most important measure. Moreover, we are not sure a one-size-fits-all story on managing pre-capital call liquidity is the best way to look at this. Wealthy individuals and smaller investors like universities and foundations would need to keep most or all of their committed money in low-risk investments like cash equivalents or short-term, low-risk bonds to avoid missing a capital call. Note that in the dot-bomb era, when wealthy investor lost boatloads on their stock portfolios, defaults on private equity capital calls were widespread. Similarly, in the crisis, Duke famously missed private equity capital calls. Similarly, CalPERS was widely criticized for dumping stocks during the crisis. It is widely rumored that the reason was not panic but needing to meet private equity capital calls. However, a CalPERS nevertheless has much more money flowing in and out on a routine basis, and thus larger investors such as the bigger pension fund and endowments could be assumed to do somewhat better, in return terms, in managing their fund so as to accommodate private equity capital calls.

** We are not certain the 300 to 400 basis point illiquidity discount is the right way to look at this issue. Private equity investors face a high degree of uncertainty as to when they get their money back. They have effectively given the general partners that option. Long-dated options are extremely valuable. We suspect this option is worth more than 300 to 400 basis points.

November 17, 2014

Obamacare = A Death Panel For The U.S. Economy

Did you know that some Americans are being hit with health insurance rate increases of more than 500 percent?  Taking advantage of "the stupidity of the American voter", the Democrats succeeded in ramming through one of the worst pieces of legislation that has ever come before Congress.  The full implementation of Obamacare has been repeatedly delayed, but now we are finally starting to see the true horror of this terrible law.  Thanks to Obamacare, millions of American families are losing health plans that they were very happy with, health insurance rates are skyrocketing, millions of workers are having their full-time hours cut back to part-time hours, rural hospitals all over the country are dying, and thousands of doctors are being driven out of the industry thus intensifying the greatest doctor shortage in U.S. history.  Obamacare is a slow-motion train wreck of epic proportions, and the full effect of this law is only beginning to be felt.  In the end, the economic impact of this law will likely be measured in the trillions of dollars.

One of the primary reasons why Democrats experienced so much pain during the recent elections was because millions of Americans are receiving some very disturbing letters from their health insurance providers.  At a time when U.S. incomes are stagnating, health insurance rates are rising to absolutely ridiculous levels.

As the New York Times recently reported, even the Obama administration is admitting that "substantial price increases" are on the way...
The Obama administration on Friday unveiled data showing that many Americans with health insurance bought under the Affordable Care Act could face substantial price increases next year — in some cases as much as 20 percent — unless they switch plans.
The data became available just hours before the health insurance marketplace was to open to buyers seeking insurance for 2015. 
An analysis of the data by The New York Times suggests that although consumers will often be able to find new health plans with prices comparable to those they now pay, the situation varies greatly from state to state and even among counties in the same state.
Originally, Barack Obama promised that if we liked our current health plans that we could keep them.  Well, it turns out that was not true at all.  Instead, the vast majority of us will eventually have to move to new plans if we have not done so already.  This is particularly true for those that purchase health insurance individually.  The following is an excerpt from an NBC News investigation...
Four sources deeply involved in the Affordable Care Act tell NBC News that 50 to 75 percent of the 14 million consumers who buy their insurance individually can expect to receive a “cancellation” letter or the equivalent over the next year because their existing policies don’t meet the standards mandated by the new health care law. One expert predicts that number could reach as high as 80 percent. And all say that many of those forced to buy pricier new policies will experience “sticker shock.”
This is something that actually happened to me.  I received a letter in the mail informing me that my new health insurance policy which meets the requirements of Obamacare will cost me nearly twice as much as my old one.

Needless to say, I was not too thrilled about that.

Other Americans are being hit even harder.  For instance, one family down in Texas got hammered with a 539 percent rate increase...
Obamacare is named the "Affordable Care Act," after all, and the President promised the rates would be "as low as a phone bill." But I just received a confirmed letter from a friend in Texas showing a 539% rate increase on an existing policy that's been in good standing for years. 
As the letter reveals (see below), the cost for this couple's policy under Humana is increasing from $212.10 per month to $1,356.60 per month. This is for a couple in good health whose combined income is less than $70K -- a middle-class family, in other words.
These rate increases are coming at a time when the middle class in the U.S. is already steadily shrinking.  A lot of families that are already stretched to the breaking point are making the very painful decision to give up health insurance entirely.  At this point, there are millions of families that simply cannot afford it.

But Obama is not about to let those people off the hook.  In fact, huge tax penalties are on the way for those that do not participate in the new system...
Penalties for failing to secure a health-insurance plan will rise steeply next year, which could take a big bite out of some families’ pocketbooks. 
“The penalty is meant to incentivize people to get coverage,” said senior analyst Laura Adams of InsuranceQuotes.com. “This year, I think a lot of people are going to be in for a shock.” 
In 2014, Obamacare’s first year, individuals are facing a penalty of $95 per person, or 1 percent of their income, depending on which is higher. If an American failed to get coverage this year, that penalty will be taken out of their tax refund in early 2015, Adams noted. 
While that might be painful to some uninsured Americans who are counting on their tax refunds in early 2015, the penalty for going uninsured next year is even harsher. The financial penalty for skipping out on health coverage will more than triple to $325 per person in 2015, or 2 percent of income, depending on whichever is higher.
Children will be fined at half the adult rate, or $162.50 for those under 18 years old.
No wonder so many people are so angry with the Democrats.

And as Massachusetts Institute of Technology professor Jonathan Gruber has so infamously observed, Obamacare never would have become law if the American people had been told the truth about what it would do to them.

It has been documented that Gruber has visited the White House about a dozen times since 2009, and he has been one of the leading intellectual proponents of Obamacare.  A video in which he states that "the stupidity of the American voter" was "really critical" to the passage of Obamacare has gone viral over the past week.  I have posted a copy of this video below...


What he is essentially saying is that the Democrats purposely deceived the American people because it was the only way that Obamacare was going to become law.
And this is a man that has become very wealthy advising government on healthcare matters.  According to an article in the Washington Post, he has made millions of dollars from "consulting" in recent years...
Not all of the contracts could be found on public Web sites, but here is a sampling. In some cases, Gruber worked with other consultants, so the fees were shared. These figures also might not represent the final payout, and of course these are gross figures, before expenses. But it’s safe to say that about $400,000 appears to be the standard rate for gaining access to the Gruber Microsimulation Model. 
Michigan: $481,050 
Minnesota: $329,000 
Vermont: $400,000 
Wisconsin: $400,000 
Gruber has also earned more than $2 million over the last seven years for an ongoing contract with HHS to assess choices made by the elderly in Medicare’s prescription-drug plan.
If you are Gruber, life is quite good.

But for most of the rest of America, the economic pain continues.

For example, one recent study found that almost half of all Floridians cannot even afford "to pay for basic necessities"...
Nearly half of Florida households do not earn enough to pay for basic necessities, according to a report released Tuesday by the United Way that seeks to cast a light on the large group of state residents who struggle financially but do not meet the official criteria for being in poverty.
While 15 percent of Florida households are below the poverty level, another 30 percent are financially insecure — a figure that also applies to Sarasota and Manatee counties — based on a new measurement developed by the United Way.
If all those people cannot even afford the basics, how are they going to pay for Obamacare?
This law is going to financially cripple millions of American families.  It truly is a death panel for the U.S. economy.  And because Barack Obama can veto anything that the Republicans in Congress do, we are stuck with it for at least another two years (and probably longer).
So what about you?

Have your health insurance premiums gone up yet?

Please feel free to add to the discussion by posting a comment below...

November 14, 2014

Corporate Profit Margins vs. Wages in One Disturbing Chart

This brief post by Doug Short is even more important than it appears to be. We had an outburst of neoliberal orthodoxy in comments yesterday on a post that discussed how wealth of most households had fallen since 1987. Some readers assigned blame for stagnant average worker wages (which was a big contributor to the lack of growth in household wealth) to immigrants, particularly Mexicans and H1-B visa workers.

While immigration was no doubt an element, to give it the leading role is counterfactual. The argument made, explicitly, is “more workers leads to lower wages”. Ahem, there a a lot more variables than just the labor supply side. But even if you take a simple-minded point of view, women’s rising participation in the workforce, particularly given that women even now make 77% of what men make, would be a vastly bigger wage-rate depressor than Mexican workers. The number of working women rose by nearly 30 million between 1970 and 2010, vastly larger than any estimate of immigrant influx.

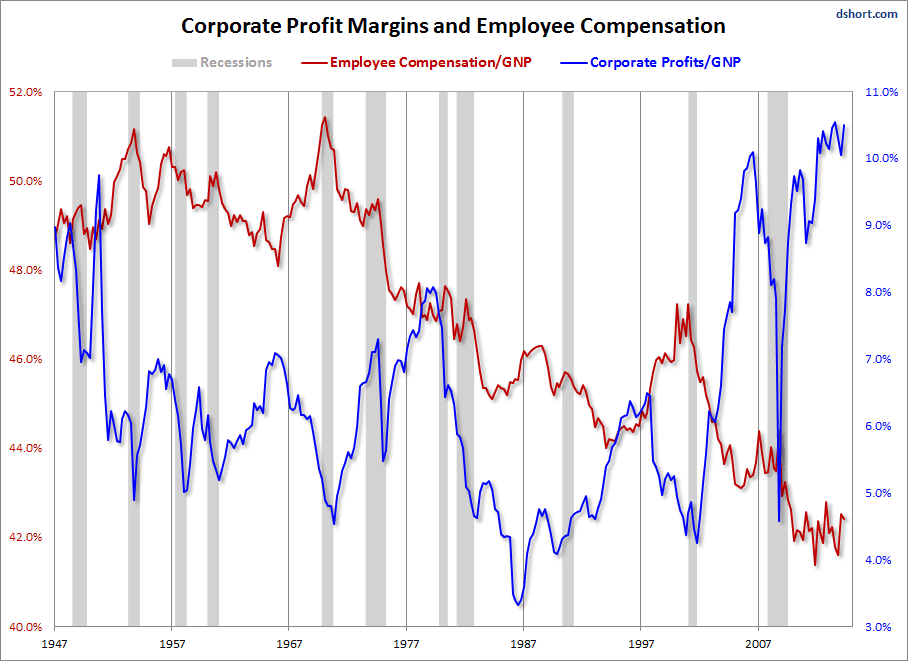
The Doug Short chart below looks at corporate profit share versus labor share. This pinpoints the degree to which wage stagnation is the result of corporate managers and executives succeeding in cutting the pie to favor themselves (executive pay has become increasingly linked to stock prices, and relentless focus on short-term earnings, as well as stock buybacks, do wonders for earnings per share).

Short omits some key elements from his discussion. One is that until recently, a profit share of GDP of 6% was perceived to be a cyclical peak; no less than Warren Buffet deemed a higher level to be unsustainable. And in fact, we see an explosion of profit share from 6% to 10% of GDP in the runup to the crisis, roughly from 2003 to 2007. The “rescue the banks and financial markets” measures succeeded in bringing the profit share back to its pre-crisis levels, at the expense of workers.

Notice the inflection point in profit share is 1987, when Greenspan became Fed chairman. Correlation may not be causation, but the timing is almost exact.

But what about the years prior to 1987? We see falling labor share and rising profit share from the 1973 recession through 1979, then labor share and profit share falling through 1987. What is that about?

Interestingly, the chart shows that corporations did well in profit terms in the mid-1970s stagflation at the expense of workers. But they were perceived (correctly) as having their lunches increasingly eaten by Japanese and German manufacturers. Inflation kept rising, which hurt investment in plant and equipment (high interest rates make any long-term commitment look lousy). High inflation killed stock market valuations, which allowed corporate leaders to press an agenda of deregulation with the Carter Administration, which was desperate for any ideas to increase flagging growth levels.

In 1979, Volcker started pushing interest rates sky high. Banks and other financial players were hemorrhaging losses. Volcker was explicit privately that he wanted to break the bargaining power of labor. In Secrets of the Temple, William Greider reported that Volcker kept a notecard which tracked average pay in the construction industry. He wanted to see that fall before he was willing to let interest rates ease. The economy went into a sharp, nasty contraction, hence the reason for both falling profits and falling labor share.

But why did corporate profits continue to fall after the 1979-1982 recession was over? I’d hazard a big contributor was the rapid rise of the US dollar, which not only killed US exports, but also enabled foreign manufacturers to gain even more ground. If you look at auto imports to the US, the Japanese made tremendous headway after the dollar spike of the early 1980s.

By Doug Short, Advisor Perspectives. Cross posted from Wolf Street

Yesterday’s collection of Advisor Perspectives articles particularly caught my attention: Why Jeremy Grantham is Right about Corporate Profit Margins by Baijnath Ramraika and Prashant Trivedi. The article includes a number of fascinating graphs, the first of which is a snapshot of US Corporate Margins since 1947 calculated by dividing Corporate Profits after Tax by Gross National Product.

The article inspired me to produce a chart of the Profit-to-GNP ratio, but with an added and rather sobering overlay: Employee Compensation (wages and salaries), which I’ve likewise divided by GNP. Here it is.


If indeed corporate profits are mean reverting, a view supported by the authors of the Advisor Perspectives article, we see that this metric can spend many years at wide variance from the trend. Employee Compensation, however, has had a distinctly downward trend since its peak in 1970. The only conspicuous exception to the trend was the bubble period of “Irrational Exuberance,” as then Fed Chairman Alan Greenspan famously called it, that began in the mid-1990s.

And when it comes to wages, there are “Lies, Damn Lies, and Statistics.” Read… How to Obscure one of the Biggest Economic Problems in the US

November 13, 2014

Obama’s Secret Treaty Would Be The Most Important Step Toward A One World Economic System

Barack Obama is secretly negotiating the largest international trade agreement in history, and the mainstream media in the United States is almost completely ignoring it.  If this treaty is adopted, it will be the most important step toward a one world economic system that we have ever seen.  The name of this treaty is "the Trans-Pacific Partnership", and the text of the treaty is so closely guarded that not even members of Congress know what is in it.  Right now, there are 12 countries that are part of the negotiations: the United States, Canada, Australia, Brunei, Chile, Japan, Malaysia, Mexico, New Zealand, Peru, Singapore and Vietnam.  These nations have a combined population of 792 million people and account for an astounding 40 percent of the global economy.  And it is hoped that the EU, China and India will eventually join as well.  This is potentially the most dangerous economic treaty of our lifetimes, and yet there is very little political debate about it in this country.
Even though Congress is not being allowed to see what is in the treaty, Barack Obama wants Congress to give him fast track negotiating authority.  What that means is that Congress would essentially trust Obama to negotiate a good treaty for us.  Congress could vote the treaty up or down, but would not be able to amend or filibuster it.

Of course now the Republicans control both houses of Congress.  If they are foolish enough to blindly give Barack Obama so much power, they should all immediately resign.

And it is critical that people understand that this is not just an economic treaty.  It is basically a gigantic end run around Congress.  Thanks to leaks, we have learned that so many of the things that Obama has deeply wanted for years are in this treaty.  If adopted, this treaty will fundamentally change our laws regarding Internet freedom, healthcare, copyright and patent protection, food safety, environmental standards, civil liberties and so much more.  This treaty includes many of the rules that alarmed Internet activists so much when SOPA was being debated, it would essentially ban all "Buy American" laws, it would give Wall Street banks much more freedom to trade risky derivatives and it would force even more domestic manufacturing offshore.

In other words, it is the treaty from hell.

In addition to imposing Obama's vision for the world on 40 percent of the global population, it is also being described as a "Christmas wish-list for major corporations".  Of the 29 chapters in the treaty, only five of them actually deal with economic issues.  The rest of the treaty deals with a whole host of other issues of great importance to the global elite.

The following list of issues addressed by this treaty is from a Malaysian news source...
• domestic court decisions and international legal standards (e.g., overriding domestic laws on both trade and nontrade matters, foreign investors’ right to sue governments in international tribunals that would overrule the national sovereignty)
• environmental regulations (e.g., nuclear energy, pollution, sustainability)
• financial deregulation (e.g., more power and privileges to the bankers and financiers)
• food safety (e.g., lowering food self-sufficiency, prohibition of mandatory labeling of genetically modified products, or bovine spongiform encephalopathy (BSE) or mad cow disease)
• Government procurement (e.g., no more buy locally produced/grown)
• Internet freedom (e.g., monitoring and policing user activity)
• labour (e.g., welfare regulation, workplace safety, relocating domestic jobs abroad)
• patent protection, copyrights (e.g., decrease access to affordable medicine)
• public access to essential services may be restricted due to investment rules (e.g., water, electricity, and gas)
Why can't we get this type of reporting in the United States?

And if this treaty is ultimately approved by Congress, we will essentially be stuck with it forever.

This treaty is written in such a way that the United States will be permanently bound by all of the provisions and will never be able to alter them unless all of the other countries agree.

Are you starting to understand why this treaty is so dangerous?

This treaty is the key to Obama's "legacy".  He wants to impose his will upon 40 percent of the global population in a way that will never be able to be overturned.

Of course Obama is touting this treaty as the path to economic recovery.  He promises that it will greatly increase global trade, decrease tariffs and create more jobs for American workers.

But instead, it would be a major step toward destroying what is left of the U.S. economy.

Over the past several decades, every time a major trade agreement has been signed we have seen even more good jobs leave the United States.

And it doesn't take a genius to figure out why this is happening.  If corporations can move jobs to the other side of the planet to nations where it is legal to pay slave labor wages, they will make larger profits.

Just think about it.  If you were running a corporation and you had the choice of paying workers ten dollars an hour or one dollar an hour, which would you choose?

Plus there are so many other costs, taxes and paperwork hassles when you deal with American workers.  For example, big corporations will not have to provide Obamacare for their foreign workers.  That alone will represent a huge savings.

Any basic course in economics will teach you that labor flows from markets where labor costs are high to markets where labor costs are lower.  And at this point it costs less to make almost everything overseas.  As a result, we have already lost millions upon millions of good jobs, and countless small and mid-size U.S. companies have been forced to shut down because they cannot compete with foreign manufacturers.

Later this month, consumers will flock to retail stores for "Black Friday" deals.  But if you look carefully at those products, you will find that almost all of them are made overseas.  We buy far, far more from the rest of the world than they buy from us, and that is a recipe for national economic suicide.

We consume far more wealth that we produce, and anyone with half a brain can see that is not sustainable in the long run.  The only way that we have been able to maintain our high standard of living is by going into insane amounts of debt.  We are currently living in the largest debt bubble in the history of the planet, and at some point the party is going to end.

Please share this article with as many people as you can.  We need to inform people about what Obama is trying to do.

If Obama is successful in ramming this secret treaty through, it is going to do incalculable damage to what is left of the once great U.S. economy.

November 12, 2014

Russia to Launch New Payments System to Circumvent SWIFT Network

Many observers have become unduly excited about what they depict as efforts to break the dollar hegeomony, such as the joint effort by the so-called BRCS nations to form a development bank. While having a suite of internationals funding entities, particularly ones focused on activities that in theory increase the collective benefits of relying on a reserve currency, are seen to be important, it does not follow that launching useful new funding institutions will break dollar dominance. As much as US abuse of its position as issuer of the reserve currency is correctly resented, there isn’t a competitor waiting in the wings. The Eurozone has blown it with its failure to clean up even sicker banks than the US has, and by compounding a bad situation with its adherence to destructive austerity policies. China clearly has the potential to displace the US longer-term, but it is unwilling to run the requisite trade deficits, since that means exporting demand and hence jobs. And no country had made the transition from being a major exporter to being consumer-driven smoothly; a crisis or protracted malaise would also delay China displacing the US as currency top dog.

But not being able to get rid of the dollar any time soon does not mean that countries that the US is trying to punish by using its influence over international payments system won’t find nearer-term escape routes. Russia, which has become America’s enemy number one apparently for its sins of interceding in Syria, (when Congress was firmly opposed to military action), successfully standing up against a US-backed coup in Ukraine, of collaborating with Iran, and harboring Edward Snowden, has become the target of increasingly stringent economic sanctions. The ones that really bite are those aimed at Russian banks, which have foreign currency exposures, and have used foreign capital markets to issue debt and equity.

Russia today announced that it plans to launch a new payments system so that it will no longer need to use the payments system SWIFT. From RT:
Russia intends to have its own international inter-bank system up and running by May 2015. The Central of Russia says it needs to speed up preparations for its version of SWIFT in case of possible ”challenges” from the West. 
“Given the challenges, Bank of Russia is creating its own system for transmitting financial messaging… It’s time to hurry up, so in the next few months we will have certain work done. The entire project for transmitting financial messages will be completed in May 2015,” said Ramilya Kanafina, deputy head of the national payment system department at the Central Bank of Russia (CBR). 
Calls not to use the SWIFT (Society for Worldwide Interbank Financial 
Telecommunication) system in Russian banks began to grow as relations between Russia and the West deteriorated over sanctions. So far, SWIFT says despite pressure from some Western countries to join the anti-Russian sanctions, it has no intention of doing so… 
SWIFT, is currently one of Russia’s main connections to the international banking system, and if turned off, could hurt the Russian economy, in the short-term. Globally it transmits orders for transactions worth more than $6 trillion, and involves more than 10,000 financial institutions in 210 countries. According to SWIFT’s statute, the system has national groups of members and users in each country. In Russia it’s ROSSWIFT – the second biggest worldwide SWIFT association after the US.
I welcome reader comment, but I believe there are two issues here. First is that even though SWIFT is still open for business with Russia, it could be cut off at a future date. It can’t have escaped Moscow’s attention that Iran’s central bank and most other major banks were barred from SWIFT in 2012. From the Wall Street Journal:
The European Union said it was banning any kind of financial transactions with blacklisted Iranian financial firms, but U.S. policy makers made it clear they would keep up pressure for wider action. 
The Belgium-based Society for Worldwide Interbank Financial Telecommunication, or Swift, a financial communication and clearing system used by most of the world’s major banks, said it would comply with the EU order. 
The ban applies only to Iran banks that the EU has placed on a sanctions blacklist. They include Iran’s central bank and more than a dozen other firms. 
The U.S. Congress, meanwhile, is asking transactions with all Iranian banks to be ended, and is threatening penalties against Swift’s board and directors if they don’t cut all ties with Iran’s financial sector. U.S. lawmakers argue that Iran is shifting funding for its nuclear program out of the sanctioned banks into other firms.
Second is that setting up a payments channel outside SWIFT can enable Russia to establish a financial system for those who don’t want to be subject to US dictates. Banks that did business with Iran, both before and after the SWIFT sanctions, were hit with money-laundering sanctions. The payments were dollar payments and were cleared thought the banks’ New York branches, making them subject to US law. All dollar transactions between banks are settled at the end of the business day in New York; interbank payment systems ultimately depend on a central bank backstop, and many large payments run over the Fed’s interbank system, Fedwire. So there’s no way of engineering around this issue, at least as of now. Benjamin Lawsky, New York’s superintendent of financial services, threatened to yank the license for the New York branch of the first miscreant he dealt with, Standard Chartered.

Federal and British regulators were outraged over his move, but Federal regulators swiftly recognized that Lawsky had done them a huge favor. They vastly upped the ante when they went after other foreign banks that were defying the US by doing business through US payment systems with blacklisted foreign countries. Lawsky fined Standard Chartered for $340 million in 2012 and the Federal fines were an additional $327 million. As staggering as that was deemed to be at the time, it paled next to the $8.9 billion in fines plus criminal charges against BNP Paribas earlier this year. (Lawsky also hit Standard Chartered with a $300 million fine in August for continuing compliance failures.)

But many foreign banks, and even foreign regulators, were incensed by the magnitude of fines the US imposed for money laundering (as in using the US payments system to conduct transactions with verboten parties). French newspapers and politicians howled over the $8.9 billion fine against BNP Paribas. If the Russian payment system works (as in is NSA-proof, you can bet the US will set its best hacking talent against it), it would allow banks like BNP Paribas and Standard Chartered to deal with Iran. It would likely please them no end to get a bit of revenge on the US that way.

In addition, there are likely businesses in Europe that are not keen about how complying with the EU sanctions against Russia is hurting their business. It isn’t clear how many would be willing to walk on the wild side and defy sanctions, but processing transactions through a Russian-controlled payment system would be far less susceptible to detection than through SWIFT.

In other words, this measure is intended to reduce the effectiveness of using the dollar dominance in payments as a weapon. Whether the Russians can launch a robust enough system quickly is an open question, but this is a sensible defensive and potentially offensive measure. It may have longer-term ramifications if other countries that are not happy with the US decide to employ it for practical or political reasons. Stay tuned.


November 11, 2014

Petrodollar Panic? China Signs Currency Swap Deal With Qatar & Canada

The march of global de-dollarization continues. In the last few days, China has signed direct currency agreements with Canada becoming North America's first offshore RMB hub, which CBC reports analysts suggest "could double maybe even triple the level of Canadian trade between Canada and China," impacting the need for Dollars.But that is not the week's biggest Petrodollar precariousness news, as The Examiner reports, a new chink in the petrodollar system was forged as China signed an agreement with Qatar to begin direct currency swaps between the two nations using the Yuan, and establishing the foundation for new direct trade with the OPEC nation in the very heart of the petrodollar system. As Simon Black warns, "It’s happening... with increasing speed and frequency."

Authorized by China's central bank, the deal will allow direct business between the Canadian dollar and the Chinese yuan, cutting out the middle man — in most cases, the U.S. dollar.

Canadian exporters forced to use the American currency to do business in China are faced with higher currency exchange costs and longer waits to close deals.

"It's something the prime minister has been talking about. He wants Canadian companies, particularly small- and medium-sized businesses, doing more and more work in China, selling goods and services there," said CBC's Catherine Cullen, reporting from Beijing.
It’s happening. With increasing speed and frequency.

The People’s Bank of China and the Canadian Prime Minister’s office issued a statement on Saturday stating that Canada will establish North America’s first offshore renminbi trading center in Toronto.

China and Canada agreed on a number of measures to increase the use of renminbi in trade, business, and investment. And they further signed a 200-billion renminbi bilateral currency swap agreement.

Moreover, just today, hot off the presses, the central banks of China and Malaysia announced the establishment of renminbi clearing arrangements in Kuala Lumpur, which will further increase the use of renminbi in South-East Asia.

This comes just two weeks after Asia’s leading financial center, Singapore, became a major renminbi hub, with direct convertibility established between the Singapore dollar and the renminbi.
And as Black notes, everyone is in on the trend. All across the world, the renminbi is quickly becoming THE currency for trade, investment, and even savings.
Renminbi deposits in South Korea, for example, surged 55-times in one single year. It’s stunning.

The government of UK just issued a renminbi bond, becoming the first foreign government to issue debt in renminbi.

Even the European Central bank is debating to include renminbi in its official reserves, while politicians the world over are sounding not-so-subtle warnings that a new non-dollar monetary system is needed.

Nothing goes up or down in a straight line. And given how volatile Europe and the global economy continue to be, the dollar may certainly be in for its surges and bumps in the coming months.

But over the long-term it’s glaringly obvious where this trend is going: the rest of the world no longer wants to rely on the US dollar, and they’re making it a reality whether the US likes it or not.
And now, no lesser oil-producing state than controversial Qatar has signed an agreement too.. seemingly opening up the door to Petrodollar panic... (as The Examiner reports)
The petro-dollar system is the heart and soul of America's domination over the global reserve currency, and their right to make all nations have to purchase U.S. dollars to be able to buy oil in the open market. Bound through an agreement with Saudi Arabia and OPEC in 1973, this de facto standard has lasted for over 41 years and has been the driving force behind America's economic, political, and military power.

But on Nov. 3 a new chink in the petro-dollar system was forged as China signed an agreement with Qatar to begin direct currency swaps between the two nations using the Yuan, and establishing the foundation for new direct trade with the OPEC nation in the very heart of the petro-dollar system.

While this new agreement between China and Qatar is only for the equivalent of $5.7 billion over the next three years, Qatar becomes the 24th nation to open its Forex market to the Chinese currency, and solidifies acceptance of the Yuan as a viable option for the future in the Middle East.

China's central bank announced Monday that it has signed a currency swap deal worth 35 billion yuan (about 5.7 billion US dollars) with the central bank of Qatar.

The three-year deal could be extended upon agreement by the two sides,said a statement on the website of the People's Bank of China (PBOC).

Also on Monday, the two sides signed a memorandum of understanding on Renminbi clearing settlement in Doha. China agreed to extend the RMB Qualified Foreign Institutional Investor scheme to Qatar, with an initial quota of 30 billion yuan.

The deal marked a new step forward in financial cooperation between the two countries, and will facilitate bilateral trade and investment to help maintain regional financial stability, the statement said. - China Daily

It is perhaps no coincidence that the term for the new agreement is set for three years, and is within the exact time frame being predicted by the director of the Finance Institute under the Development Research Center of the State Council, Zhang Chenghui for the Renminbi to become fully convertible in the global financial system.

The need for new markets and a more stable trade currency in Qatar could be tied to a new report issued last week by French bank BNP Paribas which showed that petro-dollar recycling has fallen to its lowest levels in 18 years, signifying that even oil producing nations in the Middle East are finding it difficult to trust the U.S. dollar, and facilitate its use in trade due to its depreciation since the advent of the Federal Reserve's massive QE programs.

Nearly every week now, China, Russia, or one of the BRICS nations are finalizing agreements that supersede the old system of dollar trade and reliance on the petro-dollar system. And as many countries begin to reject the dollar due to the exported inflation that is growing in nations that are relegated to having to hold them for global oil purchases, alternatives such as the Chinese Yuan will become a more viable option, especially now that the Asian power has taken over the top spot as the world's biggest economy.
Source 

November 10, 2014

The System Is Terminally Broken

The Fed has formally “ended” QE, but it hasn’t really.  The Fed will continue reinvesting interest on its portfolio in more bonds and it will rollover maturities.  We saw what happens to the stock market a few weeks ago when Fed official James Bullard asserted that the Fed needs to start raising rates:   the S&P 500 quickly dropped 8%.  Right at the bottom of the drop, the very same Bullard issued a statement suggesting that QE should be extended.  This triggered an insanely abrupt “V” move back up to a new record high for the S&P 500.  Bullard either did this intentionally or is a complete idiot.

The stock market can’t function without Federal Reserve intervention.  The stock market lost 8% quickly on just the thought that the Fed might start raising rates.  Imagine what would happen if the Fed decided to “experiment” by shutting down its market intervention operations – both verbal and physical – for a month…

As for QE, if the Fed has achieved its objective of stimulating the economy, why doesn’t it start removing the $2.6 trillion of liquidity that it has injected into its member banks (LINK)?  This was money that was supposed to be directed at the economy.  How come it’s sitting on bank balance sheets earning .25% interest?  That’s $6.5 billion in free interest the Fed continues to inject into the Too Big To Fail banks.  But why?  What would happen if the Fed decided to “experiment” by removing this massive dead-pool of money from the banks?  The money isn’t really “dead,” it’s keeping the banks from collapsing.

I’m interested to watch the Government Treasury bond auctions now that the Fed is not there to soak up anywhere from 50-100% of each issue.  I wonder if the banks will be moving their $2.6 trillion in Excess Reserves into new Treasury issuance.  Obama is going around broadcasting the lie that the Government’s spending deficit in FY 2014 was something like $600 billion.  Yet, the amount of new Treasury bonds issued increased by $1  trillion over the same period.  Either Obama is lying or the accountants at the Treasury committed a big typo.  Either the Fed has found a way to continue opaquely monetizing new Government debt issuance, or the market is soon going to force U.S. interest rates up much higher.

By continuously intervening in all of the markets, the Fed has destroyed the information transmission system that is built into freely trading markets.  If the Fed left the gold market alone – instead of hammering away with the naked shorting of Comex paper gold – the price of gold would be significantly higher than where it is now.  This would be the market’s signal that our system is indeed terminally broken.

Instead, the Fed keeps interest rates artificially low in hopes of stimulating a recovery in consumption and housing. But if this is working, how come the country’s two largest retailers have begun Black Friday shopping discounts on November 3rd (LINK)?  And the Fed keeps pushing stocks higher to  new record highs in order to “stimulate” confidence and faith in the system.  The fact that the stock market craps its pants when the Fed steps away for a split-second tells us just how broken this transmission mechanism is.  That 8% drop 4 weeks ago is the real signal that our system is terminally broken.

And now it’s emerging that the Q3 GDP report was greatly inflated by a statistical error which erroneously boosted the Government spending component.  It was this component that juiced the GDP report because residential investment (housing) and personal expenditures (consumption) both tanked.    Imagine that – a statistical error artificially boosted the GDP report right before a national election…

A colleague of mine has concluded that the QE infinity policy implemented Friday in Japan is the market’s signal that the entire western fiat system is getting close to imploding.  I’m inclined to agree with him.  Wall Street, the financial media and politicians are pointing at Europe and Japan as the source of the problems.   But the heart and nerve center of the western fiat currency/debt Ponzi scheme is right under our nose in this country.   The U.S. financial system is in worse shape than both Japan and Europe.  The only difference is that the U.S. officials do a much better job hiding these problems.

Time is starting to run out for ability of the U.S. to keep kicking the can of collapse down the road.  I really believe that the full-on intensity of the recent intervention in the precious metals market is the most obvious signal of time expiring.  China has been accumulating physical gold at a stunning rate and now some research indicates that China’s Central Bank may have accumulated significantly more gold than anyone previously thought (LINK).   China has most likely maneuvered itself into owning the world’s largest stock of gold, which is where the U.S. had positioned itself after WW2.   China has done this to a large degree by buying massive quantities of western Central Bank gold.

We’ve come full circle, only with China in the Midas throne this time around.  Eventually the world is going to revert back to a gold-backed currency system.  When this happens, the U.S. will be required to demonstrate that it possesses the amount of gold that it reports to own. The only caveat here is that I believe that the U.S. will start WW3 before it’s forced to reveal the truth about its empty gold vault. That’s how broken our system really is…

November 7, 2014

Ritual Incantation - The Economic Gibberish Of The Keynesian Apparatchiks

If you want an illustration of the utter intellectual bankruptcy of our Keynesian policy overlords just review the attached Wall Street Journal piece on yet another downgrade by the EC of its official economic growth forecast. What’s illuminating is not that the savants of Brussels were wrong by a country-mile yet again, but that they persist in a mechanistic numbers game that resembles nothing so much as ritual incantation.

Yep, the Keynesian priesthood is operating from sacred texts and magic numbers. One of these revelations says that 2% inflation was decreed by the great god of GDP and that any shortfall will precipitate his wrathful extractions from growth and jobs. But there is not a shed of empirical evidence for 2% versus 1% or 3% annual change in consumer inflation—–even if it were honestly measured. Its just revealed word as transmitted by the Keynesian priesthood.

Another sacred tenent avers that in handing down the laws of proper economic life, the Keynesian creator ordained that governments everywhere and always must strive to bring GDP growth to its full employment “potential” rate.  No exceptions. World without end.

While the texts are not clear on the precise numeric value of this divinely ordained rate of potential GDP growth, today’s congregants claim that it’s about 3%, reflecting the historic trend growth of the labor supply plus productivity gains. In fact, however, we have achieved only about half of that—about 1.8% per annum—-in the US during the last 14 years, and even a lesser fraction in Europe.

Accordingly, this imaginary trend line of “potential GDP” is now far above actual output levels. This yawning gap between the real economy and its revealed potential, in turn, enables the Keynesian priesthood to demand an endless crusade by the fiscal and central banking agencies of the state to close it.

This essentially means that the state’s economic apparatus is now all about stimulus, all of the time. In fact, the state’s central banking branch has gotten so deep into ritualized Keynesian governance that it’s essentially attempting to micro-manage vast accumulations of GDP—-about $17 trillion each in the US and Europe—-on a monthly basis.That’s entirely what the meeting statements and post-meeting press conferences are all about.

Yet this is absurd. The information flow in a $17 trillion economy is far too vast to be digested and assessed by the 12 mortal members of the FOMC, and their policy control instrument—-the bludgeon of interest rate manipulations—- could not  possibly shape its short-run course in any event. That’s especially true since the macro-economy is not a closed system, but one open to every manner of complicating and countervailing influence from trade, capital flows and financial impulses in a $80 trillion global economy.

Still, the Keynesian policy apparatchiks have not even an inkling that they are attempting the impossible or that their patter about objectives, forecasts and policy actions have gotten downright moronic. And here’s where the EC’s latest retreat on its official forecast is so ludicrously illustrative.

Given the massive complexity of the global economy—plus the tidal forces being unleashed by Japan’s yen destruction campaign, the cooling of China’s monumental construction binge, the dead-in-the-water bankruptcy of most of Europe and the massive shift of income and wealth to the top 1% in America— no one in their right mind should attempt to predict GDP growth to the exact decimal point three years into the future or even one year for that matter. There are imponderables, uncertainties and aberrations everywhere, and none of them are in the Keynesians’ primitive DSGE models.

Yet like the Keynesian apparatus everywhere in the modern world, the EC bureaucrats are pleased to try, and feel compelled to make hairline adjustments twice a year—-mainly to cover their chronic back-pedaling on the near-term picture which, in any event, reveals itself soon enough.

Thus, not too long ago the EC projected that real output gains averaged across 18 hugely divergent eurozone economies would average 2.5% during 2015. By the time of this year’s spring forecast revision, the projection was down to 1.7%; and now its fall update downgrades it further to 1.1%. Yes, and while they were splitting economic hairs, the EC prognosticators decided to embrace nine months of “disappointing” reality that has already occurred and lower the 2014 forecast to 0.8% from the spring level of 1.2%.

While it was at it, the EC also resurrected its 1.7% GDP forecast—-which was projected for 2014 awhile back before it was lowered in semi-annual nicks to its current 0.8% level. It seems that this magical 1.7% growth number for the third year forward is never really abandoned; its just rolled forward year after year. Indeed, it had  earlier been shuffled forward to 2015, but since that now seems out of reach, the Brussels prognosticators had no trouble seeing it coming clearly into view for 2016.

This paint-by-the-numbers ritual is ridiculous because it makes not a wit of difference whether the outlook for GDP three years into the future is 0.8%, 1.2%, 1.7% or any other number in that range. Its just noise and foolishness.

Why then do they persist in this pointless forecast ritual?  Well, because it is written in the sacred texts that policy action to close the GDP gap is imperative, and that the size of the gap and the requisite policy interventions depend upon a macro forecast. The latter is, in effect, their policy intervention map.

However, now that the output gap has become massive and the central bankers believe that there is vast “slack” in the labor force—- which is partly reflected in Europe’s official unemployment rates and largely obfuscated by the BLS’ dummied up U-3 numbers here—the Keynesian project faces a rude reality. Namely, that it is virtually impossible to believe that the “gap” and the “slack” are due to cyclical factors.

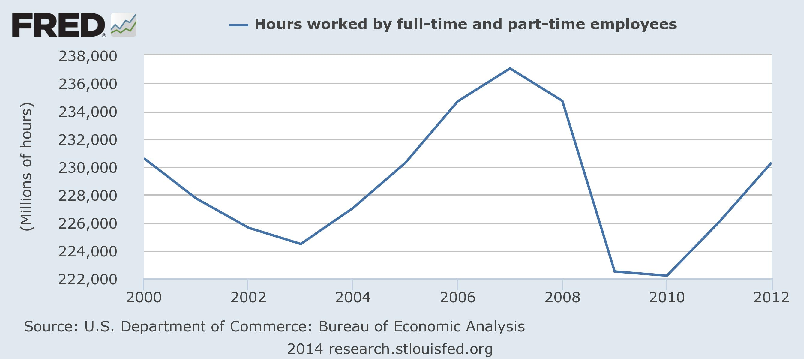
Two simple time series prove the case. First, there has been virtually no increase in non-farm labor hours actually consumed by the US economy over the past 15 years.  That’s not cyclical—–its a disastrous fundamental condition or trend.

Untitled

Secondly, real median household incomes have been trending down for the past 15 years, as well. That too is not about temporary “cyclical” slack; it is a measure of a failing, decaying national economy.


So today’s perpetual stimulus policy is utterly unsuited to the real problems at hand because these deep challenges dwell on the supply side of the economy. The latter has become freighted down with debt, taxes, regulatory barriers, crony capitalist inefficiencies and welfare state inducements to dependency. They have nothing to do with “aggregate demand”, and couldn’t be solved with even more household and business borrowing on top of the mountains of debt already on their balance sheets. The Fed’s lunatic ZIRP policy has already proven that it can’t actually stimulate credit fueled spending for consumer and capital goods owing to the roadblock of “peak debt”.

Yet the Keynesian apparatchiks continue to demand counter-cyclical “stimulus” because they are intoxicated in ritual incantation based on an earlier, more primitive Keynesian catechism. Those original texts called for episodic action at the bottom of the business cycle to prime the pump and overcome recessions. Stimulus was the exceptional condition, not the norm; it embodied the notion that after the state’s kick start——market capitalism could largely take care of itself. The corollary was that fiscal and monetary policy would rapidly normalize once the recovery commenced.

Indeed, the  “business Keynesians” of the early 1960’s promised that there would be an off-setting fiscal surplus during the top half of the cycle. Therefore “counter-cyclical deficits” were not a form of monetization of the state’s debts because the borrowing involved was held to be only temporary (i.e. would be repaid from recovery period surpluses). And central bankers like the great William McChesney Martin, who was no Keynesian at all, actually did endeavor to “lean against the wind” during the up-cycle and even take away the punch bowel just when the party got started.

But somewhere during the last two decades the Keynesian stimulus project migrated from the fiscal authorities to the central banks. This had far-reaching consequences because it shifted the locus of policy making from the unruly, paralysis prone machinery of legislative budgets and taxes to unelected bureaucrats and academics endowed with virtually plenary powers and 13 year terms.

What is worse, it put them in the full-time business of fiddling with the money and capital markets in the false belief that they could control the evolution of the macro-economy through its financial nerve center and deftly guide GDP back to the ordained path of full employment.

Consequently, all hell has broken loss. These interventions have not levitated the real economy, nor have they closed the imaginary output gap. Instead, massive central bank stimulus has destroyed honest capital markets and enabled a giant casino of speculators to feast on the free money and market props, puts and bailouts offered by the central banks.

Yet the true danger is not simply that the Keynesians are caught in a time warp. That is, that the fiscal Keynesianism taught by James Tobin in the 1960’s was OK because it was counter-cyclical help from the state to the private economy, but the 24/7 central banker Keynesianism practiced by his PhD student, Janet Yellen, has gone too far and is now obsolete.

No, Keynesianism was always wrong. It is predicated on the alleged inherent cyclical instability of market capitalism, and a purported tendency to chronically tumble into recession, depression and an economic black hole absent the ministrations of the state.

But the evidence for that is the founding event of the Keynesian gospel—–the Great Depression of the 1930s. Yet tragic as it was for mankind everywhere, the disaster of the 1930’s was not due to the inherent instabilities of capitalism or an unregulated free market.

Instead, the Great Depression was born in the financial mayhem of World War I, which destroyed the monetary system and engulfed the world in debt and inflation; and in the 1920s manipulations of the Fed, Bank of England and other central banks as they attempted to restore the pre-1914 status quo ante without the fiscal and financial discipline that was part and parcel of the prosperity and stability that flowed from the liberal international order based on the gold standard and free trade in goods, capital and labor.

All the milder business cycles since then have been generated by the state. These include the excesses of war finance and an overheated economy, as in the case the Korean and Vietnam wars; and the peacetime spells of excessive credit creation enabled by central banks, which had to then correct their own excesses through monetary stringency and recession.

In open economies and a global trading system the only thing which counts is prices, not aggregates.  America’s problem is that its production costs and labor prices are too high and its subsidies for inefficient production and non-production are too great. That is the reason why there is so much labor “slack” and why the growth of output and wealth has been so tepid since the late 1990s when the “china price” became the driving force in the global economy.

Stated differently, the Keynesian notions of “potential GDP” and “aggregate demand” have no basis in the real world. They are revealed doctrine. They are the religion of the state’s economic policy apparatus.

Its bad enough that this destructive economic religion leads to the farcical forecasting games evident in the EC’s chronic updates and slow-walks of the GDP numbers down. The evil, however, is that the Keynesian apparatchiks will not desist in their destructive money printing and borrowing until they have suffocated free market capitalism entirely, and have monetized so much public debt that the financial system simply implodes.

By Gabriele Steinhauser at The Wall Street Journal

The European Commission on Tuesday cut its growth forecasts for the eurozone and the European Union, citing the tensions in Ukraine and the Middle East along with a lack of investment.

The EU’s executive arm now also expects inflation in the eurozone to remain below the close-to 2% targeted by the European Central Bank until at least 2016. That is likely to boost expectations of stronger measures by the ECB such as large-scale purchases of government bonds and other assets.

The commission said it now expects gross domestic product in the 18-country eurozone to grow 0.8% this year, down from 1.2% growth it forecast this spring. In 2015, the eurozone economy will likely grow 1.1%, also less than the 1.7% growth seen in the spring. In 2016, growth in the currency union will rise to 1.7%, the commission said.

The forecasts for the eurozone were dragged down by lower than-expected growth in big countries, including Germany, France and Italy, the latter of which expected to fall back into recession this year.

The picture looks only mildly better for the broader EU. The 28 EU countries are now expected to grow on average 1.3% this year, down from 1.6% growth seen in the spring. Next year, EU GDP is expected to rise 1.5%, also below the 2% previously forecast. In 2016, growth is seen reaching 2%.

“The economic and employment situation is not improving fast enough,” said Jyrki Katainen, the European Commission’s vice-president for jobs and growth. “The European Commission is committed to use all available tools and resources to deliver more jobs and growth in Europe.”

Significantly for investors, the commission said eurozone inflation is likely to be 0.5% this year and 0.8% in 2015. Even in 2016, inflation in the currency union is forecast at just 1.5%, still below the close-to-2% targeted by the ECB, the commission said. Those 2014 and 2015 forecasts undershoot the ECB’s own inflation expectations released in September. At the time, the ECB said it expected eurozone inflation to be 0.6% this year and 1.1% in 2015.

Low growth and low inflation will make it much harder for the eurozone to recover from its debt crisis, causing big problems for high-debt countries such as Greece, Italy and Spain, among others.

Although most analysts don’t expect the ECB to announce new measures to stimulate inflation at its meeting on Thursday, Tuesday’s forecasts are likely to raise expectations of future action, including larger-scale asset purchases as were previously done by the U.S. Federal Reserve and the Bank of England.

Tuesday’s forecasts also form the basis for the commission’s assessment of national governments’ 2015 budgets. While the lower-than-expected growth could mean some countries get extra time to bring their deficits below the 3% of GDP allowed under EU law, they are also likely to underpin demands for new cuts in some countries, including France and Italy. According to the forecasts, both Paris and Rome will fail to cut their 2014 deficits by as much as previously promised, even when the effects of the weak economy are stripped out.