October 16, 2012

US Households Are Not "Deleveraging" - They Are Simply Defaulting In Bulk

Lately there has been an amusing and very spurious, not to mention wrong, argument among both the "serious media" and the various tabloids, that US households have delevered to the tune of $1 trillion, primarily as a result of mortgage debt reductions (not to be confused with total consumer debt which month after month hits new record highs, primarily due to soaring student and GM auto loans). The implication here is that unlike in year past, US households are finally doing the responsible thing and are actively deleveraging of their own free will. This couldn't be further from the truth, and to put baseless rumors of this nature to rest once and for all, below we have compiled a simple chart using the NY Fed's own data, showing the total change in mortgage debt, and what portion of it is due to discharges (aka defaults) of 1st and 2nd lien debt. In a nutshell: based on NYFed calculations, there has been $800 billion in mortgage debt deleveraging since the end of 2007. This has been due to $1.2 trillion in discharges (the amount is greater than the total first lien mortgages, due to the increasing use of HELOCs and 2nd lien mortgages before the housing bubble popped).

In other words, instead of actual responsible behavior of paying down debt, the primary if not only reason there has been any "deleveraging" at all at the US household level, is because of excess debt which became insurmountable, not because it was being paid down, the result of which is that more and more Americans are simply handing their keys in to the bank and walking away, and also explains why the US banking system is now practicing Foreclosure Stuffing, as defined first here, as the banks know too well, if all the housing inventory which is currently in the default pipeline were unleashed, it would rip off any floor below the US housing "recovery" which is not a recovery at all, but merely a subsidized bounce, as millions of units are held on the banks' books in hopes that what limited inventory there is gets bid up so high the second housing bubble can be inflated before the first one has even fully burst.


Naturally, two concurrent housing bubbles can not happen, Bernanke's fondest wishes to the contrary notwithstanding, especially since as shown above, US households do not delever unless they actually file for bankruptcy, and in the process destroy their credit rating for years, making them ineligible for future debt for at least five years. It is thus safe to say that all the other increasingly poorer US households (who are not getting paid more as we showed this morning with the chart showing Y/Y change in US household earnings) are merely adding on more and more debt in hopes of going out in a bankrupt blaze of glory just like everyone else: from their neighbors, to all "developed world" governments.

And why not: after all this behavior is being endorsed by the Fed with both hands and feet.

October 15, 2012

Why is a Price-Fixing/Collusion Lawsuit Against the Biggest Names in Private Equity Getting Only Cursory Notice?

It’s troubling that some stinging charges against the very biggest names in private equity are getting only passing attention in the financial media.

The New York Times last week managed to get some court filings unsealed last week in a class action lawsuit, Dahl v. Bain Capital Partners. This revelation came after the parties tried to satisfy the NY’s motion with a heavily redacted filing, which the judge nixed. This short post by yours truly in the New Republic gives an overview; due to space constraints, I had to stay pretty high level:
One of the salutary side effects of the Mitt Romney presidential bid is that it has shed light on one of the most secretive yet influential parts of the financial services industry: the major buyout firms. Thanks to motions filed by the New York Times, a federal judge in Boston released court filings this week that had previously been under seal in a class action, anti-trust lawsuit — Dahl v. Bain Capital Partners — against the eleven biggest and most blue-chip names in the private-equity industry, including Blackstone, Carlyle, Goldman, and TPG. The plaintiffs contend that they lost billions as shareholders in companies that were sold at lower prices than they would have otherwise fetched in the 2003 to 2007 period due to buyer collusion through a system they called “club deals.”
No wonder the defendants had been keen to keep the case under wraps. The 221-page complaint goes through 27 transactions, and with each, presents not only persuasive economic analysis, but more important, damning e-mails showing how the heads of each of the firms were involved in submitting sham bids, sharing information about their offers, working with management of the target companies to restrict the sales process, enforcing elaborate systems of quid pro quos (for instance, not submitting a bid with the expectation of being cut in on that deal or future deals), and other forms of market manipulation. The messages make clear that the intent was to reduce competition and buy the companies on the cheap. For instance, on the sale of Toys R’ Us,
KKR representatives admitted that KKR decided to partner with Bain and Vornado due in part to its “desire to effectively eliminate a competitor from the auction process.”…. Richard Friedman, head of merchant banking and PIA at Goldman Sachs, acknowledged in an email the belief that “the competing bidders ha[d] colluded and ganged up.”
It’s obvious that reducing the number of bidders and containing the competition among them would lower prices. I ran a mergers and acquisitions department in the 1980s, shortly after auctions became the preferred way for selling companies. The rule of thumb was that getting an additional bidder increased the sales price by 10 percent. The complaint includes economic analyses that show that these mega funds got better prices on average on these deals than on the ones where they duked it out.

Now after ordinary consumers have been on the wrong end of bank bailouts, foreclosure fraud, credit card tricks and traps, and debt collectors from hell, this scheme might seem like a fight between different types of investors and hence of limited real world import. That view could not be more wrong. Private equity firms concentrate enormous financial power in comparatively few hands. Their $2 trillion of assets under management, which they augment with a typical $3 of borrowed money for every $1 of their investors’ money that they put down, translates into $8 trillion of buying power. Compare that to the roughly $16 trillion value of the U.S. stock markets at year end 2011. More people in the U.S. work for companies owned by PE funds than belong to unions. More than half the corporate debt in the U.S. is rated junk, and the high leverage used by PE firms in their deals is far and away the biggest culprit. It’s a virtual certainty you are supporting the private equity industry. Public pension funds, whose monies come from state and local tax dollars, are one of the biggest investors in LBO funds, particularly the mega funds like KKR and Blackstone.

LBO firms fetishize secrecy and use their power to maintain it. Given that governments, both public pension funds and sovereign wealth funds, are important investors in these vehicles, their contracts with these firms are of public interest. Yet PE firm threats to turn away government investors in states where their agreements might be exposed through state Freedom of Information Act requests have led to extreme measures such as the passage of state laws to keep executed private equity from being classified as public records, unlike every other contract for goods and services. This double standard pervades the funds’ dealings with their investors. For instance, the extensive communications among private equity firms presented in Dahl v. Bain look to a layperson like clear-cut anti-trust violations. Yet the PE firms try to cow their investors by claiming that communicating with each other could violate anti-trust laws!

It’s time to pull the veil off this industry. Public interest requires much greater transparency. Congress should call hearings and require that the heads of these private equity firms testify under oath. And any settlement in this case should be a matter of public record.
I wish there had been more space in the TNR post to provide extracts from e-mails, which are typically among either the heads of the mega buyout firms, or other managing directors. They show a clear understanding of what they were up to. These players were engaged in an effort to collude, by submitting sham bids, not bidding in the auction but being invited in as a co-investor on that deal later or getting a slice of a future deal, all clearly intended to buy the target companies at more favorable prices. You really need to skim the filing. If you thought the quotes from the Libor traders in the FSA’s letter to Barclays were damning, they pale in comparison to this (the juicy stuff starts on page 26 of the pdf, which is numbered page 22):
A Lawsuit Against Private Equity
And the riveting quotes are only half of it. The filing also discusses, as asides, how investemnt banks would steer deals to private equity buyers (“financial buyers” in the parlance) rather than corporations (“strategic buyers”) because they’d rack up far more fees. And in case the pleased quotes from the PE overlords about the success of their efforts aren’t enough to persuade you, the filing also includes extensive deal by deal analysis.

Now admittedly, one reason for the understated media response is this is a private suit, not one by a regulator. But flip this around: where is the Department of Justice? It issued civil investigative demands to some of the firms who are defendants in this suit, including KKR, Carlyle, and Silver Lake, in October 2006. The content of these e-mails, along with the extensive and persuasive economic analysis of the transactions, raise serious question about the failure of the Department of Justice and the FTC to move forward.

This Department of Justice overview document titled “Price Fixing, Big Rigging, and Market Allocation Schemes” is admittedly written informally, to encourage individuals to contact the Department of Justice, but it is instructive to read it against the sort of behavior presented in the Dahl v. Bain Capital Partners filing. Consider this section:
Most criminal antitrust prosecutions involve price fixing, bid rigging, or market division or allocation schemes. Each of these forms of collusion may be prosecuted criminally if they occurred, at least in part, within the past five years. Proving such a crime does not require us to show that the conspirators entered into a formal written or express agreement. Price fixing, bid rigging, and other collusive agreements can be established either by direct evidence, such as the testimony of a participant, or by circumstantial evidence, such as suspicious bid patterns, travel and expense reports, telephone records, and business diary entries.

Under the law, price-fixing and bid-rigging schemes are per se violations of the Sherman Act. This means that where such a collusive scheme has been established, it cannot be justified under the law by arguments or evidence that, for example, the agreed-upon prices were reasonable, the agreement was necessary to prevent or eliminate price cutting or ruinous competition, or the conspirators were merely trying to make sure that each got a fair share of the market.
It’s hard to read the private lawsuit and not wonder why this behavior didn’t lead to a criminal investigation by the DoJ. Might it have something to do with the importance of private equity in funding the Obama campaign? Rahm Emanuel raised lots of money from PE kingpins, and at least two of Obama’s New York City fundraisers were hosted by LBO heavyweights.

As Matt Taibbi has pointed out, big rigging is not like what the Mafia does, it is what the Mafia does. Yet the harm here seems too remote to ordinary people, compared to, say, overpriced garbage services or municipalities blowing up thanks to toxic swaps.

If the Dahl allegations pan out, and they certainly look convincing, it provides further confirmation of the charge that these firms don’t even earn the returns they claim to (returns earned by cheating aren’t legitimate). And if their raison d’etre, that they provide better ourcomes than, say, an index of industrial firms (which we plan to address independent of the price fixing issue) is bogus, that means (ex the limited number of cases where they turn around failing companies) they are really in the business of extraction, looting, and transferring income from ordinary people to the top 0.1%. Not that many people don’t suspect that already, but there is a world of difference between instinct and proof. So no wonder the industry works so hard at secrecy, and must be delighted to have the lapdog Department of Justice by its inaction support that effort.

Source

October 12, 2012

An Overlooked Currency War in Europe

Yves here. One of the not-suffiently-discussed topics in the financial media is the tug of war over currency values, with the need to do post crisis damage control as the cover. For instance, after the initial round of QE, Brazil and India complained vociferously about the dual impact of a weaker dollar and higher commodity prices (yes, Virginia, some economists do think financial speculation can influence commodity prices) on their economies. If Europe contracts while growth in the US and China are also decelerating, it isn’t hard to imagine that the currency front will heat up even more.

This piece by Daniel Gros illustrates, surprisingly, that one currency manipulator has managed to operate under the radar so far. It will be interesting to see if his analysis gets traction in Europe.

By Daniel Gros Director of the Centre for European Policy Studies, Brussels. Cross posted from VoxEU

Switzerland has pegged its currency to the euro at a level that helps it sustain a 12% current-account surplus and one of the lowest unemployment rates in Europe. This column argues that the Swiss peg involves currency manipulation that is, as far as Europe is concerned, the same order of magnitude as China’s intervention. It has had a significant impact on the euro exchange rate and a non-negligible effect on the EZ economy.

A current-account surplus is the mirror image of a capital export. A country that is running persistent current-account surpluses is thus persistently exporting capital. An important question to consider is which sector is investing abroad, the private or the public sector? If it is the public sector which invests abroad, in particular if it is done by the central bank via the accumulation of foreign-exchange reserves, this is often called ‘currency manipulation’.

A commonly used indicator of the degree to which a country manipulates its currency is the accumulated stock of foreign-exchange reserves relative to GDP.

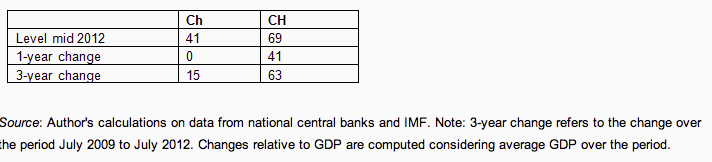
The table below shows the degree of foreign exchange intervention for two countries, which we will call “CH” and “Ch”.

The degree of influence on the domestic currency can be measured in two ways:
• The stock of foreign-exchange reserves as over GDP, or;
• The change in foreign-exchange reserves accumulated over the recent past, again relative to GDP.
Table 1 shows that on all measures CH emerges as the greater ‘manipulator’ than Ch. At the middle of 2012 the value of the foreign-exchange reserves (largely held in euro) of CH amounted to close to 70% of GDP; almost twice as much as the roughly 40% of GDP for Ch. Over the last 12 months Ch has actually stopped intervening, but this might be due to transitional factors. The three year perspective might thus be more appropriate. But even over this longer period, one finds that CH manipulates more than Ch.

Table 1. Foreign-exchange reserves, stocks and flows, as % GDP


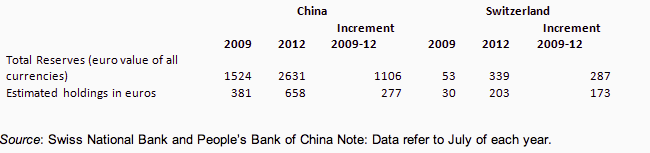
In reality Ch(ina) is a much larger country and the total amount of its interventions are much larger than CH (Confoederatio Helvetica). China has accumulated over €2630 billion ($3 trillion) worth of reserves, about seven times more (‘only’ seven times given the difference in the size of the economy, which is almost 12 to 1) than the about €340 billion ($400 billion) of Switzerland. But this latter amount is not insignificant at the scale of Europe. Moreover most of China’s foreign-exchange reserves are invested in dollars, whereas Switzerland has invested mainly in euros.

In the absence of data disclosure, one can only guess the currency composition of China’s reserves. According to various estimates, about 20-25% of China’s total foreign reserves are held in euro-denominated assets. This implies that over the last three years the People’s Bank of China has purchased about €270 billion, while Switzerland has done it for about €170 billion, somewhat less but fundamentally of a similar order of magnitude.
Table 2. Estimated reserves holdings in euros


Source: Swiss National Bank and People’s Bank of China Note: Data refer to July of each year.
The importance of the Swiss National Bank’s foreign currency interventions for the exchange rate of the euro can also be illustrated in the following way. The Swiss National Bank has intervened in the euro market to the tune of €173 billion over the last three years. If the ECB wanted to neutralise the impact on the euro’s exchange rate, it should have bought an equivalent amount of a foreign currency, say dollars. It is clear that if the ECB had bought $210 billion (€173 billion), the euro would presumably be much weaker today against the dollar. An intervention of the ECB of this scale would surely have been qualified as a real ‘currency war’ and would have led to significant conflicts among the major monetary powers. By contrast, the Swiss intervention caused barely a ripple.

The upshot is that over the last few years the Swiss National Bank has bought a large amount of euros to keep the Swiss franc artificially weak and since September 2011 it has set an official lower bound against the euro. However, this fact has attracted not even a cursory comment by policymakers anywhere whereas the Chinese interventions, which amounted to much less as a proportion of GDP (and which have stopped over the last 12 months) are almost universally condemned on both sides of the Atlantic. The differential treatment is even more surprising if one keeps in mind that Switzerland is running a current account equivalent to over 12% of GDP against less than 3% of GDP for China.

The Swiss Side of the Story

The official version of the Swiss story is simple. For over a decade the country had run large and rising current-account surpluses and kept a stable exchange rate (against the euro) without the need for any intervention, proving that these surpluses constituted market equilibrium. However, with the outbreak of the financial crisis ‘speculators’ started to consider the Swiss franc a safe haven, driving the currency to a level at which the Swiss export sector could not compete any longer. Under this view, the Swiss National Bank’s intervening heavily and then fixing the exchange rate against the euro was entirely justified.

However, this apologetic view does not take into account that the stability without intervention until 2008 was underpinned by a combination of factors that is unlikely to return i.e. Austrian local governments and households all over the new eastern member countries of the EU were willing to indebt themselves in Swiss francs because of its lower interest rates. Moreover, the global credit boom had made investment outside Switzerland appear as safe as a domestic investment. This illusion has now been shattered and private investors have understandably rushed to offload their exchange-rate risk on the Swiss National Bank. The official position is quite simple in its asymmetry.
Capital outflows are considered an equilibrium phenomenon during the upswing of a credit cycle, but capital inflows during the downswing are ‘speculative’ and must thus be neutralised.

The complaint that flows are ‘speculative’ and thus had to be countered does not ring true if one takes into account that even today the foreign-exchange reserves of the Swiss National Bank amount to ‘only’ two thirds of the sum of current account surpluses the country has accumulated over the last twenty years. It is also often argued that an excessive appreciation of the Swiss franc would damage export industries and tourism. Even leaving aside that Switzerland has one of the lowest unemployment rates in Europe, this argument does not make sense. It is clear that a decade of large current-account surpluses leads to an economic structure which cannot survive when capital flows turn around. An exchange-rate policy which seeks to cement an industrial structure which can survive only at an exchange rate which produces a double-digit current-account surplus is clearly beggar thy neighbour.

All in all it is clear that the actions of the Swiss National Bank to keep the Swiss franc low, and thus to perpetuate a current-account surplus of over 12% of GDP, have had a significant impact on the euro exchange rate and hence a non-negligible effect on the EZ economy.

The Swiss franc-euro exchange rate is important by itself given that exports of the EZ countries to Switzerland are about the same as exports to China (both around €90 billion in 2011). Moreover, the Swiss current-account surplus is relevant at the scale of the EZ, being equivalent to close to 1% of the EZ’s GDP, or the deficits of France and Italy combined. Switzerland’s peg to the euro has thus made the intra-EZ adjustment (elimination of current-account deficit in the south combined with lower surpluses in the North) significantly more difficult.

Moreover, most of the euro-denominated investments of the Swiss National Bank have presumably been in bank deposits and securities of the core countries. This means that its interventions have led to an even larger liquidity surplus within the German banking system and thus contributed materially to the huge claims accumulated by the Bundesbank within the TARGET 2 system.

Source

October 11, 2012

JPM's Dimon Builds Fiscal Cliff Bunker As CFO Exits "Balance Sheet Fortress"

Jamie "The Europeans have the will, but no way; The US has the way, but no will." Dimon had a very open and wide-ranging discussion with the Council on Foreign Relations today. The conversation ranged from the unfairness of the Bear Stearns' deal (poor chap - all that very limited downside from $2/BSC share, at least initially) to the immediate threat of the pending Fiscal Cliff - and his $100mm-debt-ceiling-preparedness war-room bunker, and America's longer-term fiscal profligacy (vigilantes moving against the US bond market is virtually assured - question is when and how). He also discussed the London Whale 'error' and went on to discuss the Greeks and the Eurozone's political and economic debacle in general. Some significant anti-administration rhetoric (ironic really), summed up with the veiled threat "Hey folks, if you think Washington and American Business can go to war with each other and it ends good - terrible error!"

Below are a few points Dimon made during the event:
On Investing in America: “The president, whoever he is next year, recognizes one thing for certain, they’re going into that office with a royal straight flush. I think this attitude, somehow, ‘how woe is me, how terrible, how America is lost. It’s just not true, folks. …This is still the best economy in the world. If you can invest in one place in this planet, it would be here.”

On JP Morgan’s London Trade Error: “We made a stupid error. I mean, we’re pretty disciplined risk people. But we made an error. We had a gap in the line. And, you know, we didn’t have this gap elsewhere. We have other flaws elsewhere, but, you know, we had a gap. We screwed up. By the way, that quarter, we made $5 billion. So yeah, it was a stupid error. … I should have caught it also. I didn’t. But it isn’t going to sink our ship.”

On Fiscal Cliff: “We have formed now a fiscal cliff war room, command center, all that kind of stuff going through to make sure we understand it all. We’ll be prepared. JP Morgan will survive the fiscal cliff. I just think it’s terrible policy to allow it to get close. ...There are all these potential outcomes and I would defy anyone to know what they are.”

On Greece and the Future of the Eurozone: “From an economic standpoint, Greece is not the issue. Greece is a couple of billion of dollars in debt. …The catastrophe is the default of Greece before you have a firewall to Italy and Spain, you’ll have a very good likelihood of a run on the banks in Italy and Spain. Italy and Spain don’t have the wherewithal to stop a run on the banks.” 
 
At the same time, the WSJ reports that Douglas Braunstein (51 year old CFO) will be stepping down...
J.P. Morgan Chase's chief financial officer is expected to step down and is likely to move into a different job at the bank, according to people close to the company.

Douglas Braunstein, 51 years old, has been finance chief at the largest U.S. bank, by assets, since 2010. Before that, the longtime deal maker ran J.P. Morgan's investment-banking operations in North and South America and was heavily involved in the bank's acquisitions of securities firm Bear Stearns Cos. and the failed banking operations of Washington Mutual Inc. WMIH +1.69%

Mr. Braunstein's status was diminished as part of an executive shake-up in July. Since then, he has reported to Matt Zames, 41, the company's co-chief operating officer, rather than Chairman and Chief Executive James Dimon.

It isn't clear where Mr. Braunstein will land at the bank, but the possibilities include J.P. Morgan's recently combined corporate and investment bank, these people said.

Mr. Braunstein declined to comment on his position as chief financial officer.

Mr. Braunstein is among J.P. Morgan executives facing outside scrutiny over the bank's handling of the trading mess in its Chief Investment Office, or CIO, a unit that manages the bank's cash. J.P. Morgan suffered a trading loss of $5.8 billion in the first half of 2012, and about a dozen regulatory or law-enforcement agencies are conducting inquiries into the trades, internal accounting and risk controls at the bank, and the adequacy of its public disclosures, according to people with knowledge of the probes and securities filings.

"Jamie is a big fan of Doug's and any potential move Doug decides to make would be unrelated to the CIO issue," said a senior person at the bank.

Mr. Braunstein and other executives dismissed initial news reports about a trader known as the "London whale," who was roiling debt markets with his large bets. On an April 13 conference call, Mr. Braunstein told analysts, "We are very comfortable with our positions as they are held today." He described the bets placed by the Chief Investment Office as part of a "very long-term" strategy to hedge the bank's risks. Mr. Dimon referred to outside concerns as a "complete tempest in a teapot."

J.P. Morgan in July said that Messrs. Dimon and Braunstein relied on the assurances of others at the bank when making those statements. Mr. Dimon has said he was "dead wrong." J.P. Morgan has said it could have additional losses of $800 million to $1.6 billion from the trades. J.P. Morgan might update investors on the status of the trades when it reports third-quarter results Friday morning.
Source

October 10, 2012

IMF Solutions Reinforce Problems

IMF: Global economic slowdown is getting worse, US must avoid 'fiscal cliff' ... Updated at 8:30 a.m. ET The International Monetary Fund said the global economic slowdown is worsening as it cut its growth forecasts for the second time since April and warned U.S. and European policymakers that failure to fix their economic ills would prolong the slump. Global growth in advanced economies is too weak to bring down unemployment and what little momentum exists is coming primarily from central banks, the IMF said in its World Economic Outlook, released ahead of its twice-yearly meeting, which will be held in Tokyo later this week. − NBC

Dominant Social Theme: The IMF is concerned.

Free-Market Analysis: The IMF is getting a good deal of play with a worried world forecast. The concern was stated in the IMF's "World Economic Report."

Here's a quote: "A key issue is whether the global economy is just hitting another bout of turbulence in what was always expected to be a slow and bumpy recovery or whether the current slowdown has a more lasting component," it said. "The answer depends on whether European and U.S. policymakers deal proactively with their major short-term economic challenges."

This is a typical elite theme – that only "policymakers" can deal with issues relating to the economy. The idea that the market itself could deal with economic issues is not one the top people at the IMF would be pleased to consider.

In fact, as we've often stated, the entire EU downturn, starting with the economic crisis of 2008 has been a kind of engineered takedown. It began with determined bank lending and ended with a "sovereign crisis."

But EU officials, decades before, are on record as stating that an economic crisis would have to be created in order to strengthen a political union. And that's just what's happening.

The IMF is front-and-center in all this because many of the policies now being applied to the EU's Southern – economically bleeding – flank have been developed by the IMF and now go under the all-embracing nomenclature of "austerity." Here's some more from the article:

Meanwhile, German Chancellor Angela Merkel arrived in Greece on her first visit since Europe's debt crisis erupted here three years ago, braving protests to deliver a message of support -- but no new money -- to a country seen by many as a prime example of Europe's ongoing and entrenched economic woes ...

In an interview with NBC's Andrea Mitchell, IMF chairwoman Christine Lagarde calls for urgent action from lawmakers to turn around the U.S. economy, saying that the combination of automatic tax hikes and spending cuts poses a major threat to the recovery.

The IMF forecast that global output in 2012 would grow just 3.3 percent, down from a July estimate of 3.5 percent. Households could face average $3,500 tax hit if Congress can't avoid 'fiscal cliff'
It also cut its expectations for China in 2012 and 2013 but warned against being overly pessimistic about the prospects of these economies, which were major engines of growth in the global financial crisis.

"Let me be clear. We do not see these developments as signs of a hard landing in any of these countries," IMF Chief Economist Olivier Blanchard said at a briefing, referring to China, India and Brazil.

The IMF said "familiar" forces were dragging down growth in advanced economies -- fiscal consolidation and a still-weak financial system, the same problems that have plagued the world since the global financial crisis exploded in 2008.

"More seems to be at work, however, than these mechanical forces -- namely, a general feeling of uncertainty," Blanchard said in a commentary on the forecasts.

In point of fact, the "familiar forces" dragging it down are generated by Western central banking that prints too much money, causing both a boom and a bust.

The combination of the euro and monopoly central banking are responsible for European ills. The "crisis" is manmade.

Additionally, the US "fiscal cliff" is the result of (badly) engineered socio-economic policy. No matter where one turns to look, it is the modern money system itself that is responsible for the damage the IMF now warns against.

Take a step back and it is easy to see that the great economies throughout the world are all in the grip of recession, depression and inflation. The BRICS, Europe and the US are not going to see renewed economic vitality any time soon.

IMF policies are not improving matters. Raising taxes during bad economic times, as the IMF demands, only makes the problem worse.

If one grants that the elites behind the IMF and the current money system are generally in favor of global government and a global currency then what's going on now begins to make more sense.

While expressing concern over world economic problems, the IMF continues to be a conduit for the difficulties it warns against. It helps create the problems it then warns against.

In a Keynesian central banking environment, the solution to economic ills is held to be continued money printing. But it is excessive money printing that creates the booms and busts that have brought the world's economy to this state.

The IMF's remedy will thus only make things worse. Inflating the money supply will inevitably lead to price inflation.

Conclusion: IMF officials are recommending policies that will only aggravate global economic ills. What's the sense of that?

Source

October 9, 2012

Revolving Door: New Goldman Sachs Guy, Andrew J. Donohue

Andrew Donohue went from Merrill Lynch Investment Managers to the US Security and Exchange Commission (SEC) where he worked from May 2006 to November 2010. Now Donohue is moving back to Wall Street to Goldman Sachs as managing director and general counsel.

There must be a way to insulate regulatory bodies like the SEC from the constant influence of Wall Street and Goldman Sachs. That is where the changes in the financial system should be concentrated. As long as the revolving door includes the special interests of Wall Street proceeding in and out of regulatory bodies, there will be conflicts of interest.

Andrew Donohue expressed his personal views on investment company regulations when he appeared before the Subcommittee on Capital Markets and Government Sponsored Entities in June 2011. There he talked about changes that have been made and future changes that could be made to SEC rules.

He believes that an asset manager "does not pose a threat to the financial stability of the United States" (p.9). He warns that derivatives and other complex financial instruments need a regulation regime of their own and should not depend solely on old rules dating back to 1940. He said the SEC needs the resources to properly carry out its regulatory functions.

See the article called Street Moves: Goldman Hires Ex-SEC Investment Management Directory by Dow Jones in Fox Business.

Source

October 8, 2012

“What if the Global Financial Crisis is Permanent?”

Yves here. I’m featuring a MacroBusiness post, “What If the GFC is Permanent?” despite its being a bit meandering, because it asks some Big Questions, and therefore will give readers something to chew over.

The headline doesn’t quite get at what the post is about. Its focus is a recent paper by Robert Gordon questioning whether growth is over. I’ve read the underlying paper; MacroBusiness’s relies on a comment by Martin Wolf that discusses it. Key sections of its abstract:
There was virtually no growth before 1750, and thus there is no guarantee that growth will continue indefinitely. Rather, the paper suggests that the rapid progress made over the past 250 years could well turn out to be a unique episode in human history…
The analysis links periods of slow and rapid growth to the timing of the three industrial revolutions (IR’s), that is, IR #1 (steam, railroads) from 1750 to 1830; IR #2 (electricity, internal combustion engine, running water, indoor toilets, communications, entertainment, chemicals, petroleum) from 1870 to 1900; and IR #3 (computers, the web, mobile phones) from 1960 to present. It provides evidence that IR #2 was more important than the others and was largely responsible for 80 years of relatively rapid productivity growth between 1890 and 1972. Once the spin-off inventions from IR #2 (airplanes, air conditioning, interstate highways) had run their course, productivity growth during 1972-96 was much slower than before. In contrast, IR #3 created only a short-lived growth revival between 1996 and 2004. Many of the original and spin-off inventions of IR #2 could happen only once – urbanization, transportation speed, the freedom of females from the drudgery of carrying tons of water per year, and the role of central heating and air conditioning in achieving a year-round constant temperature.

Even if innovation were to continue into the future at the rate of the two decades before 2007, the U.S. faces six headwinds that are in the process of dragging long-term growth to half or less of the 1.9 percent annual rate experienced between 1860 and 2007. These include demography, education, inequality, globalization, energy/environment, and the overhang of consumer and government debt. A provocative “exercise in subtraction” suggests that future growth in consumption per capita for the bottom 99 percent of the income distribution could fall below 0.5 percent per year for an extended period of decades.
I’m a bit dubious of tying the underlying problem of growth to getting out of the global financial crisis, although they certainly interact in nasty ways. If you look at our last big financial crisis, the Great Depression, it occurred in what Gordon would characterize as an underlying period of growth. Peter Temin has argued, and his analysis is persuasive, that the Depression came out of a breakdown of a paradigm that had performed well in terms of promoting trade and international stability, that of the gold standard. It was suspended in World War I and Temin contends that the efforts in the 1920s to restore it led directly to the Great Depression. A 31 year crisis (from 1914 till a new financial order was negotiated in Bretton Woods in 1944 and was implemented in 1945) is well nigh permanent from the perspective of those living through it. So even before you get to Gordon’s reasons for doubting that past rates of growth can be restored, a global financial crisis can be a symptom of the end of a set of a financial arrangements, and the time it takes to accept that and implement new arrangements can be protracted. As we warned in ECONNED:
All these factors play a role in the hesitance to impose tough reforms, but the most intractable and least recognized is the last, the difficulty of seeing that the failings of the current system are deeply rooted and not amenable to simple remedies. Any resolution of the major problems facing the financial system would take a good deal of time, care, and persistent effort, and would simultaneously be highly politicized. That makes it very likely that the financial services industry will derail or blunt reform efforts. That in turn means the current paradigm will be patched up and restored to service only to fail again. This pattern will replay until the breakdown is beyond repair.
By Michael Feller, an investment strategist. Cross posted from MacroBusiness

While Europe may be reaching a deal of sorts between Teutonic lender and Latin borrower, and while pre-election America may appear to be regaining momentum in the form of lending and employment data, economic turbulence has merely moved eastwards in its slow, global orbit.

With the Asian Development Bank cutting regional growth forecasts from 6.9% to 6.1%, and Future Fund chief David Murray warning of an external finance shock in Australia, IMF chief economist Olivier Blanchard seems right when he forecast on Wednesday that the world would not recover from the financial crisis until at least 2018.

But what if Blanchard were wrong? What if his premise was incorrect? Certainly, there is a very real structural slowdown in China, a pause in the consumption rates of South Asia and Indonesia, and a continuing malaise in Japan, but what if we didn’t look at this as a crisis, but as statis? What if our obsession with economic growth and measures of growth turned out to be an illusion.

The Financial Times’ Martin Wolf opened this can of worms on Tuesday, asking if unlimited growth was a thing of the past. Citing research on historic rates of productivity by economist Robert Gordon, Wolf questioned whether our current third industrial revolution – that of information, rather than steam and mechanisation in the 19th, or urbanisation and middle class expansion in the 20th century – was really all that profound.

Who, for instance, would trade Facebook or an iPhone for indoor heating or a flushing toilet? What economic gains could broadband have over the original subsea telegraph? Could the benefits of green energy really compare to the discovery of alternating current or the invention of the turbine?

These are questions others have asked as well, ranging from the longue durée historians of the Sorbonne, who are attempting to pinpoint capitalism’s demise by 2100 (economic systems, like those of feudal Europe or the Roman Empire, apparently last 600 years), to UBS strategist Andy Lees, who last year provocatively claimed the world had hit its innovation peak in the 1840s.

Furthermore, these questions are not new. William Morris, better known for his wallpaper designs, wrote of a cashless society in late Victorian England. In 1516, philosopher Thomas More described the isle of Utopia where gold and silver were cast aside for pursuits of real prosperity, the metals only used for the “humblest items of domestic equipment”.

And of course, there was John Stuart Mill, who in 1848 would advance the notion of the ‘stationary state’, where objectives of economic quality were to be pursued over objectives of economic quantity. This no-growth model would later have appeal for Kibbutzniks, survivalists, and environmentalists such the authors of the 1972 Club of Rome report – who reintroduced Mill’s concept of the limits of growth to a new Malthusian audience. Even John Meynard Keynes, an admirer of Mill, would at times lament the obsession politicians would come to have with GDP, an instrument of measurement he helped devise for limited use during the Second World War.

Yet Mill’s legacy is perhaps most relevant today with global populations now stabilising, the risks of catastrophic climate change becoming ever more apparent, technology supplanting labour and productivity seen by many economists as the last great hope for growth. Indeed, outside of canonising modern liberalism or the idea of falsification in the scientific method, Mill’s most important contribution to political economy was arguably his theory of development: that growth was a function of capital, labour and land (or natural resources). Mill felt that sustainable development was only possible if growth in labour was exceeded by growth in land and capital productivity, rather than debt. With middle class wages stagnating and the so-called 99% seeing few of the economic gains that we are supposed to have made since the economic deregulation of the 1980s, Mill’s dictums speak a remarkable truth across the gulf of time.

In a week where prominent fund manager Bill Gross likened America’s credit-based economic model to a crystal meth addiction (like any ‘hopium’ or narcotic, debt borrows the benefits of tomorrow for the enjoyment of today) and when central banks, from Australia to Russia, are joining peers in Europe, Britain, the US and Japan in pushing down rates or pump-priming markets with liquidity, one can see another of Mill’s classic warnings – the tyranny of the majority – coming true, with quick fixes and short-term solutions the order of the day.

Yet no country is as perhaps as apt for Mill’s analysis than China: a country that is in a self-imposed demographic decline, where utilitarianism and capital factor productivity have been warped into a fixed-asset bubble and where land is quite literally denuded of soil, drained of moisture and acidified by the detritus of industrialisation.

In an oped for the New York Times last week, economist Richard Easterlin described China’s belief it could purchase social stability through rapid economic growth as a “Faustian bargain”; a phrase also used recently by Bundesbank chief Jen Wideman’s in criticising the European Central Bank’s outright monetary transactions.

In a survey of opinions on life satisfaction scored between 1990 and 2011, Easterlin and his colleagues found that the average Chinese is no more satisfied today than they were in the aftermath of Tiananmen Square. Moreover, scores on satisfaction for urbanites actually declined for most of the period, as old social safety nets – China’s so-called ‘iron rice bowl’ – were removed in the name of productivity, efficiency and, ultimately, economic liberalisation, and as the competitive urges of capitalism overtook the cooperation, forced as it was or not, of socialism.

Yet unlike other post-Enlightenment political philosophies – both the capitalism of Adam Smith or the communism of Karl Marx – Mill saw growth as more than material. Borrowing from its classical antecedent – the Ancient Greeks spoke of humanity’s goal aseudaimonia, or flourishing – modern society is built on the ideal of improvement, development, growth and expansion, but it needn’t be so mono-dimensional. Indeed, Aristotle considered an essential pillar of eudaimonia, or one of the four cardinal virtues, to be moderation.

The problem is that in many ways we may have already reached the limits of growth. Politicians like to talk about half-glass full and half-glass empty, yet ultimately we’re still drinking from the same poisoned chalice. By relooking at John Stuart Mill there may be a more refreshing alternative.

Source

October 5, 2012

'Economies Are Not Watches and Money Flows Are Not Predictable'

Multiplying Europe's fiscal suicide (technical) ... The entire EU austerity plan is based on a false premise. This disastrous error is now clear beyond any reasonable doubt. The Teuto-Calvinists believe – or profess to believe, since much of their dogma is national self-interest dressed up as theory – that the fiscal multiplier is around 0.5. That is to say, fiscal retrenchment worth 1pc of GDP will cut output by half as much, or around 0.5pc over two years. There is pain, but at least there is gain. This is based on the IMF's analysis of fiscal crises over the decades. Well, it has not worked out like that. Ireland has contracted at nearly seven times the speed, Spain four times, and Greece three times. – Ambrose Evans-Pritchard/UK Telegraph

Dominant Social Theme: Technocratic approaches make the most sense. If you simply plan by the numbers you can organize everything.

Free-Market Analysis: Ambrose Evans-Pritchard is back with another try at organizing the world according to "monetarism."

Long ago, we recall reading that this adept mainstream journo did NOT consider himself a monetarist, or Keynesian, or anything else mainstream but in this article he seems to be trying on monetarist garb.

Ironically, what we draw from this article is that financial prognostication doesn't work. Evans-Pritchard, while proselytizing for monetarism, does a good job of demolishing IMF nostrums. Further down, we shall attempt to puncture monetarist ones.

We shall be left then with standard (Austrian) free markets. As Peter Schiff has asked in the past, "What else is there?" Nothing else stands up to scrutiny, in our view.

Back to Evans-Pritchard. His point is that IMF predictions about economic behavior simply don't work and are, in fact, making things worse. Here's more from the article:

As you can see, the multiplier is around 1.0 for the big countries, which is why France can expect a devastating year in 2013 as it tightens pointless by 2pc to comply with EU rules. And why the world faces a full-blown shock if the US goes over the fiscal cliff and tightens by 4pc next year. The multiplier is nearer 2.0 for part of the Club Med bloc.

So what went wrong? It is blindingly obvious. The IMF data – and indeed the more extreme theory of `expansionary fiscal contractions' (which the IMF does not endorse) – is based on past cases where individual countries were able to claw their way out of trouble by exporting to a healthy global economy, usually by devaluing first and often by slashing interest rates as well.

Greece, Spain and Italy cannot devalue. Most of Europe is tightening fiscal policy in lockstep. They are all dragging each other down. It is synchronised policy suicide. The European Central Bank has made matters worse. It has withheld the monetary stimulus desperately needed to cushion the fiscal shock. It allowed broad M3 money to contract earlier this year, in violation of its twin pillar mandate (the M3 growth target is 4.5pc).

The ECB has quite simply abandoned its monetarist heritage. What has it become instead? Just a plain-vanilla inflation targeter, even as inflation targeting is thrown on the scrap heap by everybody else. Yet that is not the whole story. Monetarists themselves have to confront an unpleasant fact. Vast amounts of QE in Britain did less than hoped to offset the fiscal squeeze. The UK multiplier has been around 1.0. (though not 2.0, thank God)

It is the same story in the US, though America's QE has been much less as a share of GDP. Richard Koo from Nomura – an expert on Japan's twenty year ordeal – argues that the monetary lever is almost useless once firms and households batten down the hatches in a "balance sheet recession".
"The Cameron government's austerity programs pushed the UK economy into a double-dip recession even as the BOE pursued a record-large program of quantitative easing, showing that the economy will weaken during a balance sheet recession no matter what the central bank does. If the government fails to administer fiscal stimulus.

This demonstrated that the impact of monetary accommodation is limited during balance sheet recessions and that fiscal stimulus is essential in preventing a deflationary spiral from taking hold."

Much of this is self-explanatory, but the statement about how the Japanese have "battened down the hatches" is certainly interesting.

Actually, what is being explained here is analogous to Austrian explanations. The issue is not whether money is available but whether people wish to use it or whether they are battening the hatches.

People won't start new ventures unless they are fairly sure the system surrounding them is solvent.
In both the US and Japan (and Europe, too) central banks have distributed massive amounts of funds. As a result, citizens do not know what enterprises are solvent and which ones are being propped up. Not knowing, people are reluctant to start risky business ventures.

And so economies languish. We can see clearly that money circulation, the velocity of money, is only part of the equation. The other part is people's willingness to invest and "use" money.

For this to happen, economies must be "cleansed." This is actually the opposite of what's going on, which is one reason why we have written that the object of "easings" is actually the opposite of its stated purpose.

The ACTUAL result is a prolongation of pain and even a deepening of the current depressive malaise.

Why should the powers-that-be want to make things worse? Well ... order out of chaos. If you want to build global governance, you need to tear down the previous system. Of course, you can't SAY that, so most of the statements about monetary policy tend to be the opposite of reality.

In any event, though the money being printed isn't circulating from a venture perspective, it is going somewhere ... some of it, at any rate.

Yes, even though the Fed in the US is actually paying banks perversely to hold onto money (so it doesn't circulate), some of that new money-from-nothing finds its way into the stock market and also into commodities. The main part of it apparently buffers banks' bottom lines.

This is exactly what Money Power seeks, in our view. All the rest is so much obfuscation.

Evans-Pritchard disagrees. In this article, at any rate, he remains a monetarist. He explains:

I don't agree with Mr Koo. Britain most certainly has avoided a deflationary spiral. It has also avoided the sort of crash now gathering speed in Spain.

Moreover, I don't think the Japanese carried out QE with much vigour or through the proper mechanism. I remain convinced that central banks can defeat a slump by purchasing assets from non-banks, working through the quantity of money theory.

Unfortunately that is not what the Fed's Ben Bernanke is really doing. He is dabbling at the margins trying to manipulate the cost of credit a fraction lower. That is a fruitless policy.

The reduced costs for borrowers are largely offset by reduced incomes to savers and pensioners relying on interest income. That is not the way to get much traction.

Evans-Pritchard here is really worried about price deflation. He believes that if central banks print massive amounts of money, they can combat lower prices. Of course we are not so frightened of lower prices as Evans- Pritchard. Once again he has headed off course.

He starts promisingly by demolishing IMF arguments regarding economic projections. But he finishes by arguing what is to us a somewhat absurd point – that the mechanical injection of money into the market can counteract current depressive tendencies.

Mr. Evans-Pritchard ... it has to CIRCULATE first! This is the grim reality.

It has to be lent out, and even then the results will not be mechanical ones. Monetarist theories that claim to predict exactly what the results of money printing shall be are surely questionable because money trapped on the bank shelf is not circulating money. And NO ONE can predict when or how much of that money is going to circulate – and how fast.

Free-market economic theory has it right. Keynesian theories, monetarist theories – money-modeling theories in general don't provide us with any accurate prognostications. The only theory that provides us with any semblance of workability is the Austrian theory of business cycles – and this is only because it is general, not specific.

Evans-Pritchard, as he often does, has given us a lot to think about. And he does us a favor by deconstructing the monetary nonsense of IMF nostrums. But in the end he wanders off into a monetarist theory that is equally pernicious, from our point of view.

Modeling simply doesn't work. Monetary "policy" doesn't work, nor can a coherent case be made for it. All that "works" is monetary competition in the free market. It is the friction of competition that produces valid value and accurate pricing.

If those at the top of the current financial food chain ever acknowledged this, the entire rationale for the current central banking economy worldwide would collapse. Money competition is the answer, a free-market in money including gold and silver. Not more central planning, even of the monetarist kind.

Conclusion: Economies are not watches and money flows are not predictable.

October 4, 2012

The Fed Plays All Its Cards

There never really could be much doubt that the current experiment in competitive global currency debasement would end in anything less than a total war. There was always a chance that one or more of the principal players would snap out of it, change course and save their citizenry from a never ending cycle of devaluation. But developments since September 13, when the U.S. Federal Reserve finally laid all its cards on the table and went "all in" on permanent quantitative easing, indicate that the brainwashing is widely established and will be difficult to break. The vast majority of the world's leading central bankers seem content to walk in lock step down the path of money creation as a means to economic salvation. Never mind that the path will prevent real growth and may ultimately lead off a cliff. The herd is moving. And if it can't be turned, the only thing that one can do is attempt to get out of its way.

The details of the Fed's new plan (which I christened Operation Screw in last week's commentary) are not nearly as important as the philosophy it reveals. The Federal Reserve has already unleashed two huge waves of quantitative easing (purchases of either government securities or mortgage-backed securities) in order to stimulate consumer spending and ignite business activity. But the economy has not responded as hoped. GDP growth has languished below trend, the unemployment rate has stayed north of 8%, and the labor participation rate has fallen to all-time lows. In the meantime, America's fiscal position has grown significantly worse with government debt climbing to unimaginable territory. Despite the lack of results, the conclusion at the Federal Reserve is that the programs were too small and too incremental to be effective. They have determined that something larger, and potentially permanent, would be more likely to do the trick.

However, in making its new plan public, the Fed made a startling admission. At his press conference, Ben Bernanke backed away from previous assertions that printed money would be effective in directly pushing up business activity. Instead he explained how the new stimulus would be focused directly at the housing market through purchases of mortgage backed securities. He made clear that this strategy is intended to spark a surge in home prices that will in turn pull up the broader economy. Such a belief requires a dangerous amnesia to the events of the last decade. Despite the calamity that followed the bursting of our last housing bubble, economists feel this to be a wise strategy, proving that a poor memory is a prerequisite for the profession.

But now that the Fed is thus committed, the focus has shifted to foreign capitals. Not surprisingly, the dollar came under immediate pressure as soon as the plan was announced. In the 24 hours following the announcement, the Greenback was down 2.2% against the euro, 1.6% against the Australian Dollar, and 1.1% against the Canadian Dollar. A week after the Fed's move, the Mexican Peso had appreciated 2.7% against the US dollar. Many currency watchers noted that more dollar declines would be likely if foreign central banks failed to match the Fed in their commitments to print money. On cue, the foreign bankers responded.

It is seen as gospel in our current "through the looking glass" economic world that a weak currency is something to be desired and a strong currency is something to be disdained. Weak currencies are supposed to offer advantages to exporters and are seen as an easy way to boost GDP. In reality, weak currencies simply create the illusion of growth while eroding real purchasing power. Strong currencies confer greater wealth and potency to an economy. But in today's world,no central banker is prepared to stand idly by while their currency appreciates. As a result, foreign central banks are rolling out their own heavy artillery to combat the Fed.

Perhaps anticipating the Fed's actions, on September 6th the European Central Bank announced its own plan of unlimited buying of debt of troubled EU nations (however, the plan did come with important concessions to the German point of view - see John Browne's commentary). On September 17th, the Brazilian central bank auctioned $2.17 billion of reverse swap contracts to help push down the Brazilian Real. The next day, Peru and Turkey cut rates more than expected. On September 19th, the Bank of Japan increased its asset purchase program from 70 trillion yen to 80 trillion and extended the program by six months. It's clear we are seeing a central banking domino effect that is not likely to end in the foreseeable future.

Although the Fed is directing its fire towards the housing market, the needle they are actually hoping to move is not home prices, but the unemployment rate. Until that rate falls to the desired levels (some at the Fed have suggested 5.5%), then we can be fairly certain that these injections will continue. This will place permanent pressure on banks around the world to follow suit.

All of this simultaneous money creation will likely be a boon for nominal stock and real estate prices. But in real terms such gains will likely not keep pace with dollar depreciation. Inflation pushes up prices for just about everything, so stocks and real estate are not likely to prove to be exceptions. Even bond prices can rise in the short term, but their real values are the most vulnerable to decline. In fact, even nominal bond prices will ultimately fall, as inflation eventually sends interest rates climbing. But prices for hard assets, precious metals, commodities, and even those few remaining relatively hard currencies should be on the leading edge of the upward trend in prices.

While I believe the Fed's plan will be a disaster for the economy, the silver lining is that it provides investors with a road map. As the policy of the Fed is to debase the currency, those holding dollar based assets may seek alternatives in hard assets and in the currencies of the few remaining countries whose bankers have not drunken so freely from the Keynesian Kool-Aid. We believe that such opportunities do exist. Some broad ideas are outlined in the latest edition of my Global Investor Newsletter, which became available for download this week. I encourage those looking for ways to distance their wealth from the policies of Ben Bernanke to start their search today.

Source

October 3, 2012

PricewaterhouseCoopers Paid $1 Billion as Consultant on Mortgage Settlement

Francine McKenna has a useful column in American Banker about the 50 state AG mortgage settlement.
The foreclosure reviews are a “look back” at the past. No one hates admitting and paying for mistakes more than banks. The “independent consultants” selected by the banks in November, after more than six months of contract negotiations, haven’t calculated any final damage numbers yet. It wasn’t until June of this year that, 15 months after the consent orders were signed, regulators finally issued a “financial remediation framework” prepared by the consultants.

Rest assured the consultants are getting paid, even if borrowers are not.
Settlement monitor Joe Smith continues to emphasize strong deference to bank executives. Back in April, Smith said the following.
“If litigation against the banks continues and plaintiffs’ claims continue to contradict what I’m hearing from bank leadership,” Smith says. “I’ve got to pay attention to it.” 
In other words, if bank executives continue to lie to him, he might have to start paying attention to the lies. This is an interesting and important perspective, because it comes from someone who is considered to be on the left side of the aisle. My liberal Democratic sources like Smith; he was the banking commissioner of North Carolina, where Bank of America was headquartered, but he had a reputation as an ally of community banks. He also investigated predatory lending practices, and had a reputation as a fair-minded regulator. He’s part of the left-leaning slice of the financial establishment, and was appointed to head the Federal Housing Finance Agency a few years ago (though the Senate wouldn’t confirm him). Since his appointment to the position as settlement monitor, his behavior has followed the basic template of liberal reformers. He basically supports the existing leadership of the regulatory and banking worlds, while seeking slight modifications of their behavior. For instance, as settlement monitor, Smith chose not to build a public regulatory agency, he chose to build a private one that would not be subjected to Federal pay caps, Freedom of Information Act requests, and ethics and campaign contribution restrictions. This firm (BDO) serves as he put it, as “his eyes and ears and arms and legs” in the banking landscape.
 
Smith also has a deregulatory mindset. Here he is just a few days ago.
“The thing the policymakers need to be discussing is the cost of compliance with a necessarily more rigorous mortgage regulatory system,” he says. “I am not saying it’s wrong to have those costs. But I think the banks are going to reduce the number of loans that they are making and reduce the number of counterparties from whom they buy loans. The level of competition in the marketplace overall” will decrease.

“There is a chance,” Smith says, “that the cost of this will reduce competition in the marketplace, and we don’t know how that will affect the availability and cost of credit in the future.”

Smith figures the standards will be loosened, eventually.

“I think the standards we’ve got are effective to address the abuses we’ve had in the past,” he says. “I am not entirely convinced all of them will be needed going forward and can’t be streamlined over time. But it’s not the time to streamline yet. Let’s get them in place and see what works and what doesn’t.”
According to American Banker, the big banks are going to end up paying “$5 billion to consultants just to find out how much they owe.” That’s a large amount of money, and enough to establish a real temporary public agency that could actually enforce real servicing standards. By way of comparison, the Consumer Financial Protection Agency has a 2013 budget of less than a tenth that. Obviously you can’t scale a massive multi-billion dollar agency that quickly, but you can certainly get something up and running that doesn’t allow the banks to regulate themselves. What is necessary for a regulatory model that doesn’t have the obvious conflicts of interest and lack of accountability or competence so clearly in evidence with the settlement monitor is a new ideological framework that prioritizes adversarial relationships between banks and regulators, and a clearly delineated personnel separation between public and private entities.

Source

October 2, 2012

JPMorgan Sued By NY AG Over "Shit-Breathing" Bear Stearns RMBS Fraud

NY Attorney General Eric Schneiderman is suing JPMorgan over "multiple fraudulent and deceptive acts" in selling mortgage-backed securities causing losses of over $20bn. The suit appears to be related to conduct at Bear Stearns and is on the back of the monoline insurer lawsuits, and whistleblower affidavits such as the following:
In connection with the Bear Stearns Second Lien Trust 2007-1 (“BSSLT 2007- 1”) securitization, for example, one Bear Stearns executive asked whether the securitization was a “going out of business sale” and expressed a desire to “close this dog.” In another internal email, the SACO 2006-8 securitization was referred to as a “SACK OF SHIT” and a “shit breather.”
While we hope this would effectuate some real change, the likelihood is that it will at best result in a $300mm civil-lawsuit slap-on-the-wrists and brownie points for Schneiderman while nothing changes.

JPMorgan is of course contesting the shocking allegations.
  • *JPMORGAN DISAPPOINTED NYAG PURSUING `RECYCLED' PLAINTIFF CLAIMS à NY AG MIRRORS BOND INSURER LAWSUITS
  • *JPMORGAN TO STILL COOPERATE WITH PRESIDENT'S RMBS WORKING GROUP
  • *JPMORGAN COMMENTS ON NYAG CLAIMS IN E-MAILED STATEMENT :JPM US
  • *JPMORGAN SAYS IT INTENDS TO CONTEST NYAG ALLEGATIONS :JPM US
Via NY Times:
The complaint contends that Bear Stearns and its lending unit EMC Mortgage defrauded investors who purchased mortgage securities packaged by the companies from 2005 through 2007. The firms made material misrepresentations about the quality of the loans in the securities, the lawsuit said, and ignored evidence of broad defects among the loans that they pooled and sold to investors.

Moreover, when Bear Stearns identified problematic loans that it had agreed to purchase from a lender, it was required to make the originator buy them back. But Bear Stearns demanded cash payments from the lenders and kept the money, rather than passing it on to investors, the suit contends.

Unlike many of the other mortgage crisis cases brought by regulators such as the Securities and Exchange Commission, the action does not focus on a particular deal that harmed investors or an individual who was central to a specific transaction. Rather, the suit contends that the improper practices were institution-wide and affected numerous deals during the period.

Affidavit of Whistleblower from Clayton + Watterson Prime (Mortgage Due Diligence Firm) in Ambac vs. EMC:
...Many of my colleagues at Clayton also lacked underwriting experience and a number of them had held no previous positions in the mortgage industry. I noticed that many senior Clayton employees, such as Deb Medina, hired many of their family members to work as due diligence underwriters, even when they had no experience in the mortgage industry.

...Because of the time pressures, however, many due diligence underwriters at both Clayton and Watterson entered information directly from the loan application (also known as the "1003 form") or underwriting worksheet (the "1008 form") without verifying the information by examining supporting documentation. This was known as "1008 underwriting." In addition to the time pressures, another reason that many Clayton and Watterson due diligence underwriters engaged in 1008 underwriting was because they lacked the experience to question the information on these forms.

In fact, Clayton leads instructed us not to question what was on the 1008 form: "The loan’s already closed. You can’t do anything about it at this point." I received similar instructions from leads at Watterson, who often told us: "It’s closed. Just approve it and move on, They’re already in the house." From these instructions, I understood that Clayton and Watterson supervisors wanted me to approve loans without questioning any inaccuracies or departures from the underwriting guidelines.

As a result, due diligence underwriters like me knew that we could avoid having supervisors examine our work so long as we graded the loans as 1s. If we graded loans as 2s or 3s, quality control personnel and leads scrutinized our work and, oftentimes, publicly berated us for assigning that grade. Deb Medina, a Clayton lead, frequently yelled at due diligence underwriters for grading loans as 3s in public. Watterson leads instructed us, "Pass the loan and keep it moving." By this I understood that I was supposed to approve loans and could quickly move on to the next loan.

Clayton and Watterson leads instructed us to avoid grading loans as 3s. This was true for numerous clients, but especially true on Bear Stearns jobs... due diligence underwriters at both Clayton and Watterson often used the phrase "Bear don’t care."

...I frequently reviewed loan files that contained documents that appeared to be fraudulent. For example, I reviewed many pay stubs that I believed were fraudulent because they were obviously altered. When I raised this issue to leads at Clayton, they instructed me: "This is not fraud review. Just take it from there." 
Source 
 

October 1, 2012

The Federal Reserve Sends Thank You Letters To Congress For Letting Them Destroy Our Economy In Secret

The Federal Reserve continues to pump up this "bubble economy" by recklessly printing money and by setting interest rates artificially low, and the U.S. Congress continues to stand aside and allow them to systematically destroy our economy. The U.S. Congress could choose to end this madness at any time, but the truth is that Congress won't even pass a law that would allow the American people to see what is going on over at the Federal Reserve. Congress has voted down every single bill that would authorize a comprehensive audit of the Federal Reserve. So the folks over at the Fed will continue to be able to destroy our future in secret. In fact, back in July Federal Reserve Chairman Ben Bernanke actually sent five thank you letters to members of Congress that gave speeches on the floor of the U.S. House of Representatives encouraging their fellow lawmakers to vote against the bill to audit the Fed. Since the U.S. Congress continues to refuse to do anything to hold the Federal Reserve accountable, the Fed will continue to print unprecedented amounts of money, it will continue to set interest rates insanely low and it will continue to pump up the greatest debt bubble in the history of the world. Unfortunately, all debt bubbles eventually burst, and when this one does it is going to be a financial nightmare unlike anything we have ever seen before.

It was Politico that first broke the story about the thank you letters that Federal Reserve Chairman Ben Bernanke sent to five members of Congress back in July. Bernanke acknowledged in the letters that there was never any worry that the "Audit the Fed" bill would actually get through Congress and be signed into law, but he was still extremely grateful that a number of members of Congress got up and publicly denounced the bill....

In July, the Fed chairman sent letters of gratitude to five Democratic members of Congress after they delivered speeches on the House floor urging fellow lawmakers to reject the “Audit the Fed” bill authored by retiring Texas Republican Ron Paul, the central bank’s chief antagonist.

Their efforts failed to defeat the bill, but they were not in vain, at least in Bernanke’s eyes.

“While the outcome of the vote was not in doubt, your willingness to stand up for the independence of the Federal Reserve is greatly appreciated,” Bernanke wrote in the letters, which were obtained by POLITICO through a Freedom of Information Act request.

So who did Bernanke send those letters to?

According to Politico, the thank you letters were delivered to U.S. Representatives Barney Frank, Elijah Cummings, Melvin Watt, Carolyn Maloney and Steny Hoyer.

By refusing to take action against the Federal Reserve, the U.S. Congress is silently endorsing their incredibly foolish policies.

Sadly, most Americans don't even realize that the Federal Reserve has more control over our economy than anyone else does. Most Americans that are actually concerned about politics are busy arguing over whether Obama or Romney will be better for the economy when it is actually the Fed that controls the levers of economic power.

Just think about it.

The Federal Reserve played a major role in creating the housing bubble which severely damaged our financial system a few years ago.

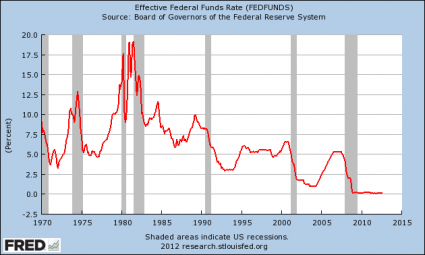
As the chart below shows, after 9/11 the Federal Reserve dropped interest rates to historically low levels. This allowed potential home buyers to get into much larger mortgages, and the big banks (which the Fed supposedly "regulates") started making home loans to almost anyone with a pulse.

When interest rates started to go back up to normal levels in 2005, many home owners discovered that their adjustable rate mortgages started to become much more painful. By 2007, we started to see a massive wave of mortgage defaults. In 2008, the financial system crashed.

In response to the financial crisis of 2008, the Federal Reserve dropped interest rates to record low levels. The effective federal funds rate is essentially at zero at this point, and the Fed has promised to keep interest rates at ultra-low levels all of the way into 2015.

But didn't artificially low interest rates cause many of our problems in the first place? The central planners over at the Fed are convinced that this is the right course for our economy, but can we really live in a zero interest rate bubble indefinitely? Won't this eventually cause even greater problems?....


The Fed is also destroying our economy by recklessly printing money.

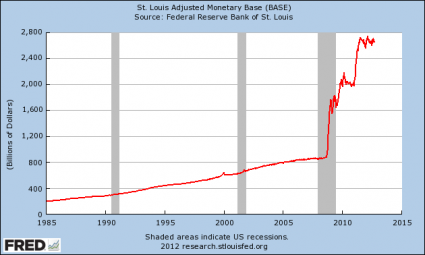
Once upon a time, the U.S. monetary base rose at a very steady pace. But since the financial crisis of 2008, Ben Bernanke has been flooding the financial system with money and this has caused an unprecedented explosion in our money supply.

It isn't too hard to see from this chart what the foolish "quantitative easing" policies of the Federal Reserve have done to our monetary base....


Fortunately a lot of the money from previous rounds of quantitative easing is being stashed by the big banks as "excess reserves" with the Federal Reserve, but when that money starts flowing into the "real economy" (and it will at some point), we are going to have a major problem on our hands.

But more than tripling our monetary base was not enough for Bernanke. He recently announced yet another round of quantitative easing which he says will last indefinitely.

Basically, Bernanke is taking a sledgehammer to the U.S. dollar. Our currency is being systematically destroyed, and the U.S. Congress is standing by and doing nothing.

For a lot more on why QE3 is going to be so incredibly destructive for our economy, please see the following five articles....

-"QE3: Helicopter Ben Bernanke Unleashes An All-Out Attack On The U.S. Dollar"

-"How QE3 Will Make The Wealthy Even Wealthier While Causing Living Standards To Fall For The Rest Of Us"

-"The Federal Reserve Is Systematically Destroying Social Security And The Retirement Plans Of Millions Of Americans"

-"QE4? The Big Wall Street Banks Are Already Complaining That QE3 Is Not Enough"

-"Quantitative Easing Did Not Work For The Weimar Republic Either"

The Federal Reserve seems to think that printing more money is always the solution to whatever economic problems we are having.

But of course the Fed has been debasing our currency from the very beginning. The entire Federal Reserve system is designed to create inflation.

From the time that the Federal Reserve was created back in 1913, the purchasing power of a U.S. dollar has declined from $1.00 to only about 4 pennies today.

And now Bernanke seems bound and determined to wipe out those last 4 pennies.

The Federal Reserve system was also designed to create a never ending spiral of government debt.

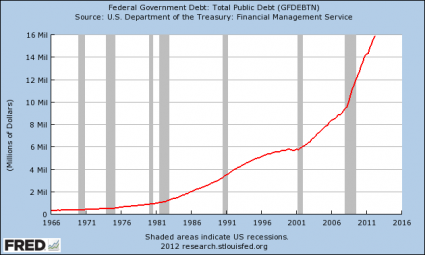
Sadly, most Americans simply have no idea where money comes from. Most Americans have no idea that money that the Federal Reserve zaps into existence out of thin air is loaned to the U.S. government at interest. Most Americans have no idea that the primary reason why we are 16 trillion dollars in debt is because this is what the system was designed to do to us.

Today, the U.S. national debt is more than 5000 times larger than it was when the Federal Reserve was originally created in 1913. This did not happen by accident....
Not that our politicians should be off the hook for this. They have been spending money as if there is no tomorrow. Most of them have shown no concern at all about the legacy of debt that they are passing on to future generations of Americans.

If our politicians had been more responsible, the national debt would still be there, but it would be at a much more manageable level.

If we ever want to totally get rid of our national debt, the Federal Reserve must be abolished.

There is no other way.

And government debt is not the only bubble that the Federal Reserve has pumped up.

The following is a chart that shows the growth of all forms of debt (government, business, consumer, etc.) in the United States. The total amount of debt in the United States has grown from less than $2 trillion to more than $55 trillion over the past 40 years....


How in the world could we have been so foolish?

How in the world did we allow the total amount of debt in our country to get more than 27 times larger over the past 40 years?

As you can see, there was a slight "hiccup" in the bubble as a result of the financial crisis of 2008, but now it has started growing again.

At this point our entire financial system is based on debt, and if the debt bubble does not continue to expand the entire thing will collapse.

But no financial bubble grows forever. History has proven that to us over and over.

At some point this bubble is going to burst.

When it does, we will either experience a deflationary collapse or a hyperinflationary collapse depending on how "the powers that be" respond to what is happening.

History has shown us that financial collapse is often accompanied by social upheaval. Many times it even leads to war.

So what will happen to America when our economic collapse happens?

That is a very good question.

How would you answer it?

September 28, 2012

Libor Scandal May Be Tricky for U.S. Prosecutors

It has been called the largest financial scandal in history, a web of alleged white-collar malfeasance spanning several continents while hitting portfolios and pocketbooks from Wall Street to Main Street.
But U.S. prosecutors may be hesitant to launch criminal proceedings against large financial institutions for alleged manipulation of the Libor, a key interbank borrowing rate that affects an estimated $360 trillion in financial contracts worldwide, economists and securities experts say.

Ever since the crash of Lehman Brothers four years ago prompted the U.S. government to rescue the country’s largest financial institutions with taxpayer money, U.S. authorities are hesitant to “do something that might make one of these banks fail,” said Stephen Bainbridge, a securities regulation expert at UCLA Law School.

All eyes in the financial world on Friday will be trained on London, where Martin Wheatley, Britain’s top financial regulator, is set to issue recommendations for regulatory reforms to prevent manipulation of the Libor, which is used by lenders to set interest rates for all manner of investments, from municipal bonds to mortgages to credit cards.

“Anybody who has any investment in financial markets has been affected by the Libor fraud,” Bainbridge said. “Over half of the American population own stocks—whether directly or through a mutual fund—so it has affected most people.”

The London Interbank Offered Rate, or Libor, is the average interest rate at which top banks estimate they would borrow money from other banks. This rate, which is adjusted daily, is used as the benchmark used to set interest rates for a wide range of financial products and commercial markets across the globe.

Wheatley’s announcement comes after months of allegations, resignations, and lurid evidence pointing at possible collusion among the banks to manipulate the rate in order benefit their trading arms.

British bank Barclays in June admitted that its traders had encouraged the bank to rig the rate in order to benefit their financial positions, paying a $470 million fine to U.S. and British authorities to settle the charges.

Wheatley’s report Friday is unlikely to include scores of smoking guns pointing to such collusion, but if it does contain instances of “trader-to-trader contact in which one is asking the other to help him push Libor up or down, that would be of great interest to U.S. criminal authorities,” said John Coffee, a prominent securities law expert at Columbia Law School.

The 18 banks that set the Libor for the U.S. dollar include financial behemoths such as Bank of America, Citibank, JP Morgan Chase, and Deutsche Bank.

Should evidence of collusion to rig rates at these institutions emerge, the U.S. Justice Department may target individual executives for criminal prosecution rather than go after the financial entity itself, said Robert Shapiro, a former undersecretary of commerce for economic affairs under the administration of U.S. President Bill Clinton.

“So far the Justice Department has not been willing to put any of the large financial institutions in that particular box,” Shapiro said. “I’d be surprised.”

Opting to forgo criminal prosecution if there is clear evidence of wrongdoing risks sending a “wrong signal that if an institution is large enough, and important enough, it’s not going to be criminally charged,” said Rosa M. Abrantes-Metz, a financial regulation expert with Global Economics Group in New York City and an adjunct associate professor at New York University’s Leonard N. Stern School of Business.

But “criminally charging institutions, particularly in the financial sector—given the instability there—can be very complicated,” she said.

Even in the absence of criminal charges, the largest U.S. financial players face a possible avalanche of civil litigation over the Libor-rigging accusations.

In July, New York-based Berkshire Bank filed a complaint in federal court against more than a dozen banks in connection with the allegations, citing the “tens, if not hundreds, of billions of dollars of loans” that “are originated or sold within this state each year with rates tied to Libor.”

Dozens of other suits have been filed in the United States in connection with the alleged rate-fixing. Plaintiffs in these cases, however, will have to do the math on whether the eventual payoff is worth the effort.

The banks involved in setting Libor “have enormous resources to fight these suits,” Shapiro said.

Source

September 27, 2012

RBS traders boasted of Libor 'cartel'

Senior traders at Royal Bank of Scotland boasted about operating a “cartel” that made “amazing” amounts of money by rigging interest rates, it has been disclosed.

Internal messages revealed in court documents apparently show how traders claimed they could manipulate Libor, which is used to set borrowing costs for millions of businesses, consumers and investors.

The messages, some sent just months before the taxpayer was forced to bail out RBS at a cost of more than £40bn, suggest the practice was condoned and encouraged by senior executives at the bank, and have now dragged the taxpayer-backed lender to the heart of the Libor scandal.

MPs have warned that the scale of RBS’s involvement in the scandal means it could face an even bigger fine than Barclays, which paid a record £290m in July after admitting attempting to manipulate Libor. The bank could also be hit with billions of pounds in damages claims.

Tan Chi Min, a former senior trader at RBS’s global banking and markets division in Singapore, has alleged that managers “condoned collusion” between staff to maximise profits by rigging Libor.

Mr Tan, who worked for RBS from August 2006 to November 2011, was eventually sacked for gross misconduct, but claims the bank made him a “scapegoat” for malpractice condoned by managers.